


How Activist Pressure At M3 Shares Has Changed Its Investment Story
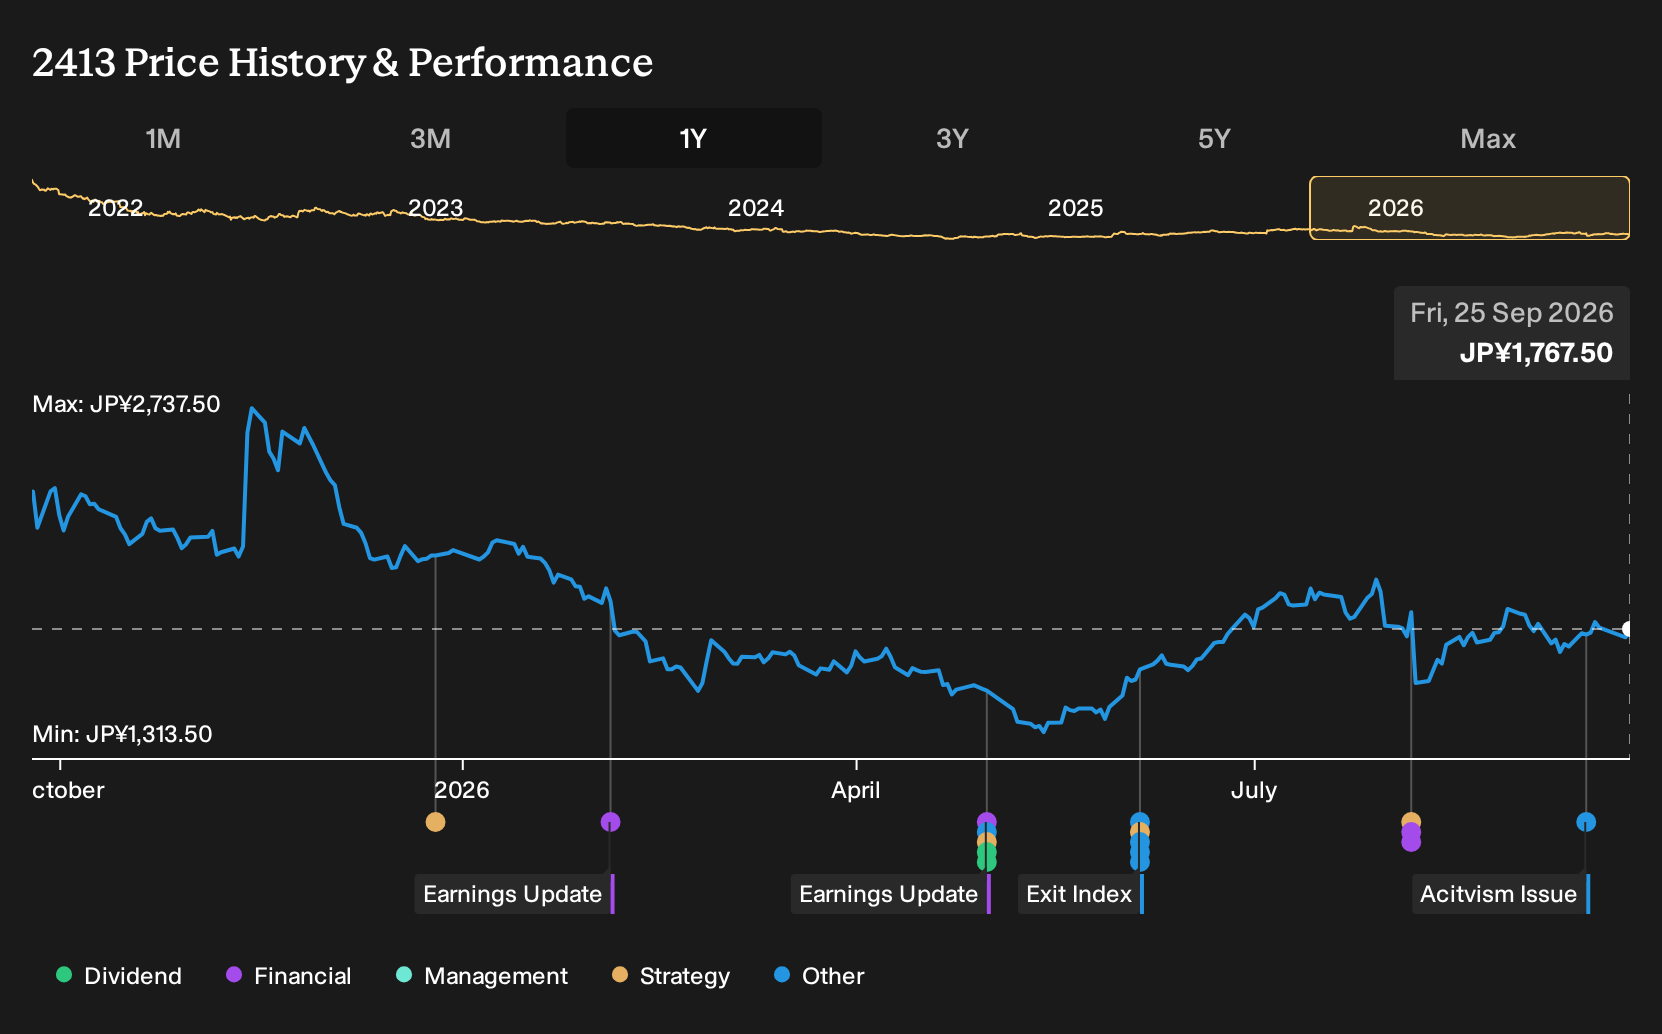
- On 15 September 2026, Oasis Management engaged M3 in activist talks on delisting options, capital policy shifts, potential control change and plans to lift its stake above 5% if M3’s share price is viewed as undervalued.
- The activist’s agenda targets core levers of M3’s corporate governance, including possible leadership changes, board reshaping, dividend policy revisions and business portfolio moves that could reshape the firm’s operating profile.
- The next step is to examine how M3’s investment narrative could be reshaped by Oasis pushing for wide ranging governance and capital changes.
What Is M3's Investment Narrative?
M3 lives or dies on execution in its healthcare internet platform, recruitment, and data services. You would need to believe that doctors and medical institutions keep relying on its tools, that pharma and device clients continue to pay for access, and that management can turn forecast revenue and earnings growth into solid cash generation without heavy new capital needs. The share price has fallen about 19% over the past year despite forecasts for earnings and sales to rise faster than the wider JP market, so the core question is whether this business model is just temporarily out of favour or structurally less attractive than it looks.
The Oasis Management activism drops straight into that debate. It targets governance, capital policy, and even a possible change of control, which could affect key near term catalysts like buyback or dividend decisions and the shape of M3’s portfolio. Operationally, nothing in the communication suggests an immediate shock to demand or pricing. The bigger risk is distraction at the top just as profit growth has recently improved and return on equity is still described as low.
Even so, there is a single fault line in the M3 story that this activist push brings into sharper focus...
There's only one way to know the right time to buy, sell or hold M3. Head to Simply Wall St's company report for the latest analysis of M3's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your M3 research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for M3. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M3's overall financial health at a glance.
Looking For More Ideas Beyond M3?
If the M3 story has you thinking about where else inefficiencies or mispricings might exist, it can help to scan a wider field of opportunities using structured filters rather than gut feel alone.
The Simply Wall St Screener lets you do exactly that. You can quickly sift through hundreds of companies by quality, balance sheet strength, income potential, and more, and then drill into the ones that fit your own criteria best.
- For investors hunting for potential mispriced quality, start with a focused set of companies that screen as financially strong and potentially underappreciated through 18 high quality undervalued stocks.
- If capital preservation and balance sheet resilience matter most to you, filter for businesses with robust financial footing using this list of solid balance sheet and fundamentals (22 results).
- Income focused investors can zero in on higher yielding opportunities and assess whether those payouts look supported by fundamentals with a curated group of 14 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com