


AEON REIT Investment (TSE:3292) Has Investors Asking A Bigger Question
AEON REIT Investment stock moves after index exit and dividend signal
AEON REIT Investment (TSE:3292) has come under fresh scrutiny after its removal from the FTSE All-World Index, alongside new guidance flagging lower distributions per unit compared with the previous year for upcoming fiscal periods.
Recent trading has been weak for AEON REIT Investment, with the share price at ¥112,600 after a 30 day share price return that fell 6.48% and a year to date share price return that declined 18.29%, while the 1 year total shareholder return is down 9.61%.
The index exit and lower distribution guidance arrived soon after half year earnings on 14 September 2026. The earnings report showed revenue of ¥21,438.11 million and net income of ¥5,968.96 million. Together, these updates appear to have shifted how investors are pricing income risk and future cash flows.
Compare AEON REIT Investment's recent index removal and lower payout guidance with other income-focused options by scanning our curated list of 14 dividend fortresses for potential alternatives.
AEON REIT Investment still owns a fully occupied portfolio of community retail assets, yet the index exit and lower distribution outlook have reset sentiment. The real issue now is whether today’s price fairly reflects that mix.
Preferred P/E of 18.5x for AEON REIT Investment: Is it justified?
Valuation screens show AEON REIT Investment trading on a P/E of 18.5x, which sits above both its direct peer group and the wider Asian Retail REITs cohort, even with the last close at ¥112,600 and a discounted share price relative to analyst targets.
The P/E ratio compares the current unit price with earnings per unit. It effectively tells you how many years of current profits investors are willing to pay for. For a REIT such as AEON REIT Investment, that matters because distributions are closely linked to underlying income generation and the stability of that cash stream.
Here, the picture is mixed. The SWS DCF model flags the units as trading 39.1% below an estimated fair value of ¥184,755.61, and past earnings are described as high quality with 1.5% yearly profit growth over the past 5 years. At the same time, earnings declined 8.2% over the last year, net profit margins eased from 32.6% to 29.9%, Return on Equity is a modest 5.3%, and the 5.53% distribution yield is not well covered by earnings.
Compared with other Retail REITs, the premium looks clear. AEON REIT Investment carries a P/E of 18.5x against a peer average of 18.1x and a wider Asian Retail REITs industry average of 13x. That means investors are paying more for each yen of current earnings than the sector norm even though 1 year total returns have fallen short of both the JP market and the Retail REITs group.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 18.5x (OVERVALUED).
Still, AEON REIT Investment faces a lower distribution outlook and index exclusion, which could keep income focused buyers cautious and liquidity conditions tight.
Find out about the key risks to this AEON REIT Investment narrative.
Another View on AEON REIT Investment's Value
The headline P/E of 18.5x makes AEON REIT Investment look expensive, yet the SWS DCF model points the other way, with an estimated fair value of ¥184,755.61. This suggests the units trade 39.1% below that figure. If both signals are right, what exactly is the market pricing in?
Look into how the SWS DCF model arrives at its fair value.
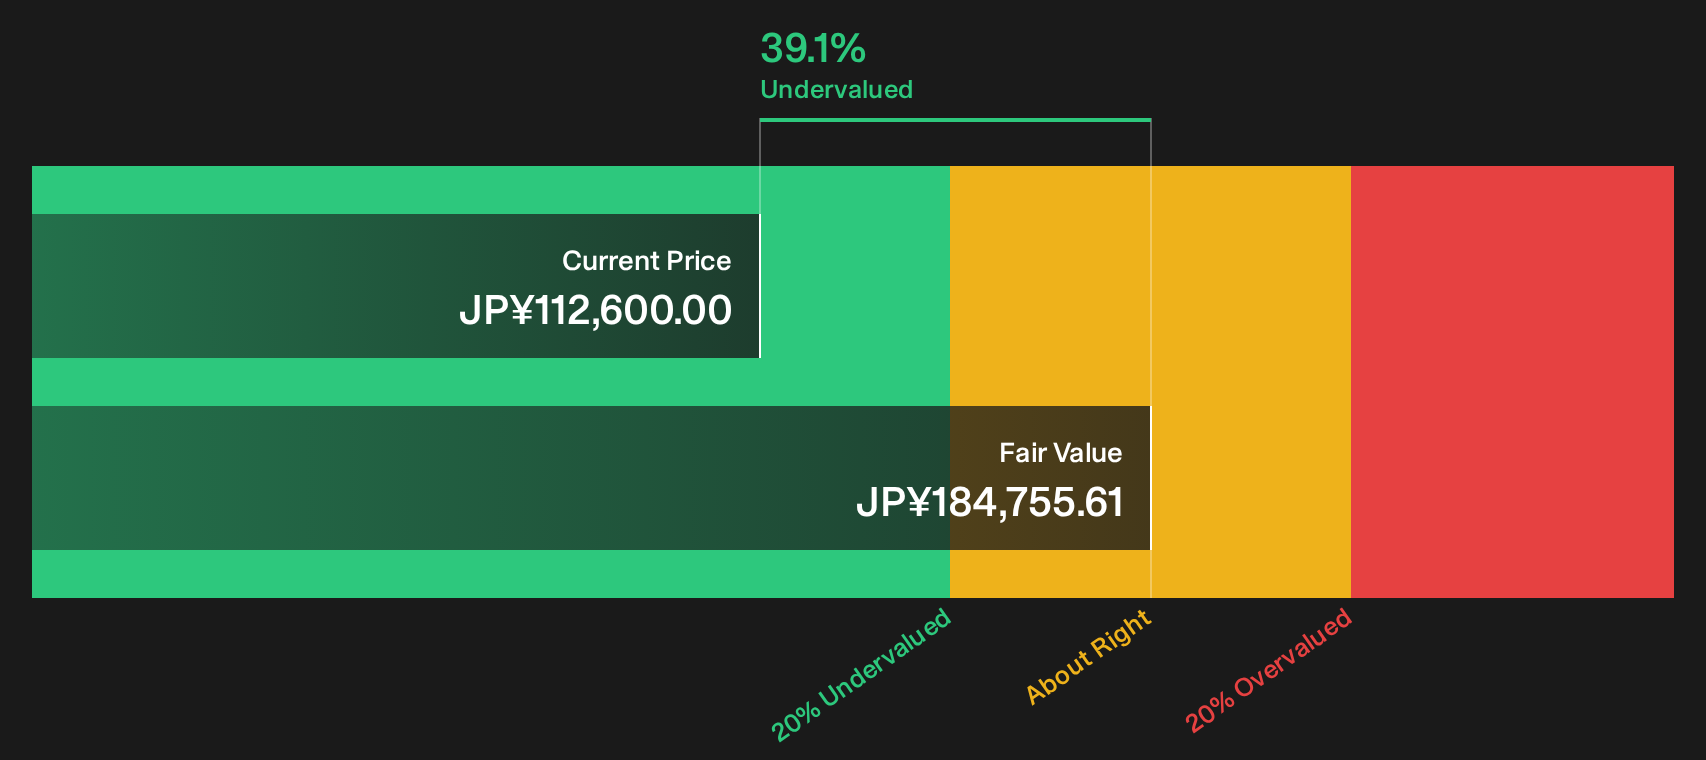
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AEON REIT Investment for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 18 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around AEON REIT Investment is clearly split, which is exactly why independent analysis matters most right now. Move quickly, look through the full picture, and weigh both sides by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond AEON REIT Investment?
AEON REIT Investment may be front of mind right now, but you give yourself far more flexibility when you line it up against other clear opportunities.
Use the Simply Wall St screener to pressure test your thinking against focused sets of ideas that match different goals and risk levels.
- Chase value by lining up AEON REIT Investment against companies that screen as potential bargains using our 18 high quality undervalued stocks.
- Stress test stability by comparing it with a list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions without stretching their finances.
- Hunt for overlooked potential with a 74 high quality undiscovered gems that have strong fundamentals but limited investor attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com