


Mycronic (OM:MYCR) Could Be 9% Undervalued On Hprobe And RoBAT Deals
Recent acquisitions of Hprobe and RoBAT put Mycronic (OM:MYCR) in sharper focus, as the electronics equipment supplier moves to expand MRAM and PCB testing within its Global Technologies division.
The share price of Mycronic has climbed to SEK334.0, with a 7 day share price return of 4.38% and a 90 day share price return of 9.29%. The year to date share price return of 54.20% sits alongside a 5 year total shareholder return of 225.58%. This points to strong momentum that recent Hprobe and RoBAT deals could be helping to reinforce, as investors reassess both growth potential and risk around future orders.
Scan how Mycronic’s acquisition driven momentum compares with other high quality electronics and semiconductor suppliers by reviewing our hand picked list of 620 high quality undiscovered gems.
Mycronic looks like a high quality equipment supplier with fresh deal momentum behind it. The harder question is whether a SEK334 share price already reflects that strength or leaves any valuation headroom.
Most Popular Narrative: 4% Overvalued
On the most followed view of Mycronic, a fair value of about SEK321.7 sits a little below the SEK334 last close. This frames the recent deal momentum against slightly richer pricing assumptions built on a 6.98% discount rate.
The analysts have a consensus price target of SEK321.67 for Mycronic based on their expectations of its future earnings growth, profit margins and other risk factors.
In order for you to agree with the analysts, you would need to believe that by 2029, revenues will be SEK12.6 billion, earnings will come to SEK2.9 billion, and it would be trading on a PE ratio of 26.3x, assuming you use a discount rate of 7.0%.
See why 9 investors see Mycronic as 4% overvalued.
Result: Fair Value of SEK321.67 (OVERVALUED)
Still, tariffs hitting High Flex deliveries and softer European demand, along with currency swings, could easily disrupt the Mycronic consensus story that investors are leaning on.
Find out about the key risks to this Mycronic narrative.
Another View On Mycronic’s Valuation
The consensus target frames Mycronic as about 4% above fair value at SEK321.7, yet the SWS DCF model points the other way. On that cash flow view, Mycronic at SEK334 trades roughly 8.6% below an estimated value of SEK365.52, which reads as undervalued rather than fully priced.
These are two different methods that lead to two different answers. The question for you is which set of assumptions feels closer to how Mycronic will actually convert its order book into long term cash generation, and whether that mismatch in outcomes is worth acting on.
Look into how the SWS DCF model arrives at its fair value.
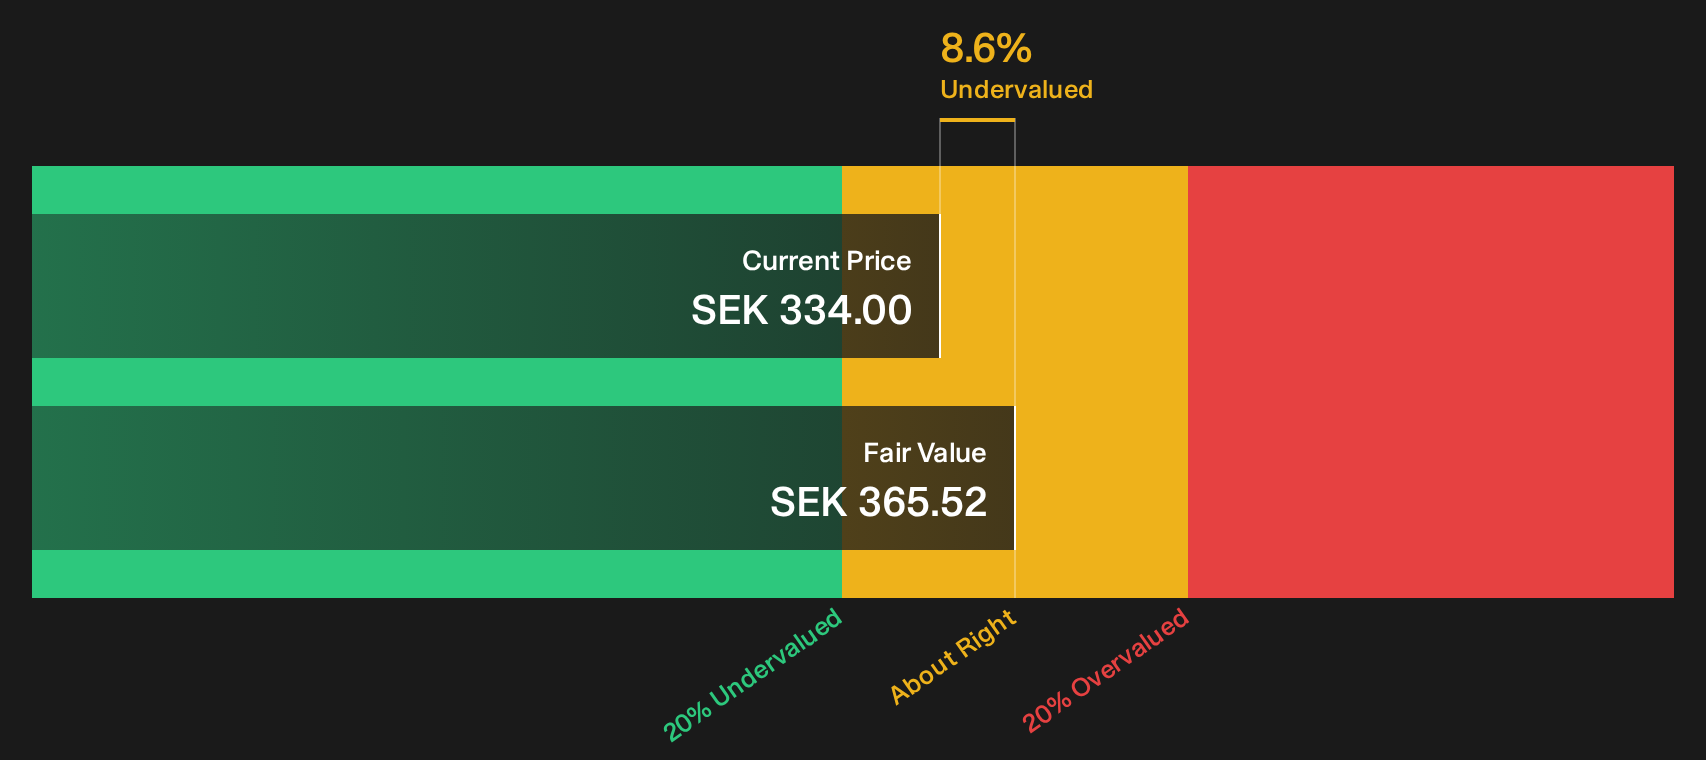
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mycronic for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Mycronic leaves you on the fence, move quickly, check the underlying numbers yourself, and weigh the 2 key rewards.
Looking for more investment ideas beyond Mycronic?
Ready to broaden your watchlist beyond Mycronic and spot other opportunities before the crowd does? Use the tools below to pressure test your next move.
- Target resilient balance sheets and dependable fundamentals by scanning a curated list of solid balance sheet and fundamentals (202 results) that can help reduce unpleasant financial surprises.
- Hunt for potential mispricing by checking a focused 181 high quality undervalued stocks that flags companies where quality and current pricing may be out of sync.
- Prioritise peace of mind by working through a 228 resilient stocks with low risk scores tailored to businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com