


YIT Oyj (HLSE:YIT) Could Be 55% Overvalued On Its Latest Data Center Deal
YIT Oyj (HLSE:YIT) just expanded its data center work in Kajaani after agreeing with XTX Markets on interior finishing, building services engineering, and commissioning for the site’s third facility.
Investors have been leaning into YIT Oyj’s recent momentum, with the share price up 5.30% over 1 day, 13.25% over 7 days and 26.85% over 30 days. The 1-year total shareholder return of 47.72% and 3-year total shareholder return of 105.13% reflect strong longer term gains.
Scan how YIT Oyj's data center momentum compares with other contractors riding similar infrastructure trends by reviewing the hand picked 87 AI infrastructure stocks.
The recent surge in YIT Oyj raises a sharper issue. Is this data center contract win the start of more upside, or has the share price already pulled most of that forward into today’s valuation?
Price-to-Sales of 0.6x: Is It Justified for YIT Oyj?
Valuation on YIT Oyj looks compressed, with the stock trading on a P/S of 0.6x while peers sit closer to 1.8x and an estimated fair level of 3.4x, even after the recent rally to €4.28.
The P/S ratio compares the market value of the equity to its annual revenue, so it effectively tells you how much investors are paying for each euro of YIT Oyj's sales. For a construction and infrastructure contractor where earnings can be cyclical and occasionally loss making, revenue based measures often give a cleaner read on how the market is treating the underlying activity.
Here that read is clear. The share price implies a discount to both direct peers and the fair P/S level that regression analysis points to. This suggests the market is pricing YIT Oyj's current losses, unprofitable track record and interest coverage issues more harshly than its revenue profile and growth forecasts alone would indicate. If sentiment or profitability move closer to those fair ratio assumptions, the gap in that multiple is the kind of thing the market could eventually close.
Explore the SWS fair ratio for YIT Oyj.
Result: Price-to-sales of 0.6x (UNDERVALUED)
Still, the story can break if YIT Oyj’s current loss making position persists or if construction demand cools across its key Nordic and CEE markets.
Find out about the key risks to this YIT Oyj narrative.
Another View: SWS DCF Model Paints YIT Oyj As Expensive
The P/S workup points to YIT Oyj looking cheap, yet our DCF model pulls in the opposite direction. On that measure, the share price of €4.28 sits above an estimated future cash flow value of €2.76. That gap leans toward overvaluation and puts more weight on execution risk if cash flows disappoint.
Look into how the SWS DCF model arrives at its fair value.
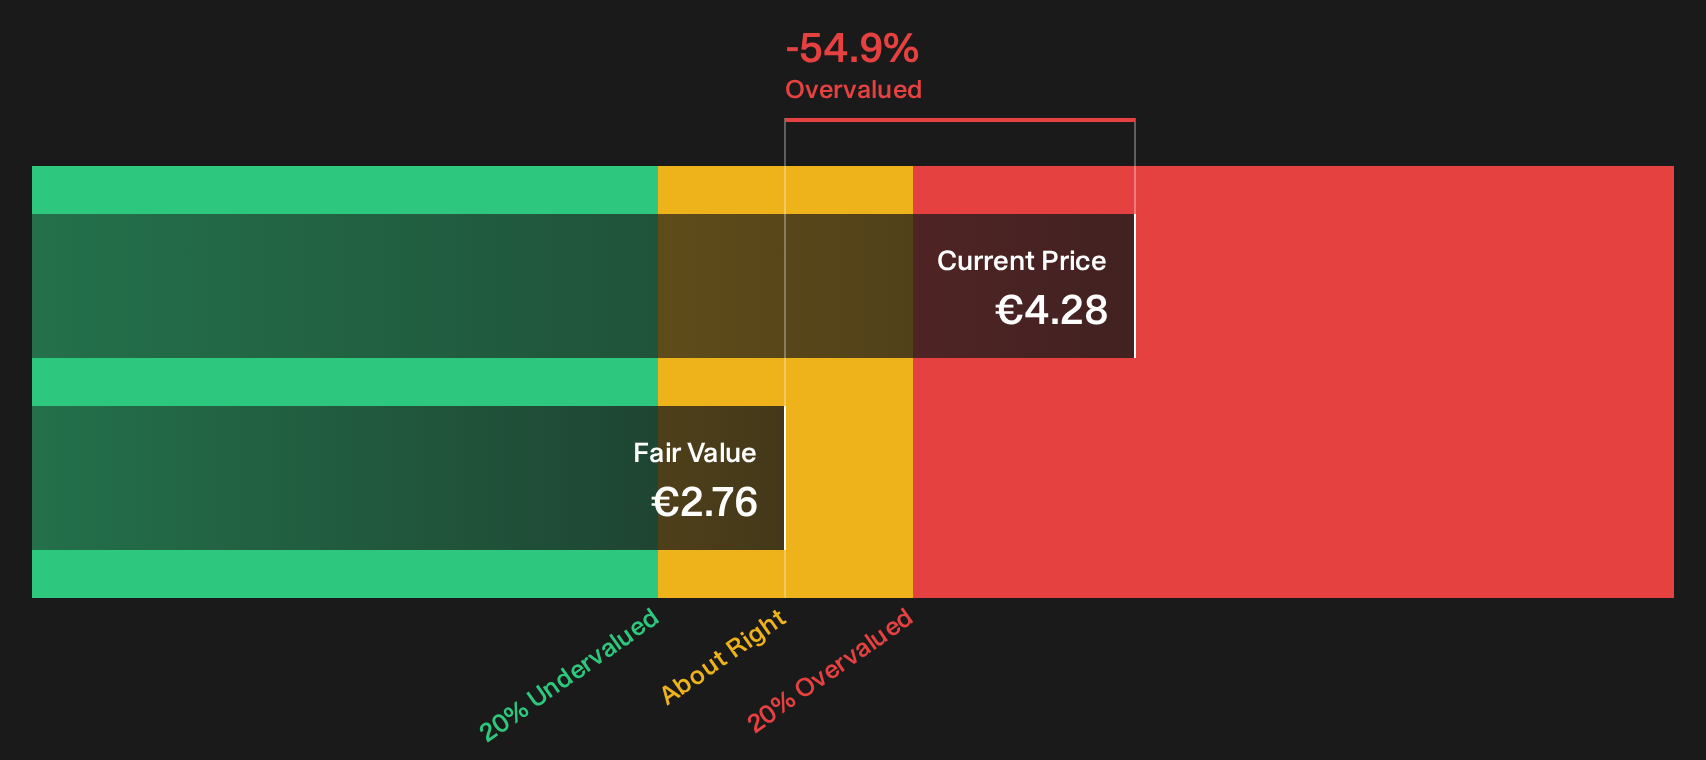
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out YIT Oyj for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 181 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on YIT Oyj so far, right. If you want to cut through the noise and weigh both sides properly, start with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond YIT Oyj?
If YIT Oyj has you thinking more broadly about where to put fresh capital to work, do not stop at a single construction stock. Widen your net with focused stock lists that surface clear themes and let the data do the heavy lifting for you.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (202 results).
- Hunt for quality at a discount by reviewing the 181 high quality undervalued stocks.
- Lock onto future potential early by checking the 620 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com