


Does Satellite Launch Success Change The Bull Case For Sirius XM Stock (SIRI)?
- Sirius XM Holdings reported that its SXM-11 satellite is now fully operational after in-orbit testing. The satellite adds high-powered capacity to improve reception, broaden Alaska coverage and support satellite-delivered audio and data services across roughly 8 million square miles in North America.
- The SXM-11 activation shows Sirius XM Holdings continuing its fleet-refresh program. The program aims to support 210 million SiriusXM-equipped vehicles and maintain reliability in a business where satellite uptime, coverage quality and infrastructure redundancy directly affect subscriber experience and churn risk.
- We will now examine how Sirius XM Holdings' investment narrative could be influenced by the SXM-11 satellite becoming fully operational.
Scan beyond Sirius XM Holdings and find other companies leaning on critical infrastructure with our hand-picked list of solid balance sheet and fundamentals (24 results) to support their long-term service commitments.
Sirius XM Holdings Investment Narrative Recap
For an investor to back Sirius XM Holdings, the core belief is that its subscription and advertising engine can stay relevant as listening habits tilt toward on-demand apps. The SXM-11 launch speaks to reliability rather than growth. It supports coverage and uptime, which matters for churn, but it does not directly change near term revenue pressure from a shrinking subscriber base.
The more immediate swing factor still sits with execution on new offerings like ad-supported plans, cross platform engagement and keeping content costs in check. The biggest current risk remains heavy exposure to the auto channel combined with high fixed satellite and debt loads, which leave less room if subscriber trends weaken further.
The SiriusXM Play ad supported plan is the announcement that ties most cleanly into this satellite upgrade story. SXM-11 helps keep the in car experience consistent across roughly 210 million SiriusXM equipped vehicles, while Play targets price sensitive listeners in up to 100 million vehicles. Together they speak to monetizing both premium and lighter usage tiers.
For you as a shareholder, the operational question is whether Sirius XM Holdings can use this broader reach plus lower entry pricing to offset competition from tech rivals and changing audio habits. Execution risk is real. The firm still faces rising content and acquisition costs, and the payoff from these plans depends on keeping churn contained while managing margins.
Sirius XM Holdings is projected to reach US$8.9b in revenue and US$1.2b in earnings by 2029, based on analyst estimates that incorporate 1.3% yearly revenue growth and an earnings increase of about US$354m from US$846.0m today.
Uncover why Sirius XM Holdings' fair value indicates a 9% potential upside to its current price that could narrow quickly.
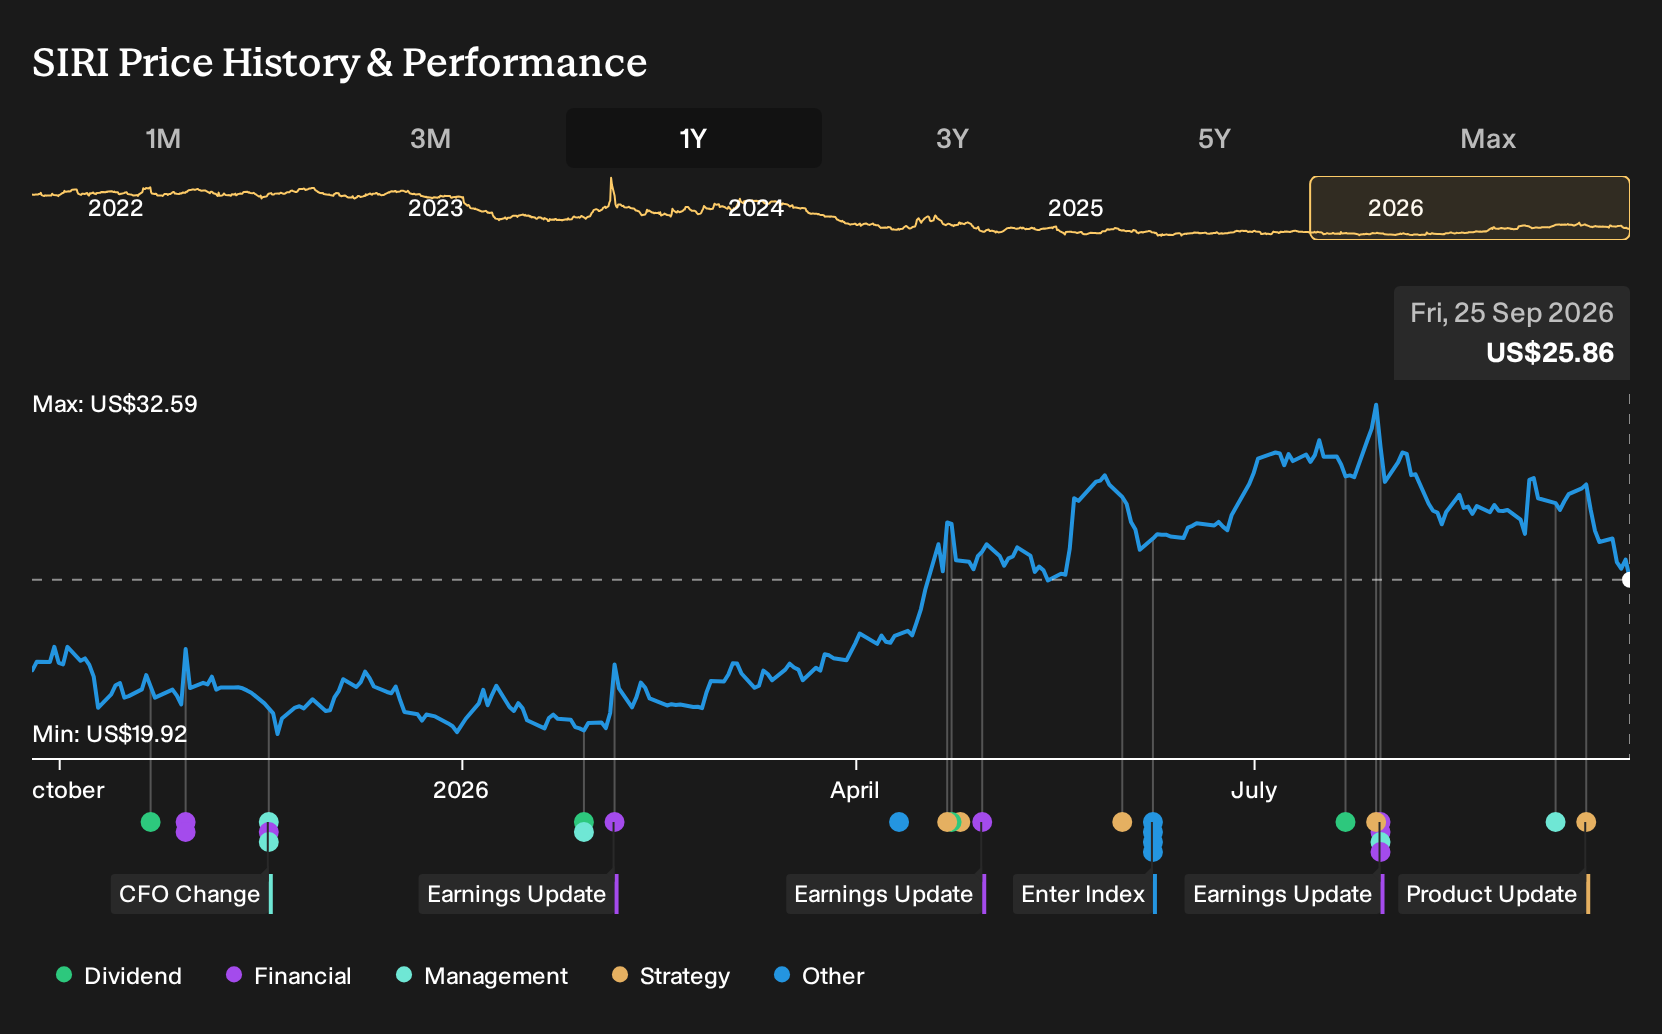
Exploring Other Perspectives
Some of the most optimistic analysts on Sirius XM Holdings focus less on churn risk and more on monetization upside. Before this SXM-11 news, the bullish camp was modeling revenue climbing to about US$10.2b and earnings to roughly US$1.3b by 2029. You can treat SXM-11 as a fresh test of those higher expectations.
Explore 7 other Sirius XM Holdings fair value estimates, including one that suggests as much as 77% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Sirius XM Holdings research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Sirius XM Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sirius XM Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Sirius XM Holdings?
If Sirius XM Holdings has you thinking about where resilient cash flows and solid balance sheets might matter most, it can help to line it up against a wider set of businesses that share similar financial traits.
- For investors who care most about balance sheet strength and durable fundamentals, scan our curated list of solid balance sheet and fundamentals (24 results) to filter for financial resilience up front.
- If you are hunting for quality that the broader market may be overlooking, sort through 16 high quality undiscovered gems and see which stories are still flying under the radar.
- When capital preservation sits high on your list, start with 31 resilient stocks with low risk scores to focus on companies that screen well on lower risk scores before you dig any deeper.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com