


3 British Undervalued Stocks With Discounts Up To 44%
Government bond markets have been hit by sharp moves, with the 10 year US Treasury yield above 5%, and that kind of spike often drags valuations lower for many UK shares that throw off steady cash. When prices adjust faster than underlying cash generation, mispricing can appear. This piece breaks down three undervalued British stocks where current cash flow estimates suggest the share price may not fully reflect the business.
The three UK stocks covered next are only a small sample from this idea, and the full screen surfaced 10 additional businesses with similarly cash rich stories not included below. To size up the wider opportunity set, head straight to the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze the highest conviction candidates.
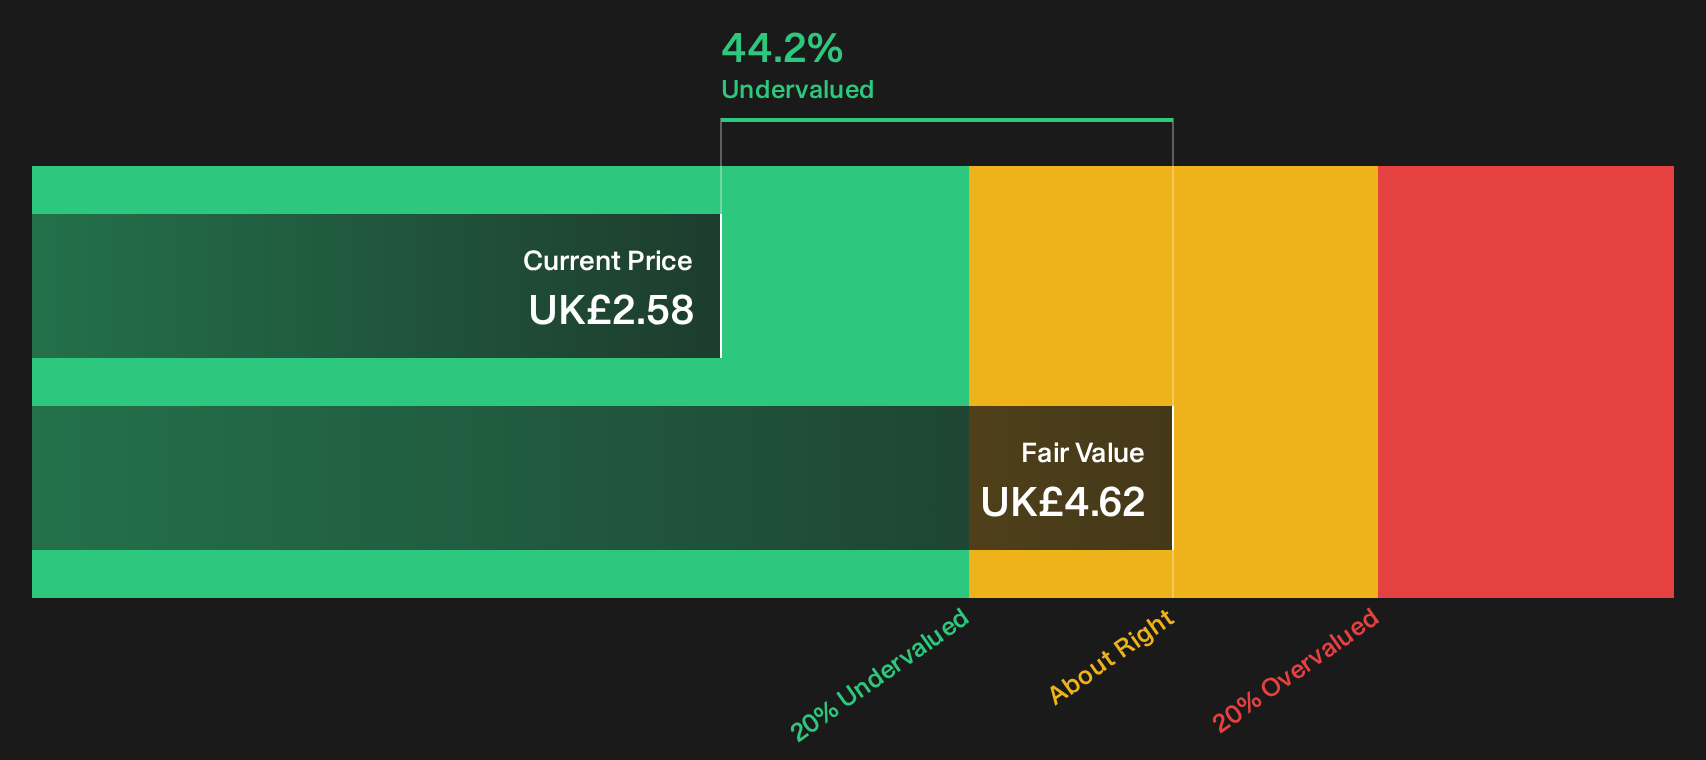
LSL Property Services (LSE:LSL)
Overview: LSL Property Services runs a capital light, UK focused platform for mortgage advice, surveying and valuations, and franchised estate agency services.
Operations: The group generates about £110.7 million from Surveying and Valuation, £48.2 million from Financial Services and £26.7 million from Estate Agency, all in the UK.
Market Cap: £254 million
LSL Property Services matters for this undervalued cash flow screen because its surveying and valuation arm produces recurring fees that plug directly into discounted cash flow models, giving you clearer testable assumptions than many more cyclical property related stocks.
"Structural growth in the private rental sector, supported by LSL’s program of lettings book acquisitions for franchisees, is expanding high visibility, recurring income streams that can smooth cyclicality in housing transactions and support group revenue resilience and net margins."
The real swing factor is whether one still developing revenue engine can carry enough weight to keep those margins moving in the right direction.
If that engine delivers, full narrative for LSL Property Services unpacks how LSL Property Services’ recurring fees, cost base and capital light model could be decoupling from traditional housing cycles.
AltynGold (LSE:ALTN)
Overview: AltynGold is a London headquartered miner that owns and operates the Sekisovskoye gold mine and Teren-Sai projects in Kazakhstan.
Operations: The business generates about $175 million from exploration and development of the Sekisovskoye gold asset in the Republic of Kazakhstan.
Market Cap: £294 million
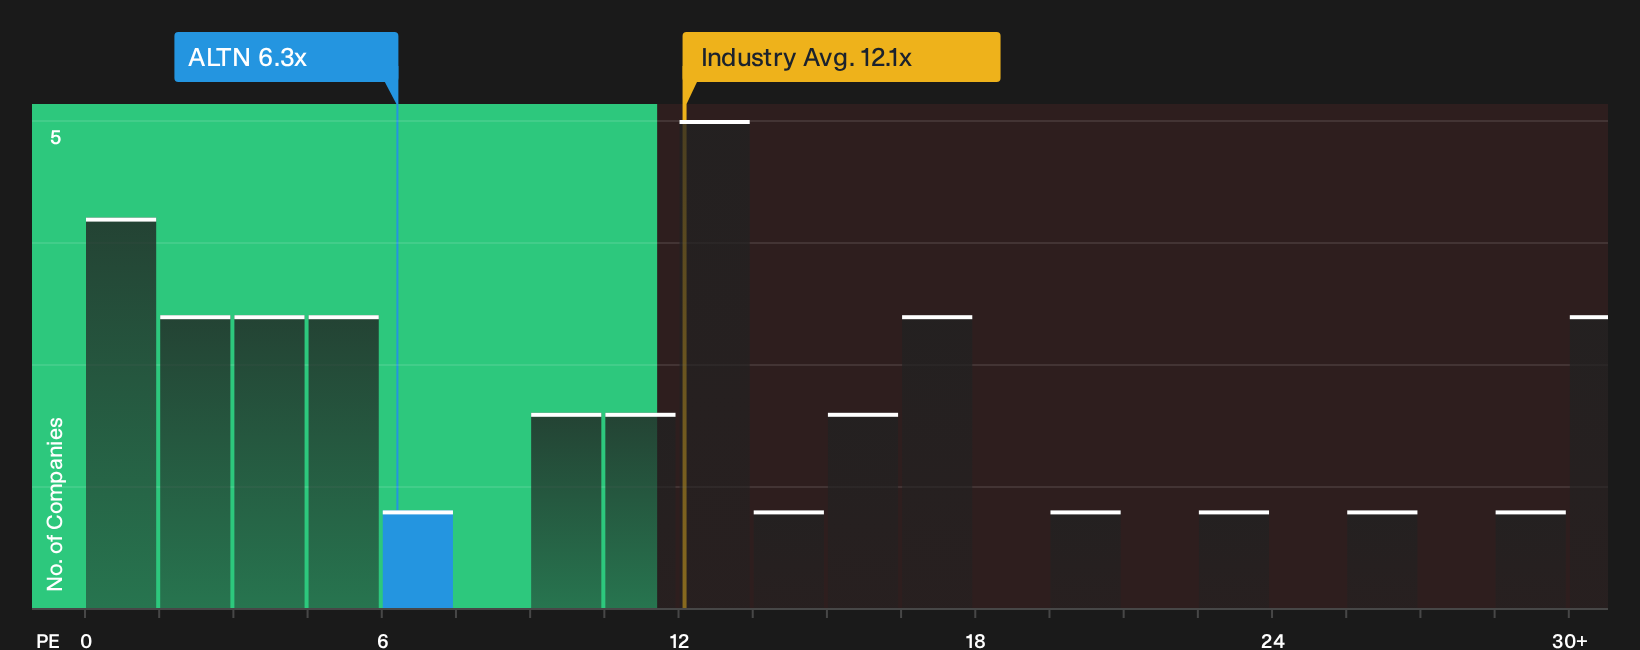
AltynGold fits into this cash flow focused screen because the Sekisovskoye gold mine and nearby Teren-Sai project concentrate value in a single, producing asset base. Earnings growth of about 35.8% a year over five years, a 41.3% ROE and a 6.3x P/E versus peers at roughly 12x all point to a stock where future cash generation has a greater influence than one unresolved pressure on how long those cash flows can run at current quality.
That single asset focus makes the risk reward balance very specific, so check the analysis report for AltynGold to see what might extend or cap AltynGold’s cash engine.
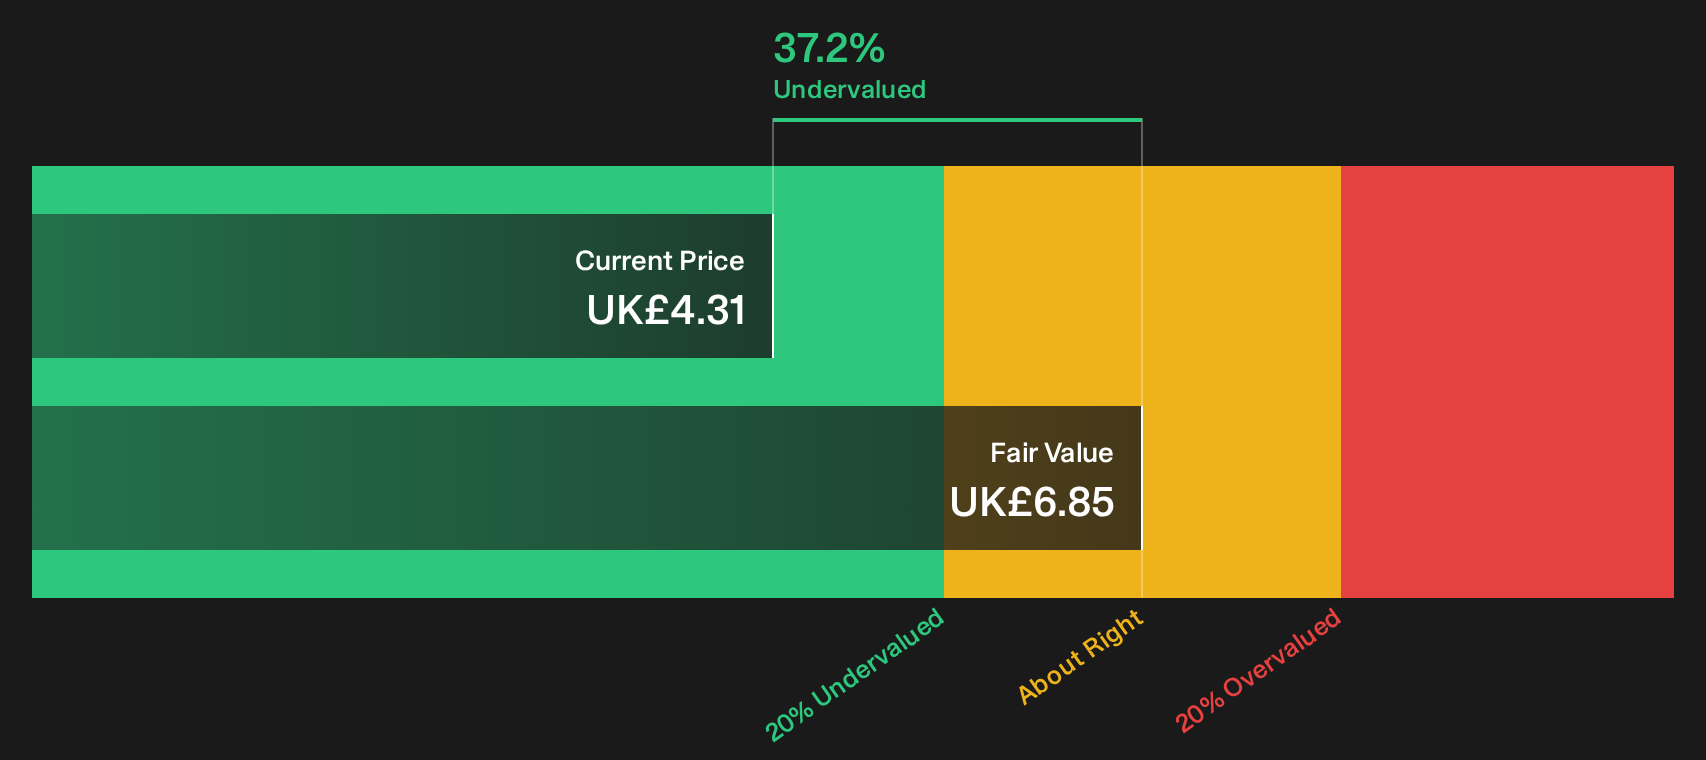
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is an investment manager that runs renewable infrastructure funds alongside private equity and venture strategies, with contracted clean-energy assets providing the clearest link to long-term cash flows.
Operations: Foresight Group Holdings generates about £114.8 million from Real Assets and £50.1 million from Private Equity, mainly across the UK and Australia.
Market Cap: £476 million
Foresight Group Holdings matters for this cash flow screen because its renewable infrastructure arm turns long-term energy contracts into fee streams that plug neatly into discounted cash flow models, giving you clearer visibility on future cash generation than many other asset managers.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) could deliver compounding EPS growth and potentially higher dividend per share increases if capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
The real tension for Foresight Group Holdings is how far those steady infrastructure fees can pull overall profitability if a single key assumption breaks.
If that assumption is starting to wobble, read the full narrative for Foresight Group Holdings to see how Foresight Group Holdings could turn its infrastructure fee engine into accelerating long term value.
Seeking Alternatives Before The Crowd
Fresh ideas tend to move first. By the time momentum headlines hit, many breakouts are already advancing. Use these curated lists while it matters and consider them early in your research process.
- Look for under-the-radar yield opportunities and scan the 1 dividend fortresses before prices adjust and income-focused investors begin concentrating on the same high payout opportunities.
- Monitor the next wave of automation leaders and review the 93 robotics and automation stocks while these potential compounders are still priced for hesitation rather than for perfection.
- Evaluate opportunities ahead of potential shifts in the energy grid and sift through the 40 power grid technology and infrastructure stocks while infrastructure spending themes are still being gradually reflected in these assets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com