


How Record Q2 Results At Urban Outfitters Stock Have Changed Its Investment Story
- Urban Outfitters reported record second quarter fiscal 2027 sales and profits, with earnings in line with expectations and revenue above consensus across Retail, Wholesale, and Subscription segments.
- Nuuly, Urban Outfitters’ apparel rental platform, has grown to over half a million active subscribers and is preparing a major East Coast facility that will triple operational square footage. This highlights the group’s push into higher complexity, technology heavy subscription logistics.
- We will now look at how Urban Outfitters’ investment narrative could be shaped by record Q2 results and management’s upbeat margin outlook.
Urban Outfitters Investment Narrative Recap
To own Urban Outfitters, you need to believe the group can keep translating its lifestyle brands and Nuuly subscription base into steady sales while holding on to recent profitability gains. Record Q2 results support that view in the near term. The key short term catalyst now sits in how well upcoming quarters convert recent momentum into consistent gross and operating margin performance.
The biggest operational risk remains cost pressure from tariffs and heavier spending on marketing and new stores, especially if demand softens. Nuuly’s complexity adds another layer of execution risk. Management’s upbeat tone on margins after Q2 helps the story, but it does not remove these headwinds.
The upcoming presentation at the Goldman Sachs Global Consumer and Retail Conference on 15 September 2026 looks especially relevant after record Q2 numbers. Investors will be listening closely for detail on how Urban Outfitters plans to balance higher marketing and expansion costs with its focus on profitability, and how Nuuly’s scale up fits into that plan.
Any extra color on tariff management, inventory discipline, and the ramp up of the new East Coast Nuuly facility could shape how you think about both the near term margin catalyst and the main downside risks. Clear, consistent commentary around these operational levers would help you judge whether current earnings quality feels repeatable.
Urban Outfitters' current earnings sit at US$569.1 million, and the analyst consensus points to earnings of US$581.0 million by 2029 alongside forecast revenue of US$7.9b. That profile reflects an assumed 7.0% yearly revenue growth rate and an earnings increase of about US$11.9 million from earnings today.
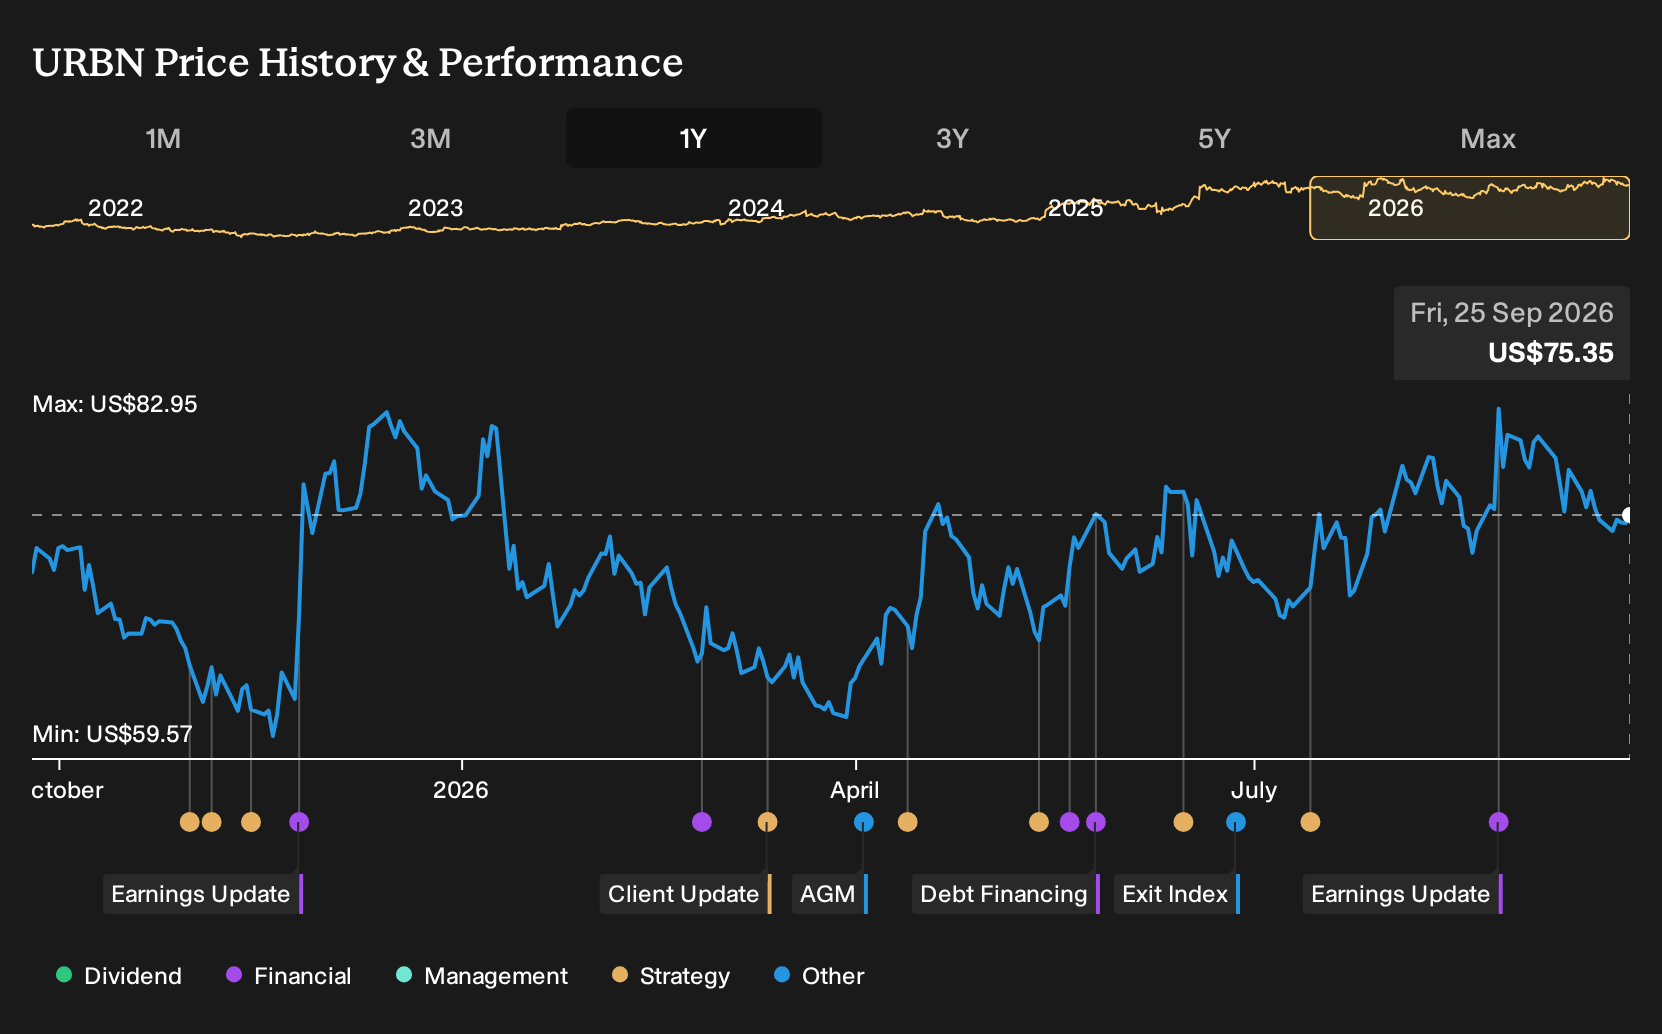
Uncover why Urban Outfitters' fair value indicates a 19% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts Nuuly at the center of the Urban Outfitters story. The most optimistic analysts were already penciling in US$8.0b of revenue and US$662.4 million of earnings by 2029, compared with the lower end near US$569.2 million. These forecasts came before the conference and Q2 news, so you may see opinions shift.
Explore 2 other Urban Outfitters fair value estimates, including one that suggests as much as 19% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Urban Outfitters research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Urban Outfitters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Urban Outfitters' overall financial health at a glance.
Looking for more Urban Outfitters style ideas?
If the Urban Outfitters story has you thinking about what else might fit your watchlist, it can help to scan a wider field of potential opportunities with similar or complementary characteristics.
- If capital preservation is a priority, review 30 resilient stocks with low risk scores to find steadier risk profiles paired with more resilient fundamentals.
- For investors who care most about financial strength, start with a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with stronger footing.
- Those hunting for mispriced opportunities can cast a wider net using a 31 high quality undervalued stocks to spot situations where quality and current pricing appear out of sync.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com