


There's A Lot To Like About Press Kogyo's (TSE:7246) Upcoming JP¥25.00 Dividend
Readers hoping to buy Press Kogyo Co., Ltd. (TSE:7246) for its dividend will need to make their move shortly, as the stock is about to trade ex-dividend. The ex-dividend date is usually set to be two business days before the record date, which is the cut-off date on which you must be present on the company's books as a shareholder in order to receive the dividend. The ex-dividend date is important because any transaction on a stock needs to have been settled before the record date in order to be eligible for a dividend. Meaning, you will need to purchase Press Kogyo's shares before the 29th of September to receive the dividend, which will be paid on the 2nd of December.
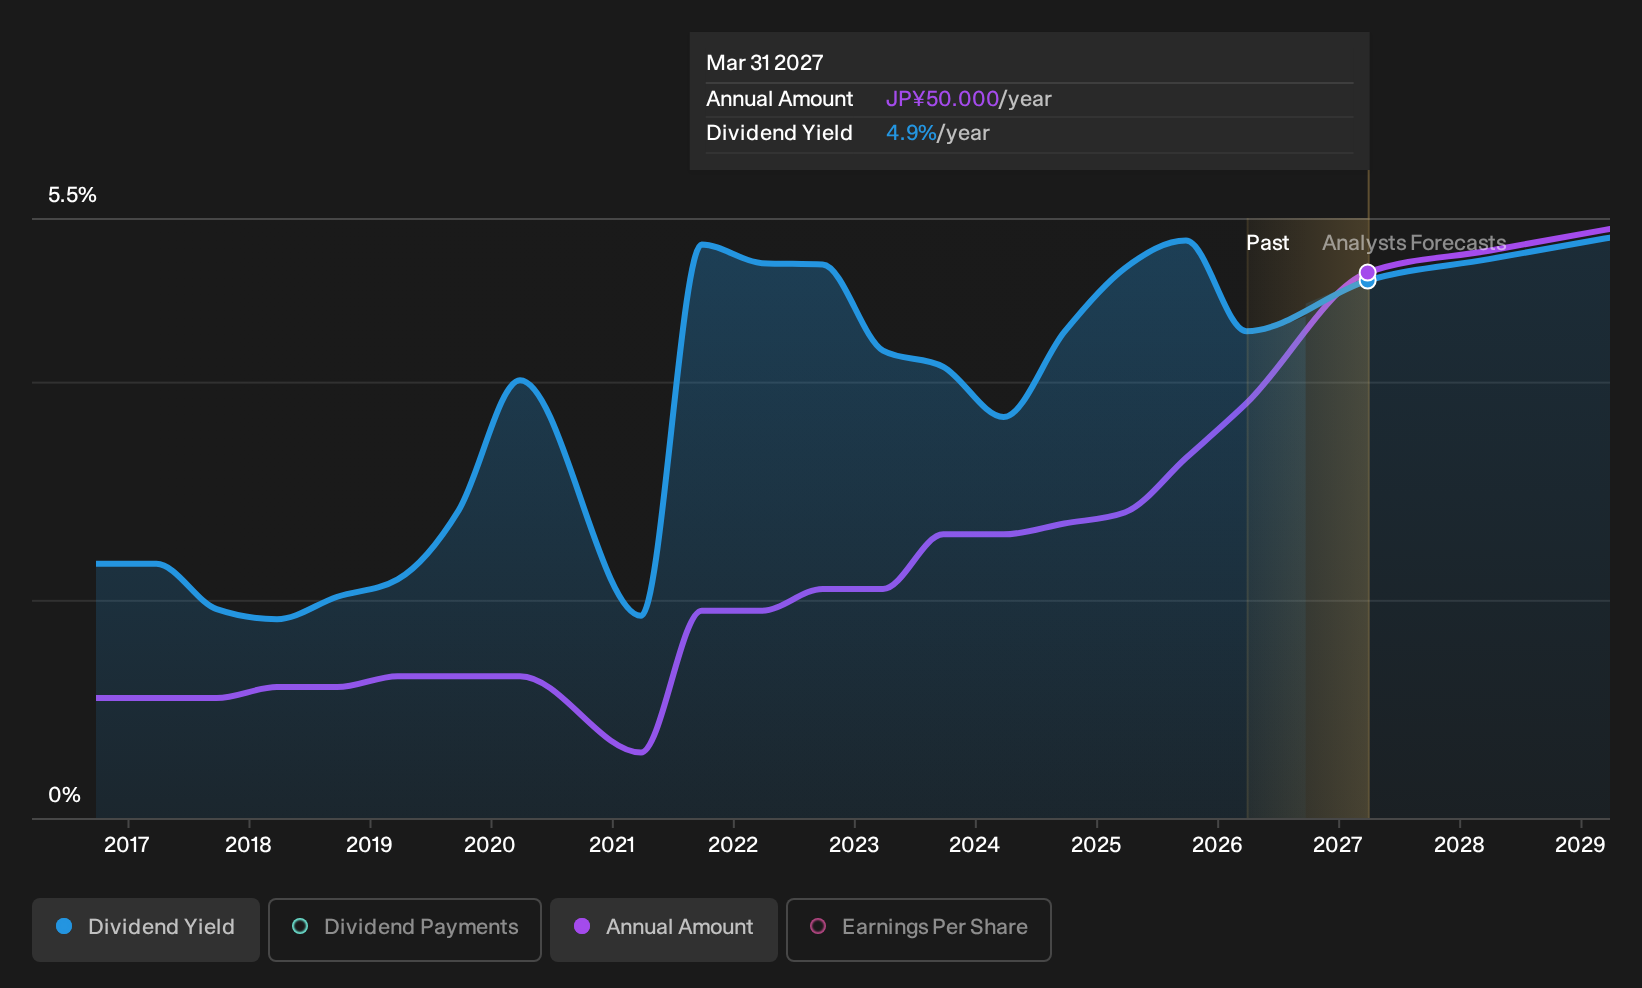
The company's next dividend payment will be JP¥25.00 per share, on the back of last year when the company paid a total of JP¥44.00 to shareholders. Calculating the last year's worth of payments shows that Press Kogyo has a trailing yield of 4.9% on the current share price of JP¥1015.00. We love seeing companies pay a dividend, but it's also important to be sure that laying the golden eggs isn't going to kill our golden goose! We need to see whether the dividend is covered by earnings and if it's growing.
Dividends are usually paid out of company profits, so if a company pays out more than it earned then its dividend is usually at greater risk of being cut. That's why it's good to see Press Kogyo paying out a modest 38% of its earnings. A useful secondary check can be to evaluate whether Press Kogyo generated enough free cash flow to afford its dividend. Over the last year, it paid out more than three-quarters (76%) of its free cash flow generated, which is fairly high and may be starting to limit reinvestment in the business.
It's encouraging to see that the dividend is covered by both profit and cash flow. This generally suggests the dividend is sustainable, as long as earnings don't drop precipitously.
See our latest analysis for Press Kogyo
Click here to see how much of its profit Press Kogyo paid out over the last 12 months.
Have Earnings And Dividends Been Growing?
Companies with consistently growing earnings per share generally make the best dividend stocks, as they usually find it easier to grow dividends per share. If earnings decline and the company is forced to cut its dividend, investors could watch the value of their investment go up in smoke. That's why it's comforting to see Press Kogyo's earnings have been skyrocketing, up 48% per annum for the past five years.
The main way most investors will assess a company's dividend prospects is by checking the historical rate of dividend growth. In the last 10 years, Press Kogyo has lifted its dividend by approximately 16% a year on average. Both per-share earnings and dividends have both been growing rapidly in recent times, which is great to see.
To Sum It Up
Has Press Kogyo got what it takes to maintain its dividend payments? From a dividend perspective, we're encouraged to see that earnings per share have been growing, the company is paying out less than half of its earnings, and a bit over half its free cash flow. There's a lot to like about Press Kogyo, and we would prioritise taking a closer look at it.
With that in mind, a critical part of thorough stock research is being aware of any risks that stock currently faces. Our analysis shows 1 warning sign for Press Kogyo and you should be aware of it before buying any shares.
Generally, we wouldn't recommend just buying the first dividend stock you see. Here's a curated list of interesting stocks that are strong dividend payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.