


NBT Bancorp (NBTB) Could Be 9% Undervalued After Kimberly Boynton Board Appointment
Why Kimberly Boynton’s Board Appointment Matters For NBT Bancorp
NBT Bancorp (NBTB) has drawn fresh attention after naming Kimberly A. Boynton to the boards of both the holding company and NBT Bank, N.A., effective October 1, 2026.
Her background blends healthcare leadership, financial management, and commercial real estate experience in upstate New York, which could influence how the bank thinks about risk, community engagement, and growth priorities in its core markets.
Recent trading has been steady rather than dramatic, with a 90 day share price return of 3.99% and a year to date share price gain of 24.00%. NBT Bancorp’s 1 year total shareholder return of 25.36% and 3 year total shareholder return of 79.48% point to momentum that has built over time rather than faded.
See how NBT Bancorp compares with other regionally focused financial institutions by checking a curated group of list of solid balance sheet and fundamentals (24 results)
After a strong run in NBT Bancorp over the past year, the real tension now sits in the valuation. Is the meaningful discount to estimated intrinsic value pointing to further upside, or has most of the easy gain already played out?
Most Popular Narrative: 9% Undervalued
At a last close of $51.57 versus a widely followed fair value estimate of $56.83, the prevailing view is that NBT Bancorp trades at a meaningful discount, with that gap hinging on how much investors credit its expansion and fee income plans.
Enhanced focus on expanding wealth management and insurance services, especially with access to Evans' customer base, supports a growing share of non-interest, fee-based revenues and leads to a more resilient earnings profile. Strong capital and liquidity positions following the Evans merger improve NBT's capacity to pursue additional acquisitions or organic expansion and set the stage for long-term earnings and tangible book value per share growth.
See why 15 investors see NBT Bancorp as 9% undervalued.
Result: Fair Value of $56.83 (UNDERVALUED)
Still, the bullish case for NBT Bancorp can unravel quickly if commercial credit quality weakens or non interest expenses continue to rise faster than fee income.
Find out about the key risks to this NBT Bancorp narrative.
Another View On NBT Bancorp’s Valuation
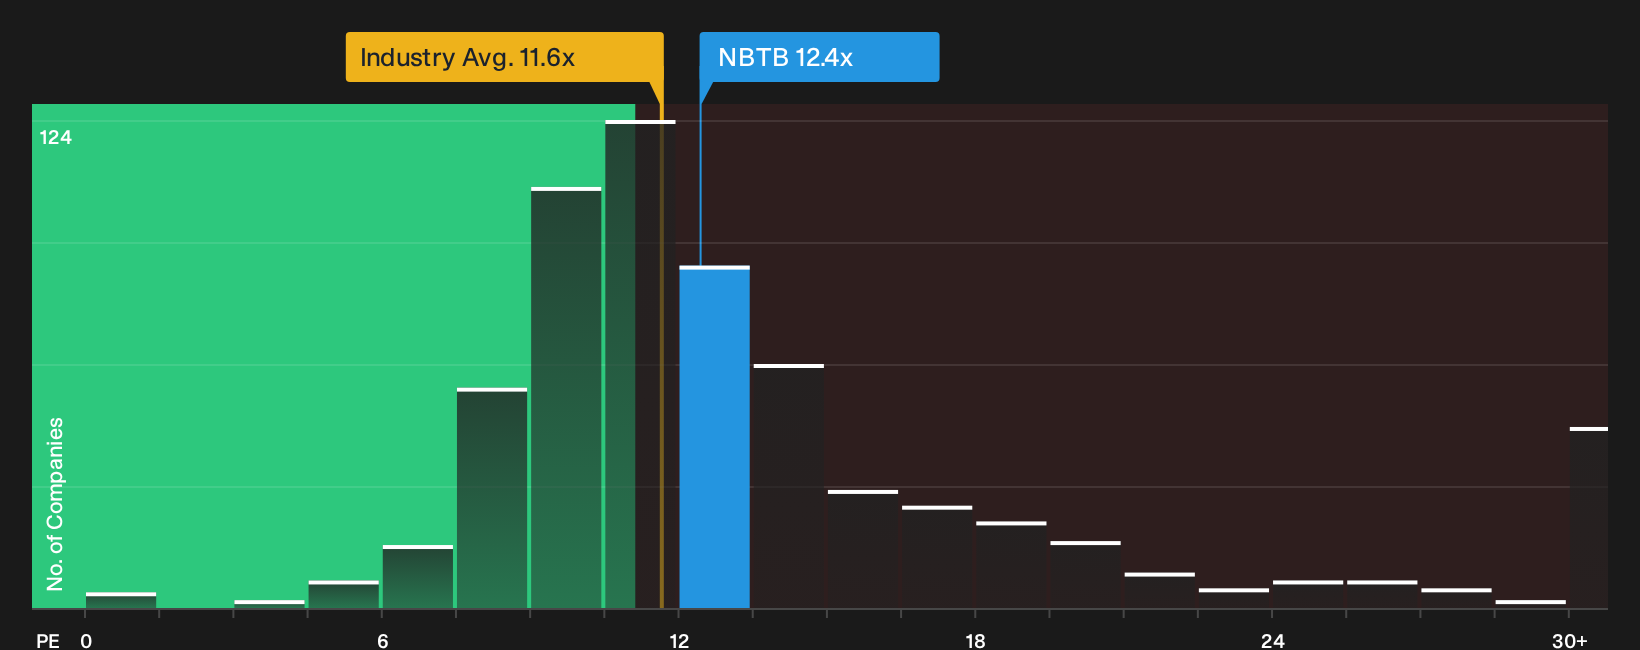
The first lens on NBT Bancorp focused on a fair value estimate of $56.83 and a headline discount. A different angle uses the current P/E of 12.4x versus a fair ratio of 12x and a US Banks industry average of 11.5x. That gap suggests investors are already paying a small premium. Is that comfort with the story, or a margin of safety that is thinner than it looks?
To unpack how that premium could adjust over time, and what it might mean for valuation risk if sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on NBT Bancorp after all this, or leaning one way? Act while the information is fresh and weigh both sides by checking the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond NBT Bancorp?
If NBT Bancorp has sharpened your focus on quality and valuation, do not stop here. Broaden your watchlist now before the next opportunity races away.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Spot potential value opportunities early by reviewing a focused 31 high quality undervalued stocks list that compares quality metrics against current pricing.
- Prioritise stability and income together by reviewing a hand picked set of 29 resilient stocks with low risk scores built around lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com