


Same Day Delivery Deal Might Change The Case For Investing In Dollar General (DG)
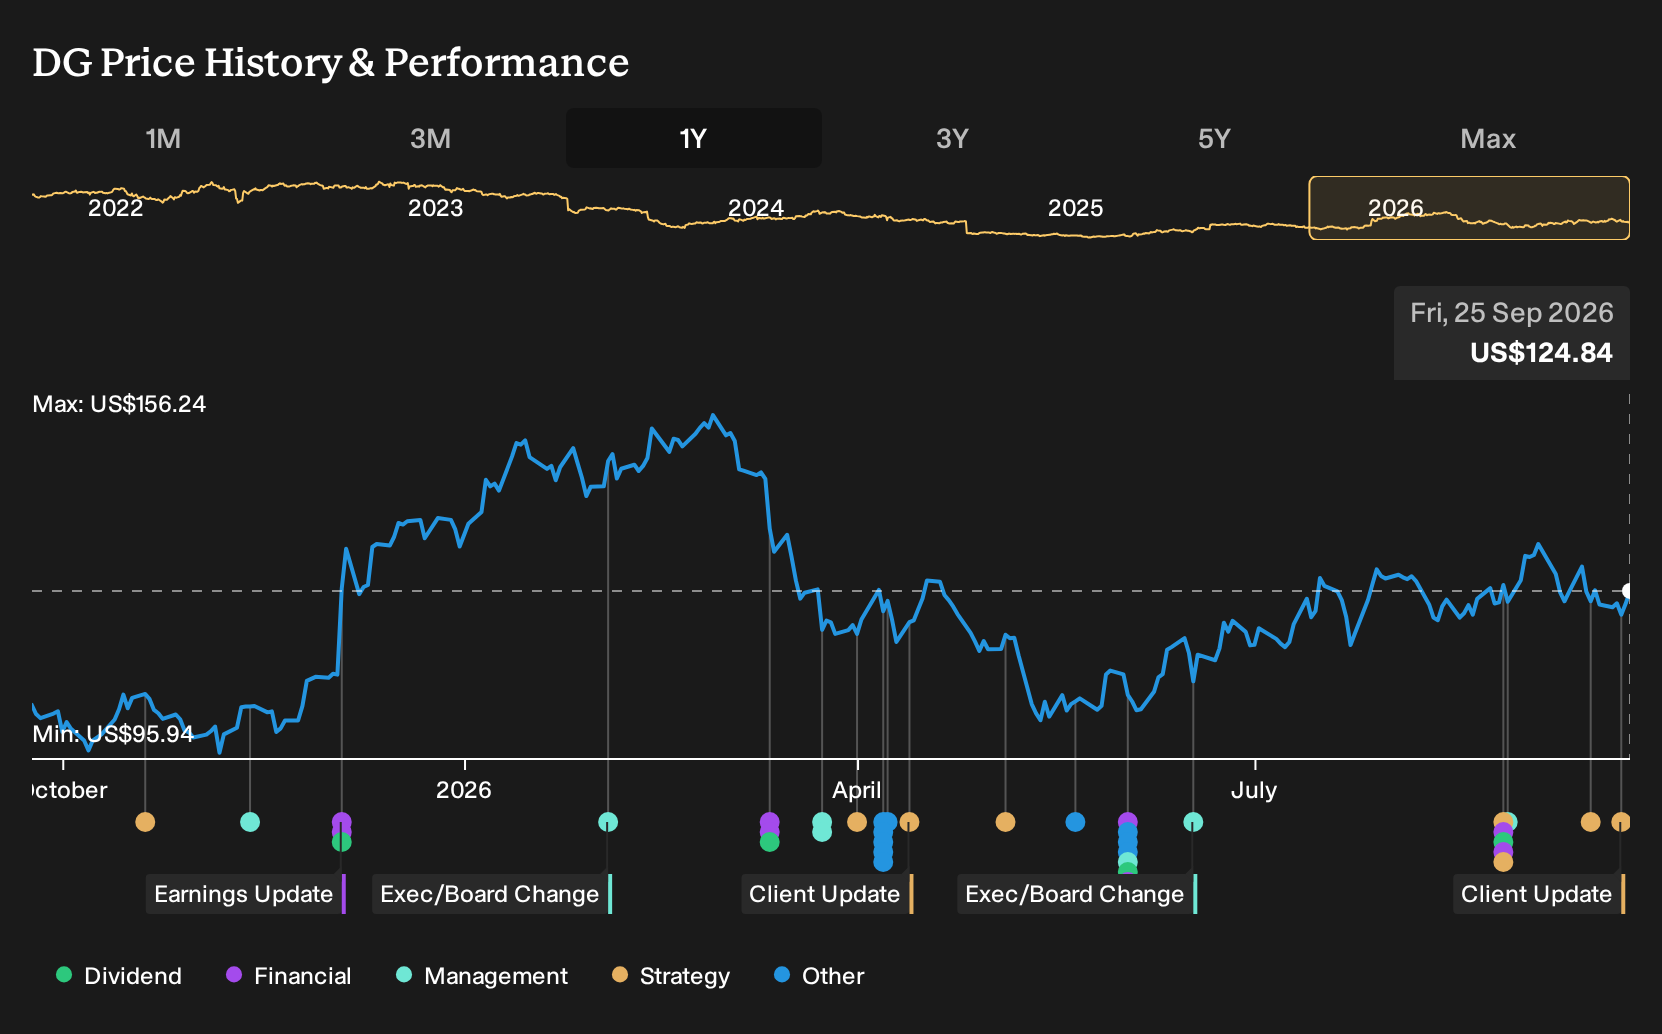
- Maplebear Inc., parent of Instacart, and Dollar General announced a partnership to offer same-day delivery of Dollar General and pOpshelf essentials from an initial pilot of about 7,000 stores in six states. The companies plan to extend coverage to roughly 20,000 locations across 48 states with delivery in as fast as one hour.
- The Instacart collaboration gives Dollar General a broad digital shelf almost overnight, expanding access to its value-focused assortment without new store builds. This development could influence how the retailer balances in-store investments, labor needs, and omni-channel execution costs.
- Now the focus shifts to how Dollar General's Instacart-fueled delivery push might reshape its investment narrative around digital scale and profitability.
Dollar General Investment Narrative Recap
To own Dollar General, you need to believe its dense store base and value focus can keep pulling in budget conscious shoppers while management keeps costs, labor and shrink in check. The Instacart deal speaks directly to the biggest near term catalyst, proving Dollar General can scale digital reach without building a heavy in house e commerce stack.
The flip side is execution risk. Rapid expansion, remodels and wage pressure already strain operations. Layering same day delivery could complicate staffing and inventory if stores are not ready. If service quality slips or costs rise faster than sales, the Instacart push may matter more for risk than for near term upside.
The Instacart partnership looks most relevant for the current story around Dollar General because it plugs directly into the digital and delivery catalyst analysts have been watching. Same day access across up to 20,000 locations links its low price positioning with convenience that used to be a weak spot.
This move also intersects with longer term threats. Rural exposure, competition from Walmart and Aldi, and slower omni channel progress have all been flagged as issues. Execution on Instacart gives Dollar General a way to test online demand, pressure test store level processes and refine how much capital really needs to go into its own delivery infrastructure.
What The Dollar General Forecasts Actually Assume
Dollar General's narrative projects US$48.8b revenue and US$1.9b earnings by 2029. That profile rests on 4.3% yearly revenue growth and about US$300m earnings increase from US$1.6b today.
Uncover how Dollar General's fair value indicates a 5% potential upside to its current price before that discount closes for Dollar General investors.
Exploring Other Perspectives
Some of the most optimistic analysts already expected Dollar General to reach about US$51.9b in revenue and US$2.1b in earnings by 2029 on faster digital traction. You now have an Instacart deal that those forecasts did not yet factor in. That cohort sees delivery and pOpshelf as upside levers. More cautious voices stick closer to the US$48.8b and US$1.9b consensus path. Treat this spread as a reminder that you are weighing very different stories, and it can be worth exploring both before deciding which version sounds more realistic to you.
Explore 6 other Dollar General fair value estimates, including one that suggests as much as 41% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own view carefully.
- A great starting point for your Dollar General research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Dollar General. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dollar General's overall financial health at a glance.
Looking for more Dollar General style investment ideas?
If Dollar General's blend of value pricing and convenience appeals to you, it can be useful to widen the lens and see which other businesses share similar financial traits or risk profiles. The Simply Wall St Screener lets you sift through the market using the same data driven filters that underpin this analysis, so you can build a watchlist that fits your own return and risk preferences.
- For investors who care most about strong fundamentals with room to rerate, start with a curated set of 31 high quality undervalued stocks that combine quality metrics with pricing that screens below intrinsic value estimates.
- If capital preservation and a steadier ride matter more than chasing every rally, consider reviewing a 30 resilient stocks with low risk scores that filters for companies with healthier balance sheets and fewer red flags in their risk profile.
- Readers who want solid financial footing without spending hours combing through filings can use a focused list of solid balance sheet and fundamentals (24 results) that surfaces businesses with cleaner leverage, liquidity and asset coverage ratios.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com