


Will Earnings Growth Forecasts Change Vita Coco Stock Narrative
- Vita Coco Company recently attracted attention after analysts issued projections that its upcoming quarterly earnings per share could rise 27.5% alongside a 28.2% year over year revenue increase, with full year estimates also pointing to higher earnings and sales.
- The projections suggest analysts see Vita Coco Company benefiting from demand for coconut based beverages and related products, which could interact with existing cost pressures from tariffs, freight, and SG&A spending in important ways for profitability.
- We will now look at how Vita Coco Company's investment narrative could be affected by these upbeat earnings and revenue projections.
Vita Coco Company Investment Narrative Recap
For Vita Coco Company to make sense in your portfolio, you need to believe the brand can keep turning consumer interest in coconut based drinks into consistent earnings while managing input costs. The upbeat projections for earnings and revenue sharpen the focus on near term execution on pricing, mix, and supply chain efficiency as the key short term catalyst.
The biggest immediate risk still sits with costs rather than demand. Higher tariffs on coconut imports, elevated freight, and rising SG&A can quickly eat into profit margins if they flare up again or if private label softness persists. The latest forecasts do not remove that risk. They mostly frame how much cushion Vita Coco Company may have if cost pressure returns.
The most relevant recent development is the set of analyst expectations pointing to higher earnings per share and revenue for Vita Coco Company in the coming quarter and over the full year. These projections sit on top of already strong reported metrics, including US$706.0m in revenue and US$109.5m in net income, with net margins of 15.5%.
For you, the question is how those estimates intersect with the existing catalysts and threats. A business leaning into coconut water penetration, product adjacencies, and international markets may benefit if demand tracks those projections, especially with a P/E of 31.7x and a return on equity of 27.3%. The same forecasts also raise the bar on execution if tariffs, freight costs, or SG&A begin to squeeze margins again.
Vita Coco Company's narrative projects US$1.1b in revenue and US$158.2m in earnings by 2029. This aligns with analyst assumptions of 15.6% yearly revenue growth and an earnings increase of about US$48.7m from US$109.5m today.
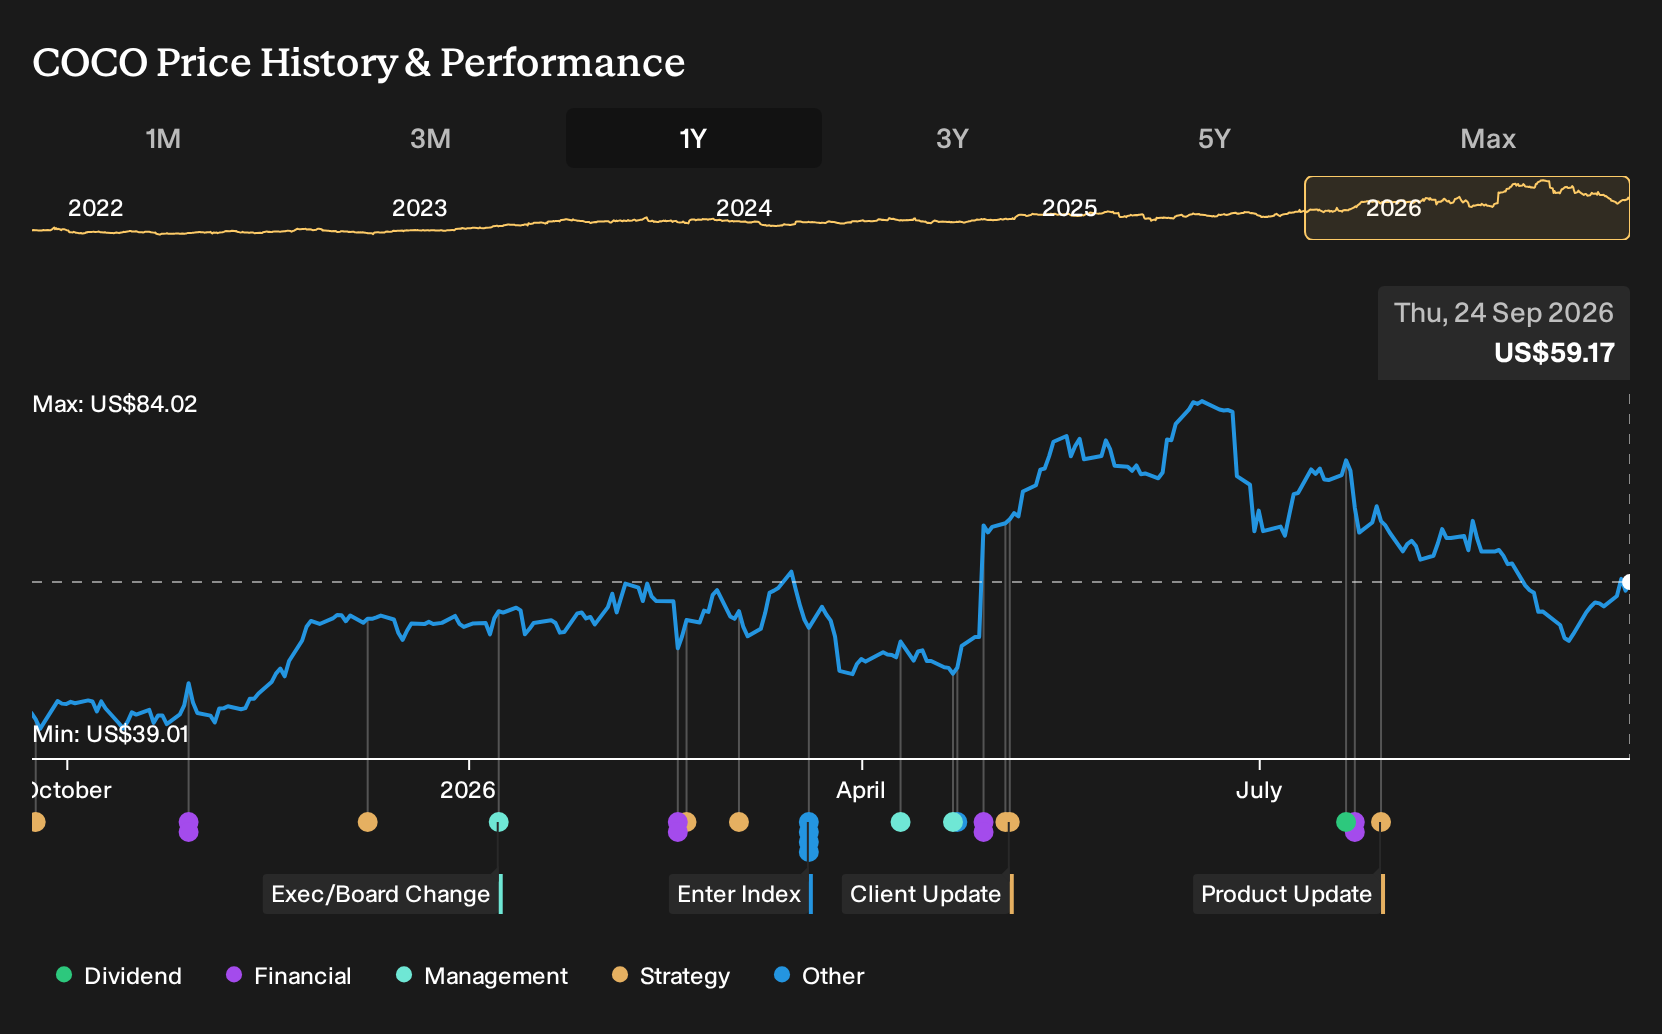
Uncover how Vita Coco Company's fair value indicates a 43% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between 83.56 and 83.96, so retail opinions currently point to a very narrow pricing band for Vita Coco Company. You still have to weigh that against unresolved tariff and freight risks, which could shift earnings power and make these community views look stale quickly.
Explore another Vita Coco Company fair value estimate, including one that suggests it could be worth just $83.56.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vita Coco Company research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Vita Coco Company. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate Vita Coco Company's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vita Coco Company?
If the Vita Coco Company story has sharpened your thinking about earnings quality and pricing power, it can help to compare it with other businesses screened on clear fundamentals. That way you test your thesis against a wider set of opportunities instead of focusing on a single ticker.
- If you want potential growth with tight cash controls, review a curated set of smaller companies in the 8 elite penny stocks with strong financials that already show stronger financials than many peers.
- For investors who care most about getting solid value for every dollar invested, weigh opportunities in the 32 high quality undervalued stocks that pair quality fundamentals with pricing that still looks reasonable.
- If capital protection matters more than big swings, narrow your watchlist to businesses in the 30 resilient stocks with low risk scores that score well on resilience and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com