


Is Idorsia (SWX:IDIA) Too Expensive For Its Sales Base?
Idorsia has given investors a bumpy ride over the past few years, and the current share price puts a spotlight on one basic question: Are you paying a sensible amount today for the company’s ability to generate sales?
- Over the last 5 years, the share price has fallen 79.8%, which puts current valuation arguments squarely on whether the remaining business can support today’s market value through its revenue base.
- The group’s future hinges on how effectively it can translate its drug portfolio and pipeline into stable product sales, since that will influence both funding needs and how much value investors can reasonably tie to its top line.
- There is a second opinion on Idorsia worth weighing. See what analysts think Idorsia's shares could be worth.
The issue now is whether Idorsia’s current market price is well supported by its sales when judged against the Fair Ratio benchmark.
If you want a second reference point alongside Idorsia’s valuation on its sales, a focused screen of other companies trading on 180 high quality undervalued stocks can broaden your research list.
Is Idorsia Getting Expensive on Sales?
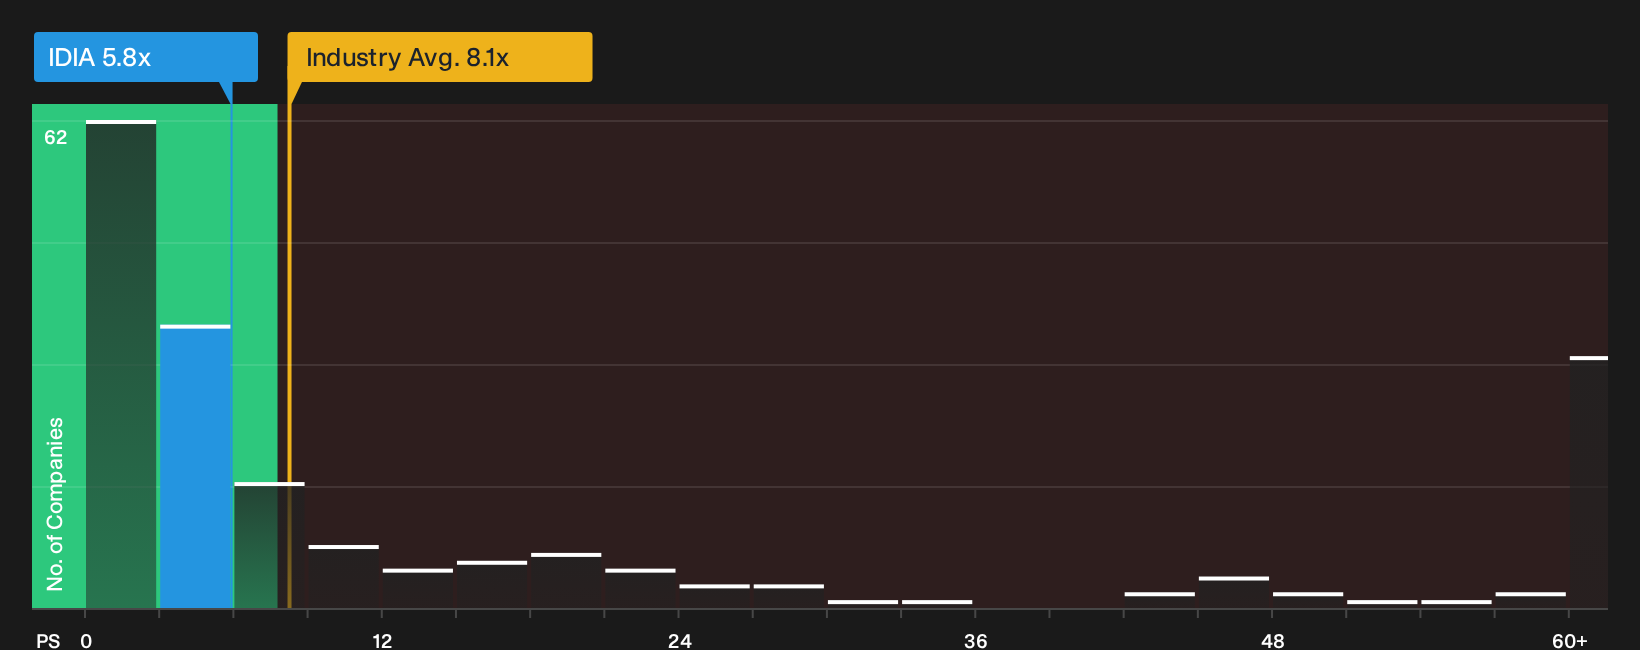
The P/S ratio suits Idorsia because investors are mostly weighing its potential to convert its drug portfolio into revenue rather than near term profits. On this basis, the stock trades on about 5.8x P/S, which is below the broader biotech industry average of roughly 10.4x and also below the closer peer group on about 8.1x.
The Fair Ratio, which adjusts the P/S multiple for Idorsia’s own growth profile, margins, size and risk, sits below the current level. That leaves the shares screening as overvalued on this framework, even though the raw P/S still appears lower than sector benchmarks. For anyone considering Idorsia today, the key question is whether its product pipeline can justify paying a premium to that tailored fair multiple over time. Explore the numbers behind Idorsia's P/S valuation.
The Idorsia Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Idorsia’s valuation puzzle leaves off. They spell out what sort of growth, margins and earnings profile would need to unfold for the stock to be worth materially more or materially less than today’s price on the Community page. Each scenario ties a fair value to a clear story about Idorsia’s potential catalysts and key risks so you can track which version of events is taking shape over time.
One of the top community narratives on Idorsia: 26% undervalued
"A capital light, partnership centric model that out licenses late stage assets to global players enables Idorsia to participate in large markets..."
Discover why this Narrative puts Idorsia at 26% undervalued.
The Idorsia share price is only one piece of the decision
Valuation metrics tell you what the market is willing to pay today, but analyst models sketch out where they think Idorsia could be a few years from now and give you a different yardstick to compare with the current tag. Explore where analysts expect Idorsia to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com