


Is Philip Morris International (PM) Undervalued As Its Dividend Rises And Smoke Free Rules Ease?
Philip Morris International (PM) is back in focus after its board approved an 8.8% lift in the regular quarterly dividend to an annualized US$6.40 per share, resetting the income backdrop for shareholders.
Philip Morris International shares trade at US$191.50 after a year of steady momentum, with a 19.46% year to date share price return and a 1-year total shareholder return of 21.00%, supported by dividend growth and a friendlier outlook for smoke free regulation.
Capture this moment in Philip Morris International, and then scan a curated set of income focused stocks with resilient cash flows using the 8 dividend fortresses.After a strong run on the back of richer income and a friendlier policy backdrop for smoke free products, the question now is whether Philip Morris International still offers meaningful upside or if the easy gains are already in the rear view mirror.
Most Popular Narrative: 6% Undervalued
Analysts following Philip Morris International anchor their view around a fair value of $203.80 per share, which sits modestly above the latest close at $191.50, and frame the current setup as a balance between smoke free momentum and execution risk.
The accelerating global adoption of smoke-free alternatives, driven by increasing health awareness and regulatory moves away from combustibles, is fueling strong double-digit volume and margin growth in PMI's IQOS, ZYN, and VEEV platforms. This secular shift enables the company to capture new consumer segments, expand its addressable market, and structurally boost net revenues and operating margins over time.
See why 94 investors see Philip Morris International as 6% undervalued.
Result: Fair Value of $203.80 (UNDERVALUED)
Still, the narrative around Philip Morris International could be knocked off course if cigarette volumes weaken faster than expected or if new regulations hit smoke free products harder than analysts model.
Find out about the key risks to this Philip Morris International narrative.
Another View On Philip Morris International Valuation
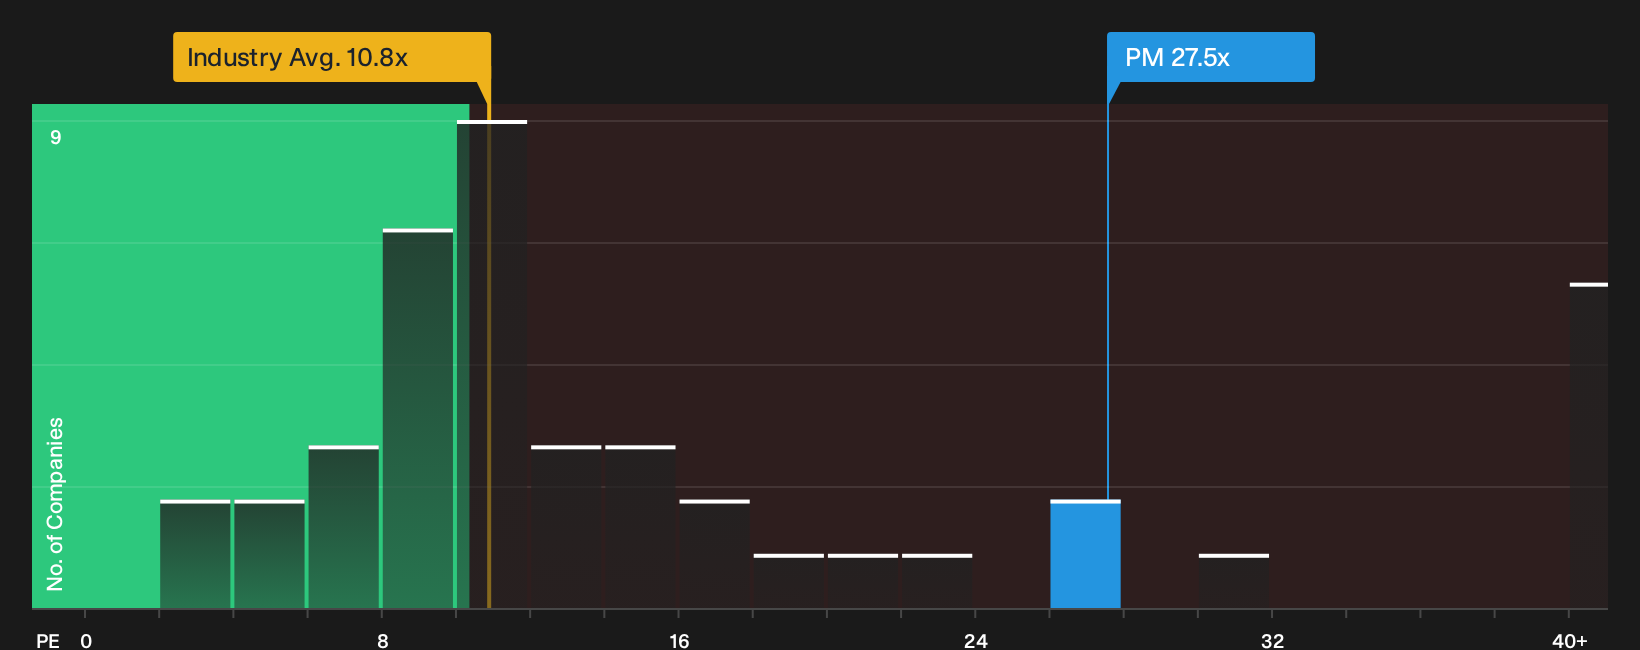
Analysts frame Philip Morris International as modestly undervalued on their fair value of $203.80, yet the current P/E of 27.5x tells a different story. That multiple sits above peers at 21.2x and even edges past a 27.3x fair ratio, which hints at less margin for error if sentiment cools.
For a closer look at what that premium means in practice, and how much of Philip Morris International's reduced risk story might already be in the price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Philip Morris International valuation and risk can pull investors in opposite directions, so act promptly, review the data yourself, and weigh the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Philip Morris International?
If Philip Morris International has caught your attention, do not stop here. Broaden your watchlist and test your income, value, and risk assumptions with fresh candidates.
- Target reliable income streams by scanning a curated universe of high-yield payers through the 8 dividend fortresses.
- Hunt for quality at a sensible price by filtering for companies that screen as 30 high quality undervalued stocks.
- Protect your downside by focusing on financial resilience using our 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com