


How Investors May Respond To O Reilly Automotive Stock Strong Same Store Sales
- Recent coverage of O'Reilly Automotive has highlighted strong same store sales performance, an efficient operating model, and profitability metrics that compare favorably with peers.
- The focus on operating margin quality and returns on capital has drawn attention to how O'Reilly Automotive converts day to day execution into long term value creation.
- We will now look at how O'Reilly Automotive's investment narrative is affected by the focus on same store sales momentum and efficiency.
Scan for more companies turning strong same store sales and efficient operations into profitability by reviewing the hand picked 16 high quality undiscovered gems that share traits with O'Reilly Automotive.
O'Reilly Automotive Investment Narrative Recap
To own O'Reilly Automotive, you need to be comfortable with a story built around disciplined same store sales, tight cost control, and heavy investment in distribution and inventory. The recent focus on its strong same store performance reinforces that picture rather than changing it. For now, the key short term swing factor is whether professional do it for me growth and new stores keep supporting those comps.
The biggest risk still sits on the cost and capital side. Tariff decisions, supplier pricing, and the planned move toward 2.5x leverage all interact with an already debt heavy balance sheet and negative equity. The latest news on profitability does not remove those pressures; it just makes execution quality more visible.
Among recent developments, the most operationally relevant piece is management leaning into inventory and distribution. Inventory per store is around US$892,000, with a 5% growth target per location aimed at keeping shelves full enough to support comparable sales. That directly ties to the same store momentum highlighted in the latest coverage of O'Reilly Automotive.
The same update cycle also flagged sizeable 2026 capital expenditure of US$1.3b to US$1.4b, including spend on the new Atlanta distribution center. For investors, this sits at the center of the catalyst and risk mix. Efficient deployment can help margins and product availability, while weaker cash generation against this higher spend and leverage target could tighten financial flexibility.
What The O'Reilly Automotive Forecasts Are Asking You To Believe
O'Reilly Automotive's forward looking story now hinges as much on the analyst spreadsheet as on the store aisle. Consensus models build in 6.1% yearly revenue growth over the next three years, assuming that the current operational playbook can keep scaling through more locations, a heavier professional do it for me mix, and added distribution muscle.
Those same forecasts anchor on earnings today of about US$2.7b and a shared view that profit can reach US$3.2b by 2029. That is an earnings increase of roughly US$500m from current levels, with analysts broadly aligned on that destination. The framework implies that O'Reilly Automotive could be generating US$22.2b of revenue and US$3.2b of net profit in 2029 if the revenue growth, margin tweaks, and capital plans all work in concert.
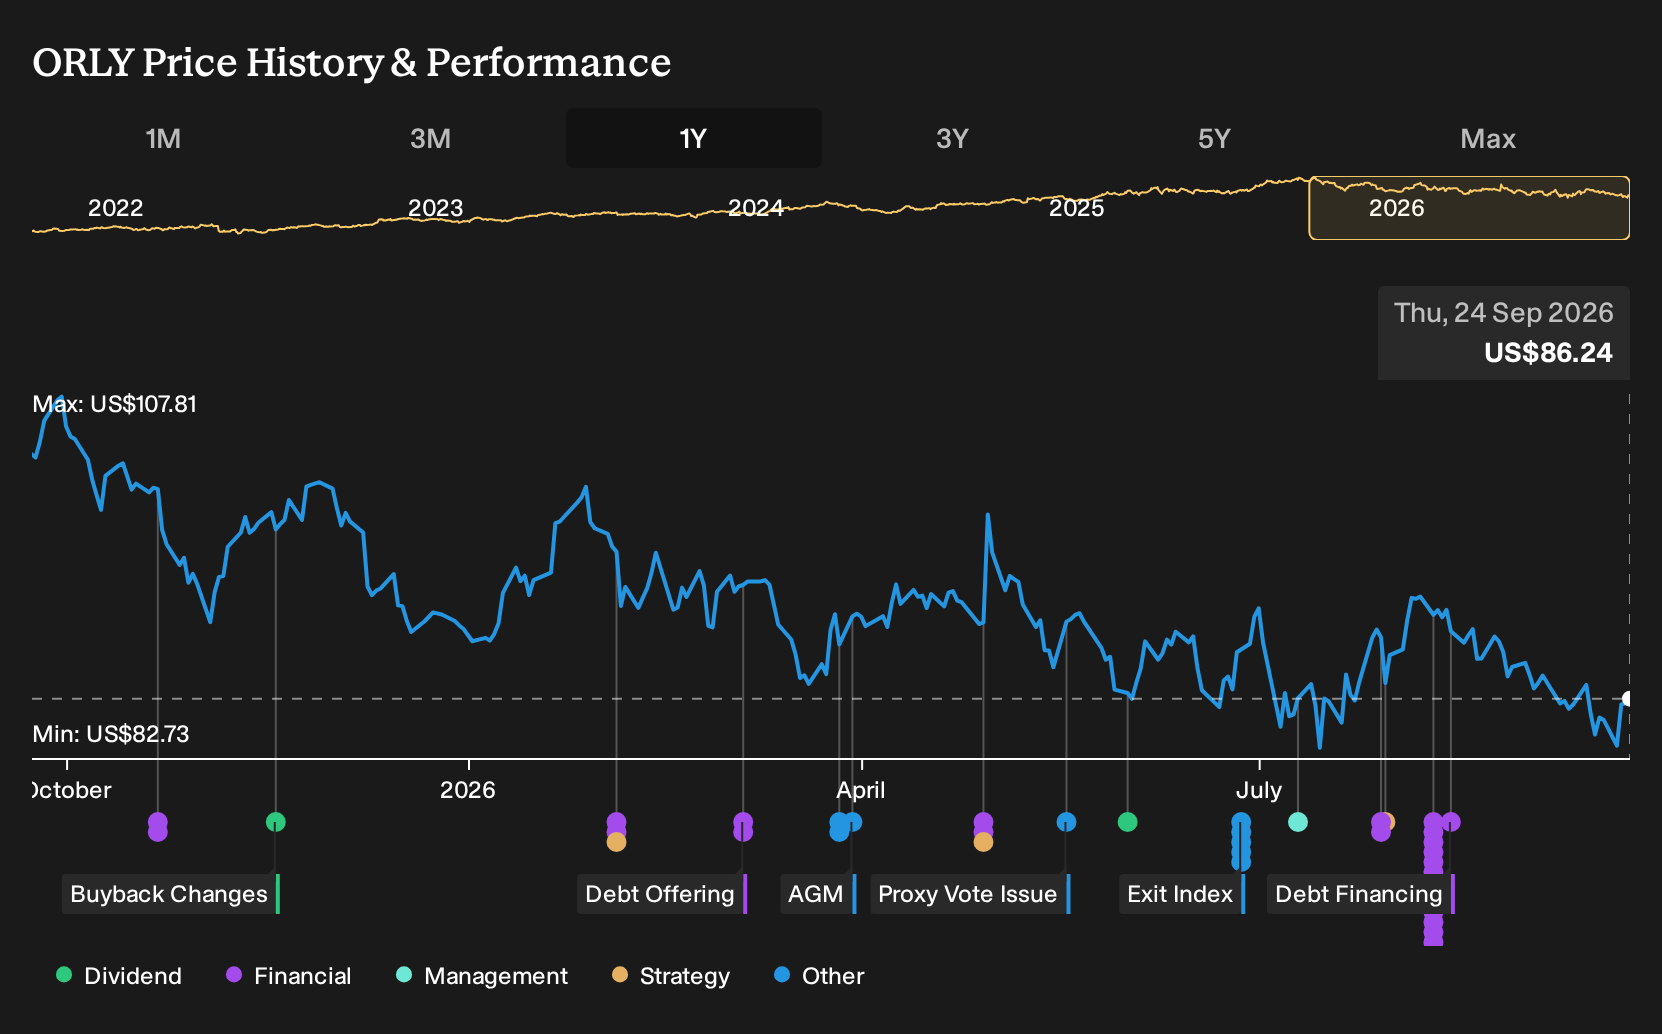
Valuation assumptions then layer on top of that operating picture. The consensus view uses those 2029 earnings to back into a P/E of 30.4x, compared with about 25.9x today and an industry figure of 15.9x for US specialty retailers. In practice, that means the current share price and the US$107.8 average target both rely on the idea that O'Reilly Automotive can earn more, at slightly higher margins, and still command a richer multiple than the sector.
O'Reilly Automotive's narrative projects US$22.2b revenue and US$3.2b earnings by 2029. This requires 6.1% yearly revenue growth and an earnings increase of about US$500m from US$2.7b today.
Uncover why O'Reilly Automotive's fair value indicates a 25% potential upside to its current price before investors fully account for that difference.
Exploring Other Perspectives
One alternate angle focuses on electric vehicles as the long term spoiler for O'Reilly Automotive. While the recent attention is on strong same store sales, the most optimistic analysts had been modelling faster momentum, with revenue reaching about US$23.0b and earnings of US$3.4b by 2029. Those projections were set before this news, so opinions may evolve as fresh data comes through. It can be useful to explore how your own view lines up with both the bullish and more cautious cases.
Explore 4 other O'Reilly Automotive fair value estimates, including one that suggests as much as 39% potential increase from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your O'Reilly Automotive research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for O'Reilly Automotive. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate O'Reilly Automotive's overall financial health at a glance.
Looking For More Ideas Beyond O'Reilly Automotive?
If you want to test your thesis on O'Reilly Automotive against other opportunities, the Simply Wall St Screener can help you quickly surface stocks with similar qualities, different risk profiles, or a completely fresh angle for your portfolio.
- If capital preservation sits high on your list, start with a basket of companies screened for resilience and lower risk using the 30 resilient stocks with low risk scores.
- If dependable fundamentals and clean balance sheets matter most to you, broaden your watchlist with the list of solid balance sheet and fundamentals (24 results).
- If you are hunting for quality that has not yet drawn broad attention, cast a wider net across the market using the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com