


Is Samsonite Group (SEHK:1910) Undervalued Or Is Its DTC Story Already Priced In?
Samsonite Group (SEHK:1910) recently completed a corporate rebranding, changing its legal name from Samsonite International S.A. to Samsonite Group S.A. This move refocuses attention on how this travel-goods business is valued today.
Recent trading tells a mixed story. Samsonite Group’s share price has slipped over the past quarter and is down 38% on a year to date basis. However, the 1 year total shareholder return decline of 22.7% is less severe, hinting that recent weakness extends a longer period of fading momentum rather than a sudden shift in sentiment.
Spot opportunities by comparing Samsonite Group’s recent share price pressure with a curated 179 high quality undervalued stocks, which may be pricing in very different expectations.Samsonite Group looks like a solid global travel gear business on paper, yet the share price has retreated sharply. Is this still a quality franchise available at a fair valuation today?
Most Popular Narrative: 37% Undervalued
Samsonite Group’s most followed valuation narrative points to a fair value of HK$19.74, compared with the last close of HK$12.40. This frames today’s selloff as potentially out of step with that longer term view, which is built on a 10.29% discount rate.
Channel mix shift toward higher-margin direct-to-consumer (DTC) and e-commerce sales is already boosting margins and improving earnings quality, and the continued move toward a 50% DTC sales contribution will further expand operating margins over the medium to long term.
See why 1 investors see Samsonite Group as 37% undervalued.
Result: Fair Value of HK$19.74 (UNDERVALUED)
Still, Samsonite Group’s reliance on wholesale partners and exposure to softer consumer sentiment in markets like North America and China could quickly challenge that optimistic valuation story.
Find out about the key risks to this Samsonite Group narrative.
Another View On Samsonite Group’s Valuation
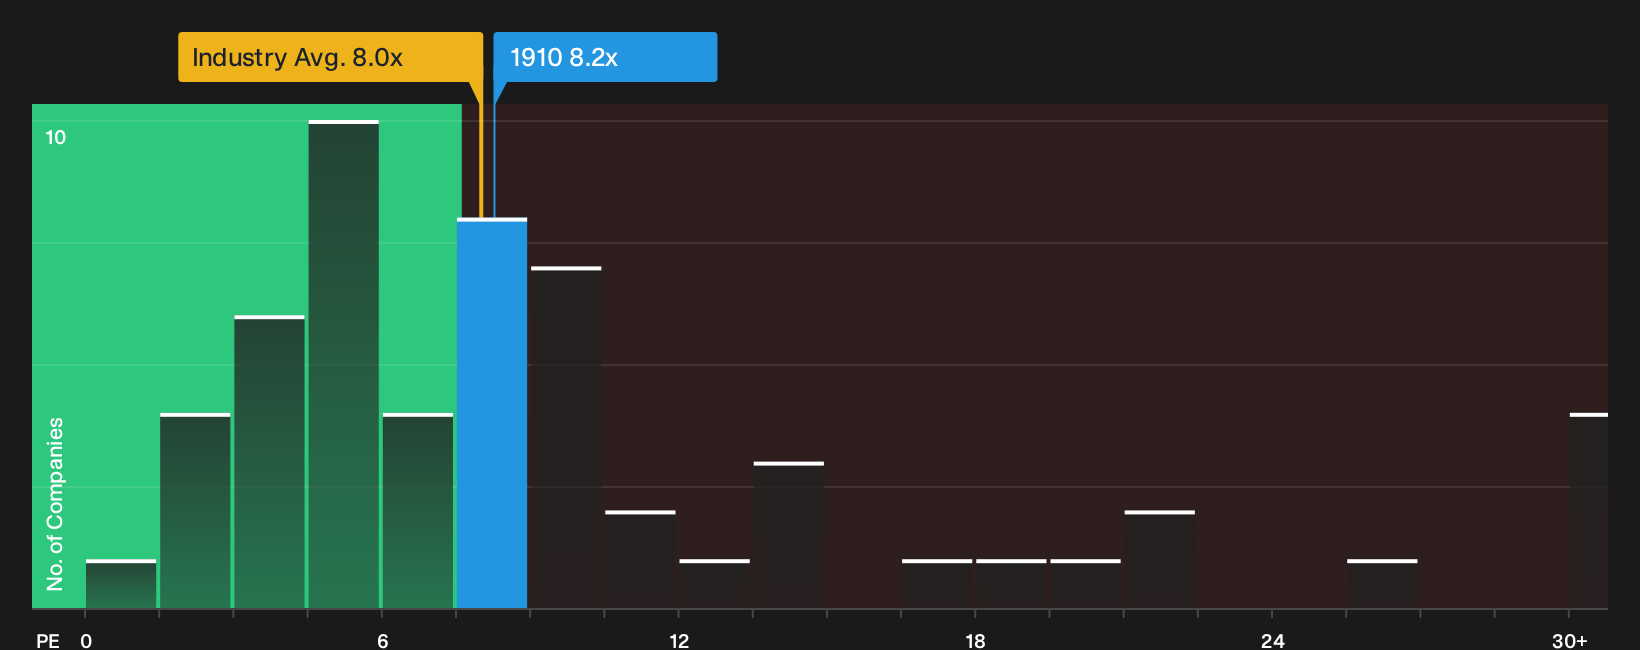
That 37% discount to fair value from the narrative model looks tempting. Yet on simple earnings metrics, Samsonite Group trades on a P/E of 8.2x, which is slightly higher than both the Hong Kong Luxury sector at 8x and its own fair ratio of 7.4x. That gap points to a less obvious margin of safety. Which lens do you trust more for your own decision making?
To pressure test these comparisons against detailed earnings, cash flow and peer checks, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Samsonite Group is clearly split, with investors flagging both pockets of risk and areas of real promise. Consider acting early, reviewing the data for yourself, and then weighing up the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Samsonite Group?
If Samsonite Group has your attention, do not stop there. Broadening your watchlist with other high quality opportunities can sharpen your judgment and reduce overreliance on a single story.
- Target resilient balance sheets by scanning a list of solid balance sheet and fundamentals (202 results) that filters for companies with strong fundamentals and financial stability.
- Hunt for potential bargains by reviewing a carefully curated 179 high quality undervalued stocks that aligns price, quality, and balance sheet strength.
- Prioritise consistency and capital preservation by checking a 226 resilient stocks with low risk scores that highlights businesses with lower risk profiles and steadier characteristics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com