


How Investors May Respond To Kinetik Holdings (KNTK) Earnings Estimate Upgrade
- Kinetik Holdings presented at the TD Cowen Annual Energy Conference in Austin on 24 September 2026, highlighting its Texas Delaware Basin midstream operations and project pipeline to an institutional audience.
- The sharp 91.2% upward revision in current year earnings estimates has increased focus on how Kinetik converts basin activity into fee-based cash flows and supports its income profile.
- We will now look at how Kinetik Holdings' investment narrative could be reshaped by the sharp upward revision in earnings estimates.
Scan how Kinetik Holdings compares to other income-focused midstream and energy plays by reviewing the hand picked 8 dividend fortresses that pair yield with underlying business strength.
Kinetik Holdings Investment Narrative Recap
For a shareholder in Kinetik Holdings, the core belief is that the Texas Delaware Basin remains busy enough to keep its gathering, processing, and pipeline assets heavily used on long term, fee based contracts. The near term story revolves around how quickly new and existing infrastructure like Kings Landing and acid gas injection systems fill with volumes, while cost inflation in power and compression remains manageable.
The conference appearance and sharp revision in earnings expectations shine a light on execution around that build out. The main short term catalyst is operational follow through that turns basin activity into stable cash flows. The biggest risk is still concentrated exposure to one region, combined with high capital needs and interest and dividend coverage that already look stretched.
The TD Cowen Annual Energy Conference slot on 24 September 2026 matters because Kinetik Holdings used a high profile forum to walk institutional investors through its Delaware Basin footprint and growth projects. That kind of detail helps investors judge whether current throughput and producer development plans support the recent reset in profit expectations.
Conference settings also let management explain how multi year capital projects, such as new plants, compression, and acid gas injection wells, line up against balance sheet constraints and dividend commitments. For readers watching catalysts, the key question is whether these projects can ramp efficiently enough, in a competitive sour gas treating market, to offset commodity price swings and rising operating costs without putting more pressure on leverage metrics.
Kinetik Holdings Earnings Reset Through The Numbers
Kinetik Holdings' narrative projects US$2.9b revenue and US$186.3m earnings by 2029. This implies 15.8% yearly revenue growth and an earnings increase of roughly US$0.9m from current earnings of US$185.4m.
The analyst framework now in focus is built on relatively modest earnings progression sitting on top of faster projected revenue expansion. Forecast earnings of US$186.3m by 2029 compare with earnings today of US$185.4m, so the story is less about a surge in profits and more about how the business mixes growth projects, leverage and dividends without stretching its balance sheet further.
Revenue assumptions are punchy. A 15.8% annual growth rate over three years implies a much larger top line feeding Kinetik Holdings' systems, even while profit margins are expected to compress from 9.8% to 6.4%. That combination points to a thesis where volumes and new projects such as Kings Landing and added acid gas injection capacity do the heavy lifting, while unit economics face pressure from competition, power costs and compression expenses.
On earnings, the consensus path is flat in dollar terms but harder in execution. A roughly US$0.9m uplift in profit over several years is small in absolute terms compared with the capital required to build and integrate new infrastructure. For income oriented readers, this raises a clear question: How much room is there to grow or even maintain payouts if revenue grows quickly but margins step down and interest costs stay elevated?
Analysts also bake in richer pricing for the equity. Their fair value framework references a P/E of 36.9x on those 2029 earnings, versus 23.5x today and an industry figure of 12.7x. That gap means the narrative around Kinetik Holdings is not only about project delivery and basin throughput but also about investors being willing to pay a premium multiple for fee based cash flows tied to the Delaware Basin.
The valuation math then links back directly to the operating plan. To line up with the US$2.9b revenue and US$186.3m earnings profile, the business needs to grow share count by 7% a year for the next three years, manage a leverage ratio currently at 3.6x and fund a heavy capital program across plants, power and AGI wells. Readers tracking income and risk may want to stress test how sensitive that story is to slower volume ramp, higher power prices or a more competitive sour gas treating market.
Uncover how Kinetik Holdings' fair value indicates an 8% potential upside to its current price that could narrow quickly if sentiment continues to improve.
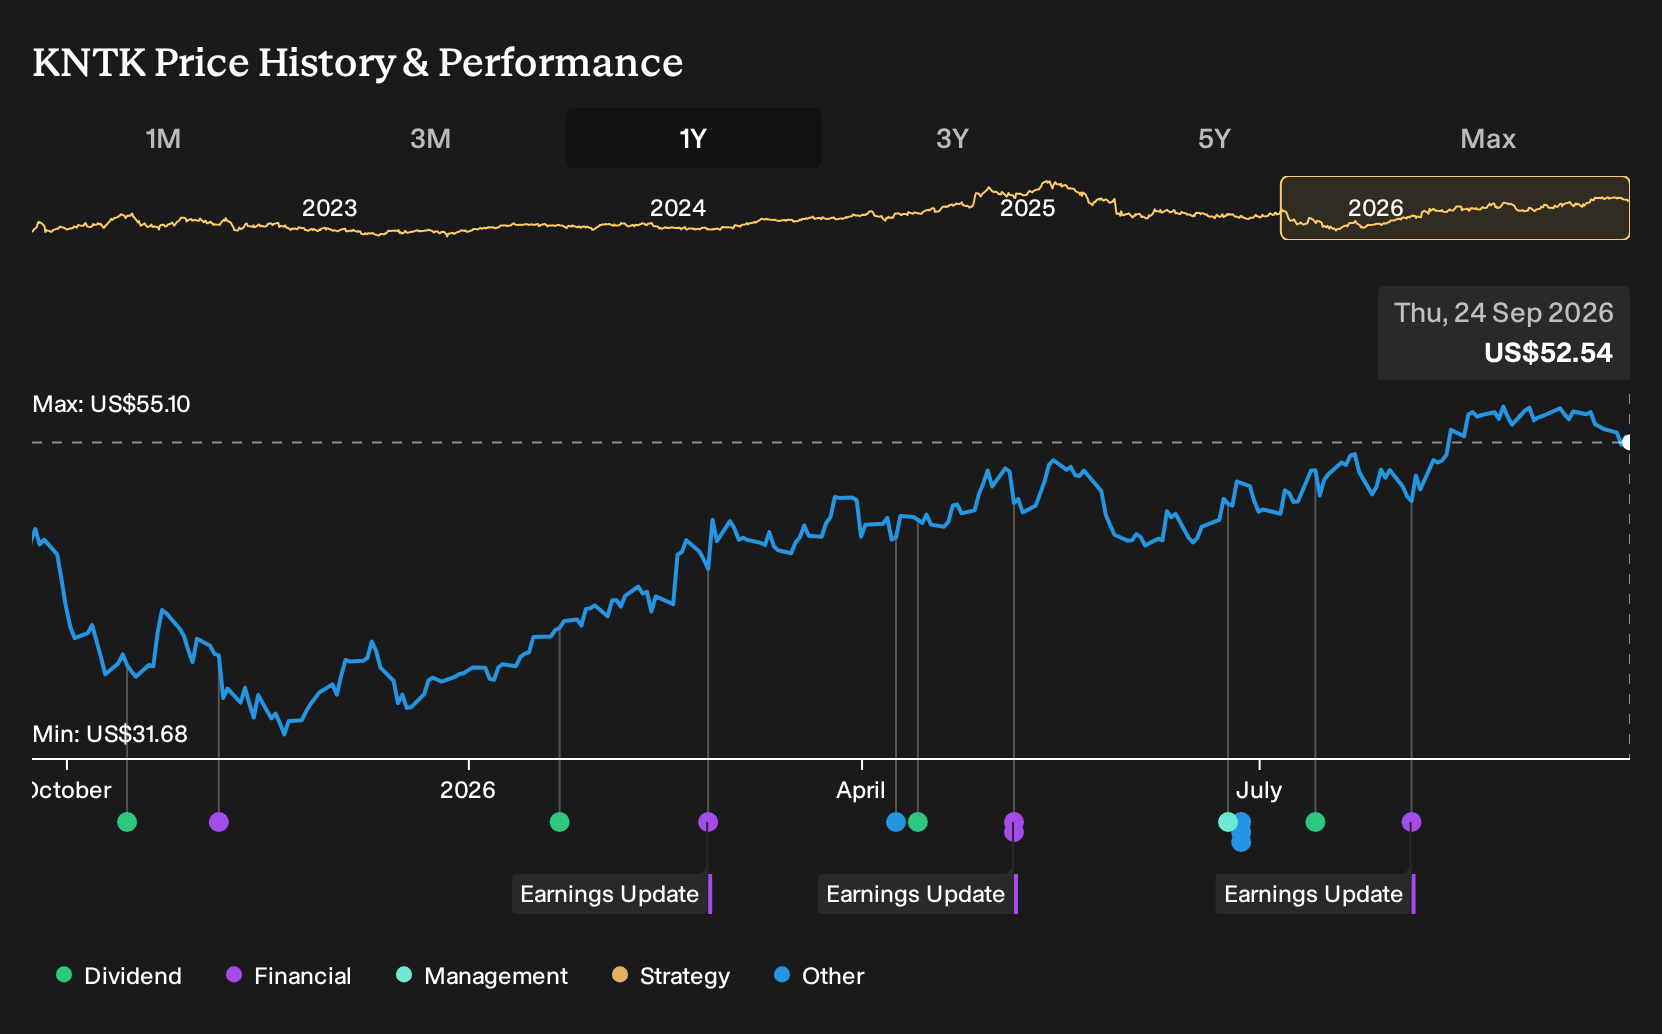
Exploring Other Perspectives
For Kinetik Holdings, the alternate view you may want to pressure test is dilution risk. The most pessimistic analysts were modelling 3 year revenue of about US$2.5b and 2029 earnings near US$160.6m before this conference. That is a much colder take on future payout headroom, and the Austin update could eventually shift those assumptions. Consider both stories, and then decide which set of trade offs feels more realistic to you.
Explore 3 other Kinetik Holdings fair value estimates, including one that indicates as much as 9% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Kinetik Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Kinetik Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kinetik Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Kinetik Holdings?
Once you have a view on Kinetik Holdings, it can help to line that up against other opportunities that fit different goals, from income resilience to balance sheet strength. The Simply Wall St Screener gives you a quick way to scan for stocks that match the type of risk and return profile you want to focus on next.
- If capital preservation sits high on your list, start with companies that show more robust financial footing using our list of solid balance sheet and fundamentals (24 results).
- For readers hunting for potential mispriced opportunities, compare your thesis on Kinetik with companies trading on more conservative valuation metrics through the 30 high quality undervalued stocks.
- If you prefer businesses that are off most investors' radar, broaden your watchlist with a 16 high quality undiscovered gems that combine quality fundamentals with lower profile coverage.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com