


Heat Pump Demand Could Be A Tailwind For Trane Stock
- Recent industry reports indicate that the North American residential HVAC and U.S. residential heat pump markets are projected to expand, supported by demand for energy efficient, connected home systems and favorable policy incentives, with Trane Technologies identified among the leading suppliers.
- The emphasis on smart, connected HVAC and sustainable refrigerants indicates that Trane Technologies operates in product areas where regulation, customer preferences, and technology are closely aligned.
- The following section assesses how Trane Technologies' investment narrative could be influenced by residential heat pump demand and policy trends.
Scan across Trane Technologies' peers by reviewing a curated group of HVAC and heat pump players, screened for resilient balance sheets and fundamentals, in our list of solid balance sheet and fundamentals (24 results)
Trane Technologies Investment Narrative Recap
To own Trane Technologies, you need to believe the push toward efficient, connected HVAC and refrigerant transitions supports steady demand across residential and commercial markets. The latest heat pump projections support that narrative by pointing to a larger pool of potential units for Trane Technologies to compete for rather than changing the story outright.
In the short term, the key swing factor still sits in Commercial HVAC bookings and how well pricing holds against tariffs and input costs. The biggest risk remains weakness in transport refrigeration and any crack in Trane Technologies’ ability to pass through costs without eroding margins, where recent heat pump headlines do not materially move the needle.
Recent commentary around a growing heat pump market ties most closely to Trane Technologies’ continued push into higher efficiency, connected systems and sustainable refrigerants. That focus links directly to the company’s core HVAC portfolio, where policy incentives and tighter emissions standards can influence replacement cycles and product mix toward higher value equipment.
For you as a shareholder, the operational question is execution. Can Trane Technologies convert regulatory change and incentive programs into booked orders while managing tariff exposure and transport softness? Delivery on that mix shift and pricing discipline would support the existing growth and margin expectations analysts model, while any stumble could expose how much of today’s story depends on flawless execution.
Trane Technologies’ current earnings are reported at US$2.9b, with analyst consensus pointing to US$4.5b of earnings and US$28.4b of revenue by 2029, which implies 9.5% yearly revenue growth and an earnings increase of about US$1.6b from today’s level.
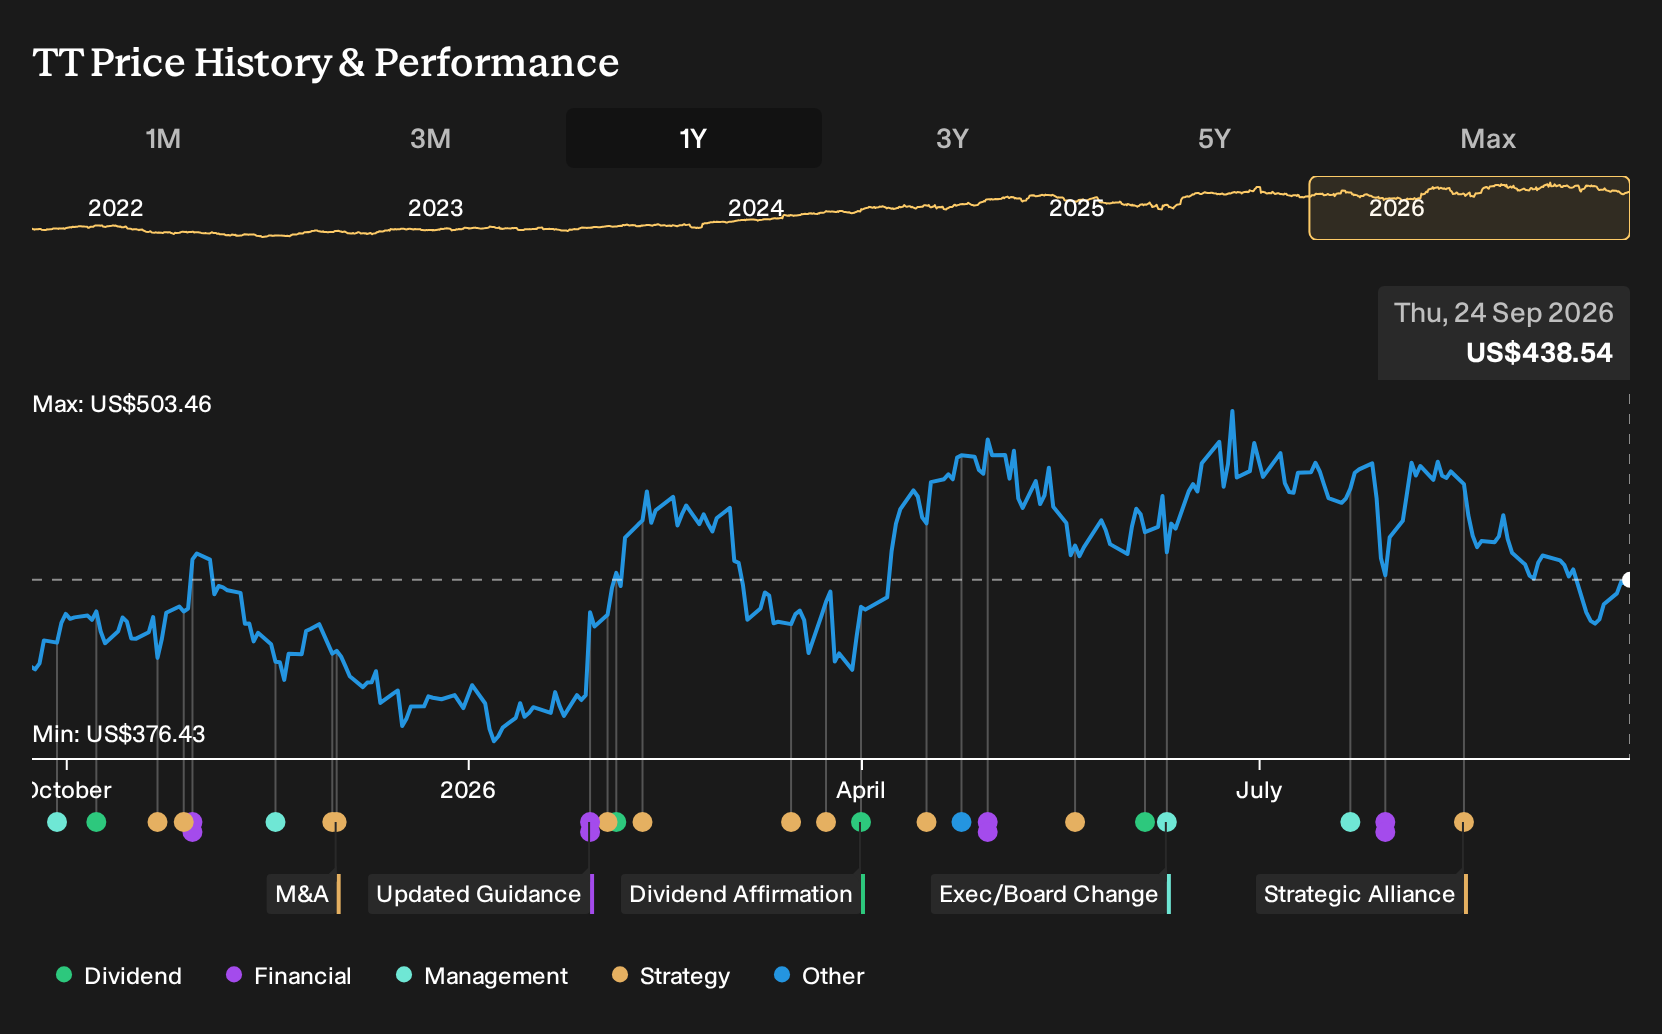
Uncover why Trane Technologies' fair value indicates a 19% potential upside to its current price that could close quickly as expectations catch up.
Exploring Other Perspectives
Some of the lowest Trane Technologies forecasts lean into a different worry. They focus on rapid adoption of next generation heat pump and distributed energy technology potentially capping demand for traditional HVAC. Those analysts were penciling in about US$27.8b of 2029 revenue and US$4.3b of earnings, which signals a meaningfully more cautious story. Both narratives were set before this latest residential heat pump news, so treat them as starting points and consider how your own view might shift as the data evolves.
Explore 4 other Trane Technologies fair value estimates, including one that suggests as much as 13% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Trane Technologies research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Trane Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Trane Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Trane Technologies?
If the Trane Technologies story has sharpened your thinking, broaden your watchlist by using the Simply Wall St Screener to spot other companies that match your preferred mix of quality, risk, and income potential.
- Prefer to focus on companies that already generate strong cash flows and trade below their estimated worth, while still maintaining solid fundamentals, by scanning our 30 high quality undervalued stocks.
- If resilience matters most to you, filter for businesses with sturdier balance sheets and dependable financial profiles using this curated list of solid balance sheet and fundamentals (24 results).
- For investors who want income on top of potential capital gains, check out a hand picked set of higher yielding stocks screened as 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com