


Do Aramco Contract Wins Change The Bull Case For SLB (SLB)?
- SLB reported that Aramco awarded it four three-year integrated well construction contracts in Saudi Arabia and that OQ Exploration & Production selected the company to deliver the Bisat-B Expansion Production Facility in Oman, including multi-year operations and maintenance support.
- These Middle East wins expand SLB's long-duration project workload and link higher value digital well construction and production services to recurring operations revenue in key hydrocarbon regions.
- Now the focus is on how SLB's multiyear Aramco well construction awards could shape the existing investment narrative around international spending.
SLB Investment Narrative Recap
Owning SLB means believing that global operators will keep leaning on large integrated projects, digital workflows and long-life production work rather than just short cycle drilling. The Aramco and Oman awards deepen that story by giving the company more line of sight on multi year activity in the Middle East and Asia, where spending has been relatively resilient.
The key near term swing factor is how global upstream budgets evolve in 2025 as some regions talk about trimming short cycle work. These contracts do not erase that risk, but they partially offset it by tying SLB to longer duration programs that rely less on quarterly commodity price moves.
The Aramco integrated well construction awards are the announcement that really matters here. Managing over 450 wells across three years, with options for up to two more, ties SLB’s well construction and digital units to a single operating model that aims for more consistent execution across planning, drilling and delivery.
For catalysts, this matters because it directly touches the themes analysts have highlighted. It leans into international spending, supports the push toward higher margin digital workflows, and broadens exposure to OPEX-like activity. The flip side is execution risk. Integration complexity, geopolitical disruption or operator spending cuts could still pressure volumes and margins in outer years.
What The SLB Forecasts Are Pricing In
SLB's narrative projects US$42.2b revenue and US$5.6b earnings by 2029. This is based on an assumption of 5.5% yearly revenue growth and an earnings increase of about US$2.3b from current earnings of US$3.3b.
Discover why SLB's fair value indicates a 19% potential upside to its current price that may not last much longer.
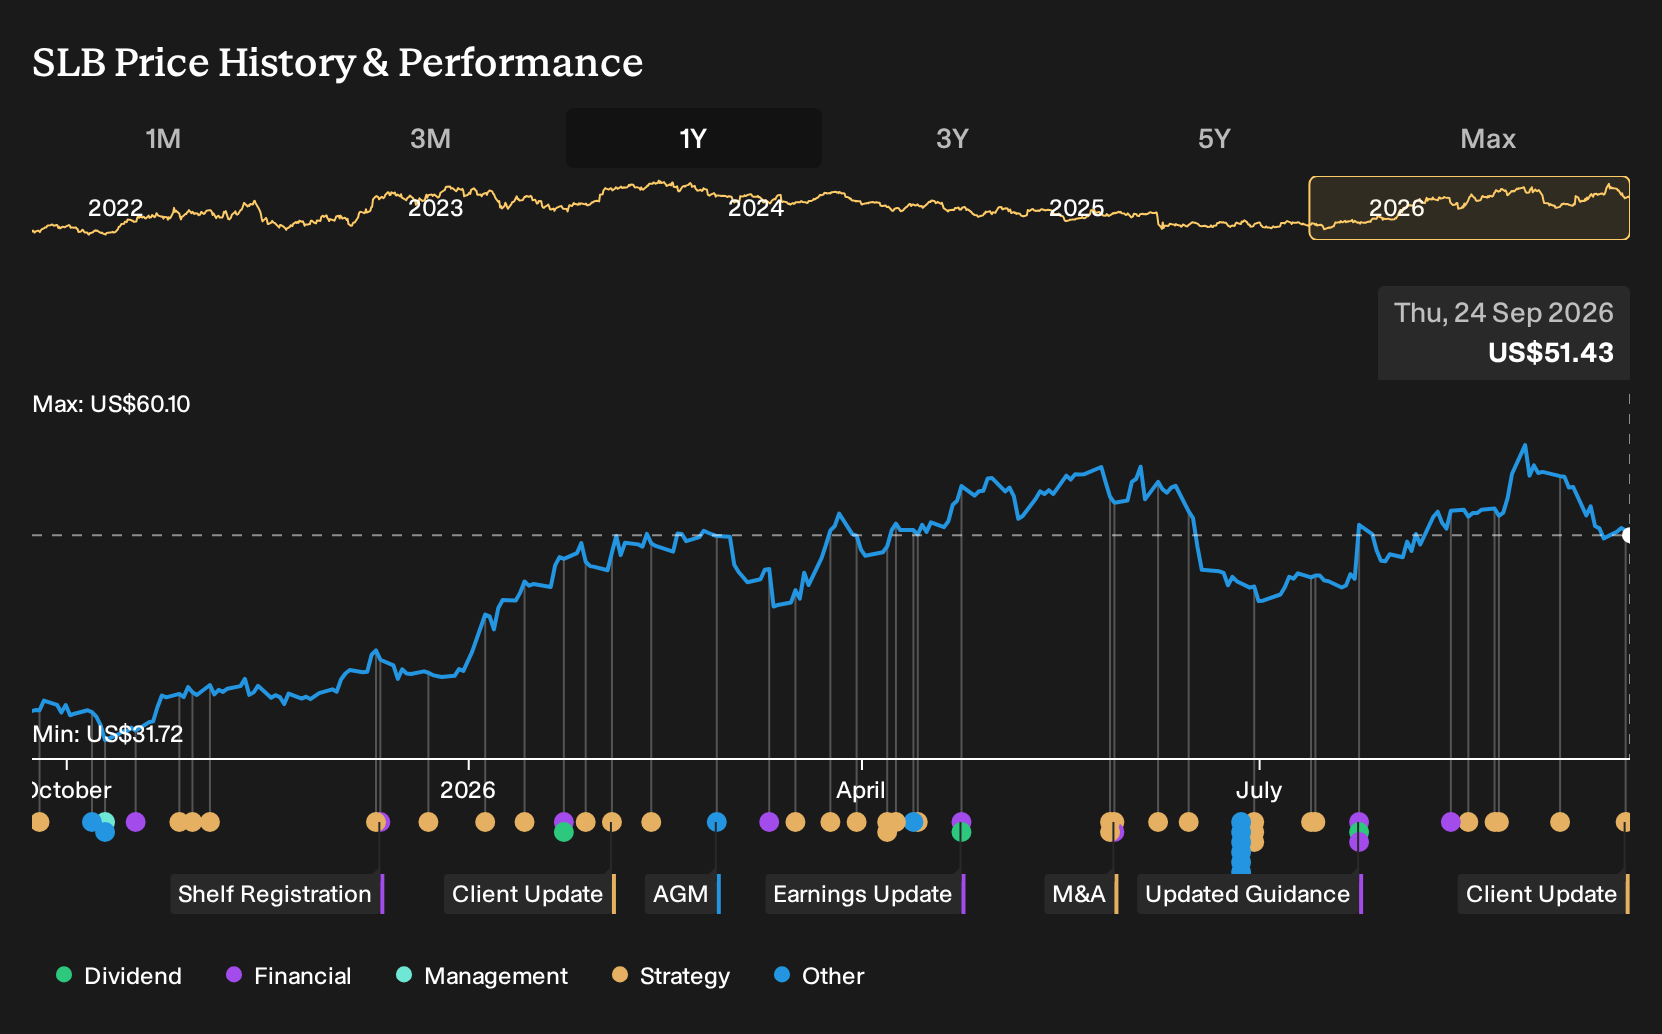
Exploring Other Perspectives
One alternate take is that SLB's real swing factor is the bullish digital story rather than contract wins. The most optimistic analysts were already penciling in US$48.9b of revenue and US$6.8b of earnings by 2029 before this news. That is a very different stance from consensus, and it may shift again as these Middle East awards sink in.
Explore 6 other SLB fair value estimates, including one that suggests as much as 74% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own perspective.
- A great starting point for your SLB research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SLB. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate SLB's overall financial health at a glance.
Looking For More Ideas Beyond SLB?
Once you have formed a view on SLB, it can help to compare that thesis with other companies that share similar qualities or offer very different risk and reward profiles. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If capital preservation comes first for you, start with a basket of companies that our filters flag as relatively steady using 30 resilient stocks with low risk scores.
- If you prefer to focus on financial strength and resilience, check out a list of solid balance sheet and fundamentals (24 results) and see which businesses meet your quality bar.
- If you are hunting for overlooked opportunities with strong fundamentals, widen your search through 16 high quality undiscovered gems and build a bench of ideas to track.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com