


Element Solutions (ESI) Dropped, What Is Behind Its Latest Move?
Element Solutions (ESI) lifted its 2026 adjusted EBITDA guidance, tying its outlook to organic expansion, AI related electronics demand, stronger cash generation, recent acquisitions, and efficiency gains that together have influenced investor sentiment toward the stock.
Recent trading has been choppy. The share price fell 2.7% over the last session and is down about 24% over 90 days. However, the year to date share price return of roughly 33% and 1 year total shareholder return of about 40% suggest Element Solutions still carries positive momentum in investors' eyes.
Scan beyond Element Solutions and evaluate other specialty chemicals and electronics suppliers that appear to be riding similar themes of AI demand and cash generation with our curated 16 high quality undiscovered gems.
Element Solutions lifted guidance and the share price has already run hard. The real tension now is simple: does the current valuation still leave enough upside to justify fresh risk?
Most Popular Narrative: 27% Undervalued
On Simply Wall St's most followed narrative, Element Solutions screens as undervalued, with a fair value estimate of about $47.38 compared to the latest close of $34.50. This raises a clear question about whether the current price fully reflects its AI linked materials story.
Accelerating investment in data centers and high-performance computing infrastructure is driving demand for advanced electronics materials and wafer-level packaging solutions, positioning Element Solutions as a key supplier for leading-edge semiconductor and circuit board applications and supporting robust future revenue growth.
See why 3 investors see Element Solutions as 27% undervalued.
Result: Fair Value of $47.38 (UNDERVALUED)
Still, the bullish Element Solutions narrative can fray quickly if cyclical electronics and auto demand weakens further or if competitive pricing pressures squeeze those modeled margins.
Find out about the key risks to this Element Solutions narrative.
Another View: Element Solutions Looks Expensive On Earnings
The first narrative presents Element Solutions as undervalued on a fair value of $47.38, yet the current P/E of 47.1x tells a very different story. That multiple sits well above the US Chemicals industry at 22.4x, the peer group at 24.6x, and even the fair ratio of 31.7x. Taken together, these figures point to a rich earnings-based valuation and raise a real question about how much good news is already priced in.
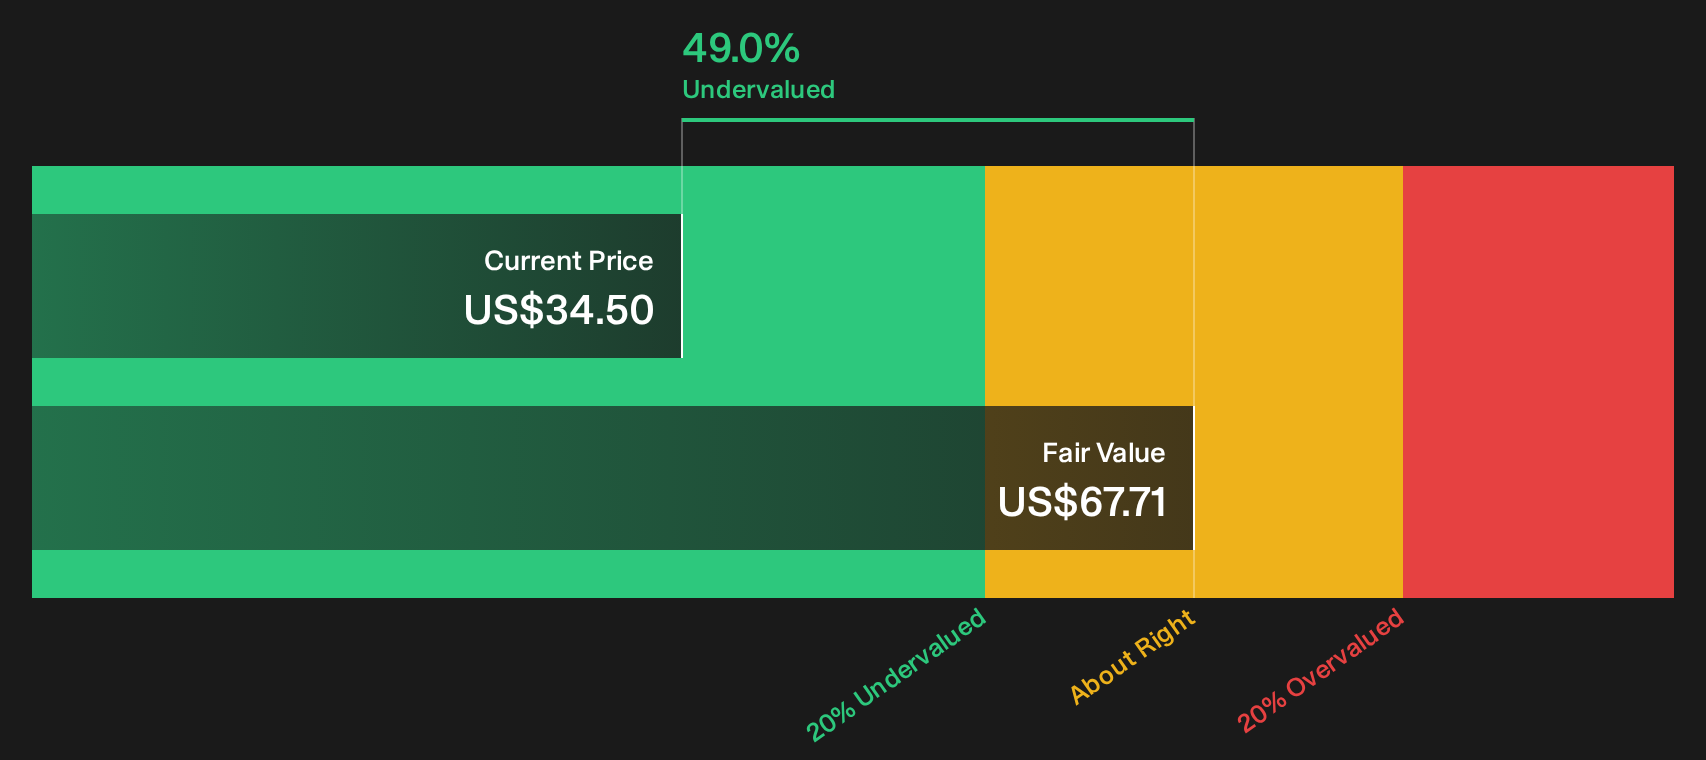
Our DCF model suggests one outcome, while the earnings multiple points to another. It is therefore worth seeing exactly how the cash flow approach gets to its number before deciding which signal matters more for you as an investor. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Element Solutions can feel confusing. Move quickly from headlines to hard numbers and weigh both upside and downside for yourself with the 3 key rewards and 2 important warning signs.
Looking For More Element Solutions Style Ideas?
Element Solutions has given you a clear example of how a focused thesis can play out. Do not stop here. Use the Simply Wall St Screener to surface fresh opportunities that match your own risk appetite and return goals.
- Target potential mispricing and hunt for quality companies trading below their implied value through the 30 high quality undervalued stocks.
- Strengthen your focus on balance sheet resilience by checking companies that pair funding flexibility with solid fundamentals using the list of solid balance sheet and fundamentals (24 results).
- Dial down risk and search for steadier profiles by scanning companies that score well on stability with the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com