


Top 3 Japanese Growth Stocks With ROE Over 22%
Japanese government bond yields recently reached a 30 year high as global bond markets sold off, which has pushed investors to reconsider where to put fresh capital. When borrowing costs climb, smaller Japanese companies with solid balance sheets and resilient business models can start to look more appealing. This article highlights three under followed, high quality Japanese stocks that sit on a specialist “hidden gems” shortlist.
The three companies below are just a starting sample. The full screen surfaced 71 more smaller Japanese businesses with equally compelling narratives that are not covered in this article.
If you want to move straight from ideas to your own shortlist, head into the High-Quality Undiscovered Gems screener to identify, filter, and analyze the highest conviction plays that fit your style and risk tolerance.
Sanki Engineering (TSE:1961)
Overview: Sanki Engineering provides HVAC, plumbing, and environmental control systems for commercial and industrial buildings, including clean-room facilities for semiconductor, pharmaceutical, and food manufacturers.
Operations: The business generates revenue of approximately ¥258.4b primarily from projects and services within Japan.
Market Cap: ¥384.7b
Sanki Engineering fits the High-Quality Undiscovered Gems theme through its specialist HVAC and clean-room work for mission critical industrial plants, while remaining diversified across broader building and machinery systems. Investors looking for smaller Japanese infrastructure players with earnings momentum, capital returns, and under-owned HVAC exposure may find the story compelling, depending on how one unseen pressure on project margins plays out.
That margin pressure question is exactly what the 3 key rewards and 2 important warning signs unpacks, so you can see where Sanki Engineering’s upside and stress points may really sit.

Tsugami (TSE:6101)
Overview: Tsugami manufactures CNC precision automatic lathes, turning centers, and other machine tools that help electronics, telecoms, and automotive manufacturers produce complex metal parts at scale.
Operations: Tsugami generates most of its roughly ¥136.4b segment revenue from China at ¥122.2b, with smaller contributions from Japan and India.
Market Cap: ¥238.4b
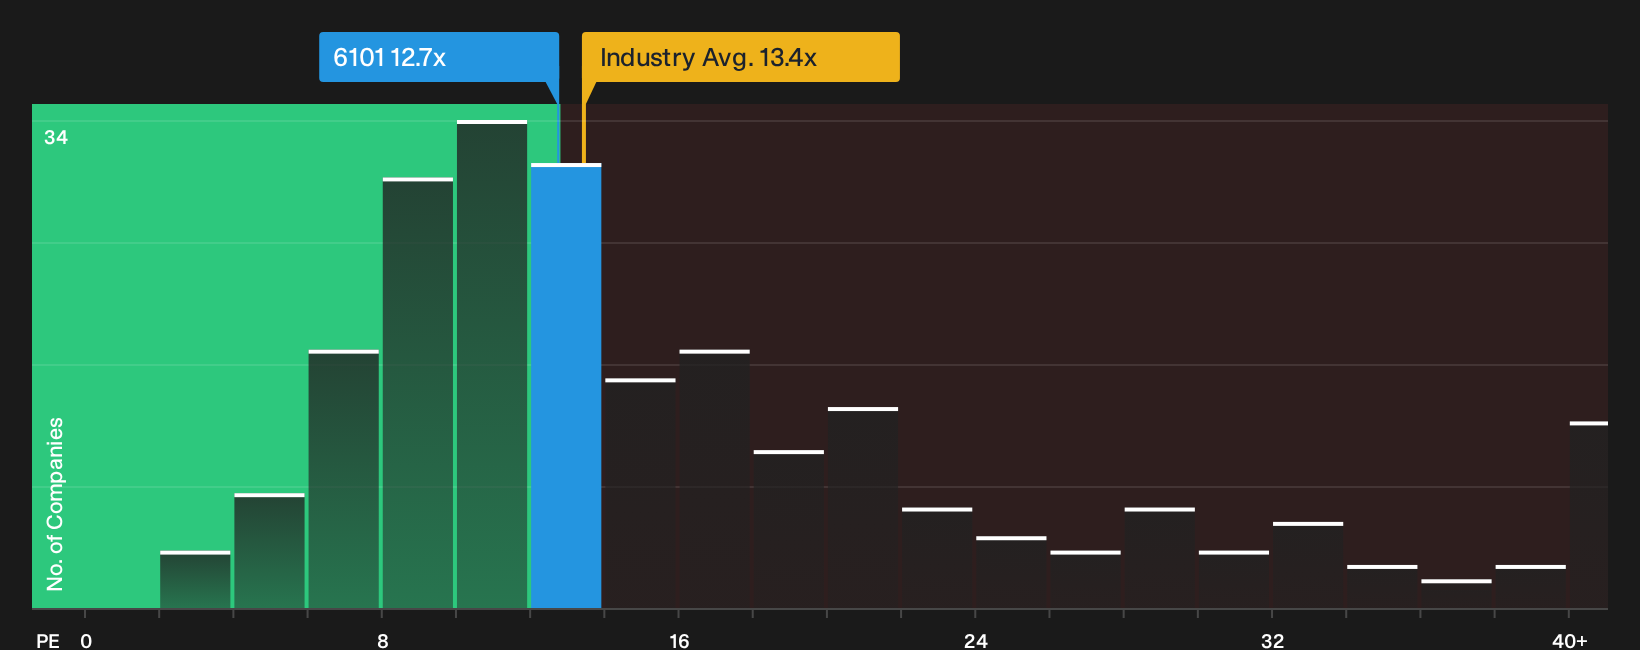
Tsugami aligns with the High-Quality Undiscovered Gems theme through its precision CNC lathes and turning centers that support production for electronics, telecoms, and auto suppliers. Earnings grew 53.6% last year with net margins at 13.6% and ROE at 23.2%, while the stock trades on a P/E of about 12.7x. This leaves one key assumption about future tool demand and pricing to do the heavy lifting.
If that single demand and pricing swing is what matters for you, head to the analyst forecasts for Tsugami to see how expectations line up with that bet.
santec Holdings (TSE:6777)
Overview: santec Holdings develops high margin optical components and test instruments such as tunable and swept source lasers and OCT systems for telecom, medical imaging, and photonics R&D customers.
Operations: The group generates roughly ¥25.3 billion from optical measuring instruments, ¥6.5 billion from optical components, and ¥2.9 billion from other activities.
Market Cap: ¥253.1 billion
santec Holdings offers focused exposure to high precision optics used in telecom networks and OCT medical imaging. The company is backed by forecast earnings growth of around 13.45% a year and historically strong earnings momentum, yet remains a smaller Japanese stock that many large funds may still overlook, depending on how one quiet shift in pricing power and product mix plays out.
That quiet shift is exactly what the 2 key rewards and 1 important major warning sign unpacks so you can see where pricing power and product mix could be quietly reshaping the santec Holdings story.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the next breakout list will not stay quiet for long. Scan these fresh ideas while the momentum is still under the radar for now.
- Target cash generative potential and balance sheet strength by running the 18 high quality undervalued stocks before the crowd starts paying attention and price gaps close.
- Explore the build out of next generation power systems by scanning the 39 power grid technology and infrastructure stocks while these infrastructure stories are still priced as afterthoughts.
- Review the curated 93 robotics and automation stocks to stay informed on developments in automation and robotics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com