


FC 27 Launch Altering The Investment Case For EA Stock?
- Electronic Arts released EA SPORTS FC 27 in September 2026, alongside major updates to EA SPORTS FC Mobile and new social-focused features such as The Grounds, refreshed Career Mode tools, and expanded Football Ultimate Team options across consoles, PC, and mobile.
- The launch deepens Electronic Arts' football ecosystem by tying console, PC, and mobile experiences together. This may influence player engagement patterns, content spending, and the mix of live-service versus full-game revenue over time.
- Focus now turns to how this expanded EA SPORTS FC 27 ecosystem, particularly The Grounds social mode, could influence Electronic Arts' investment narrative.
Compare how Electronic Arts’ football and hockey launches stack up against other publishers building long-lived franchises by reviewing our hand picked 16 high quality undiscovered gems in the gaming and digital entertainment space.
Electronic Arts Investment Narrative Recap
To own Electronic Arts, you need to be comfortable with a business that leans heavily on recurring live services and annual sports launches, while some older IPs and Apex Legends face pressure on bookings. The most important short term catalyst is whether this year’s slate deepens engagement enough to offset those weaker franchises and softer discretionary spending.
The biggest risk is that player time and spending drift away faster than EA can refresh its portfolio and live service loops. The FC and NHL launches help, but do not fully resolve concerns around portfolio transition, Apex dependence, and the timing gap between new franchises and waning titles.
Among the recent developments, EA SPORTS FC 27 looks closest to the heart of the current story. It ties together console, PC and mobile, adds social play through The Grounds, and leans into live modes like Football Ultimate Team. These all connect directly to the push for higher engagement and steadier service revenue around the 2026 World Cup window.
Execution risk remains. EA still has to keep players moving from older FC entries into FC 27 and then into FC Mobile and live content, which past migration issues flagged as a concern. For you, the key question is whether this connected football ecosystem can meaningfully counteract weaker Apex Legends bookings and uneven consumer spending over the next year.
Electronic Arts' current analyst narrative points to revenues of US$8.9b and earnings of US$1.7b by 2029. That pathway assumes revenue growth of 5.9% per year and an earnings increase of roughly US$813m from current earnings of US$887m.
Uncover why Electronic Arts' fair value indicates a 3% potential downside to its current price, which leaves little room for error.
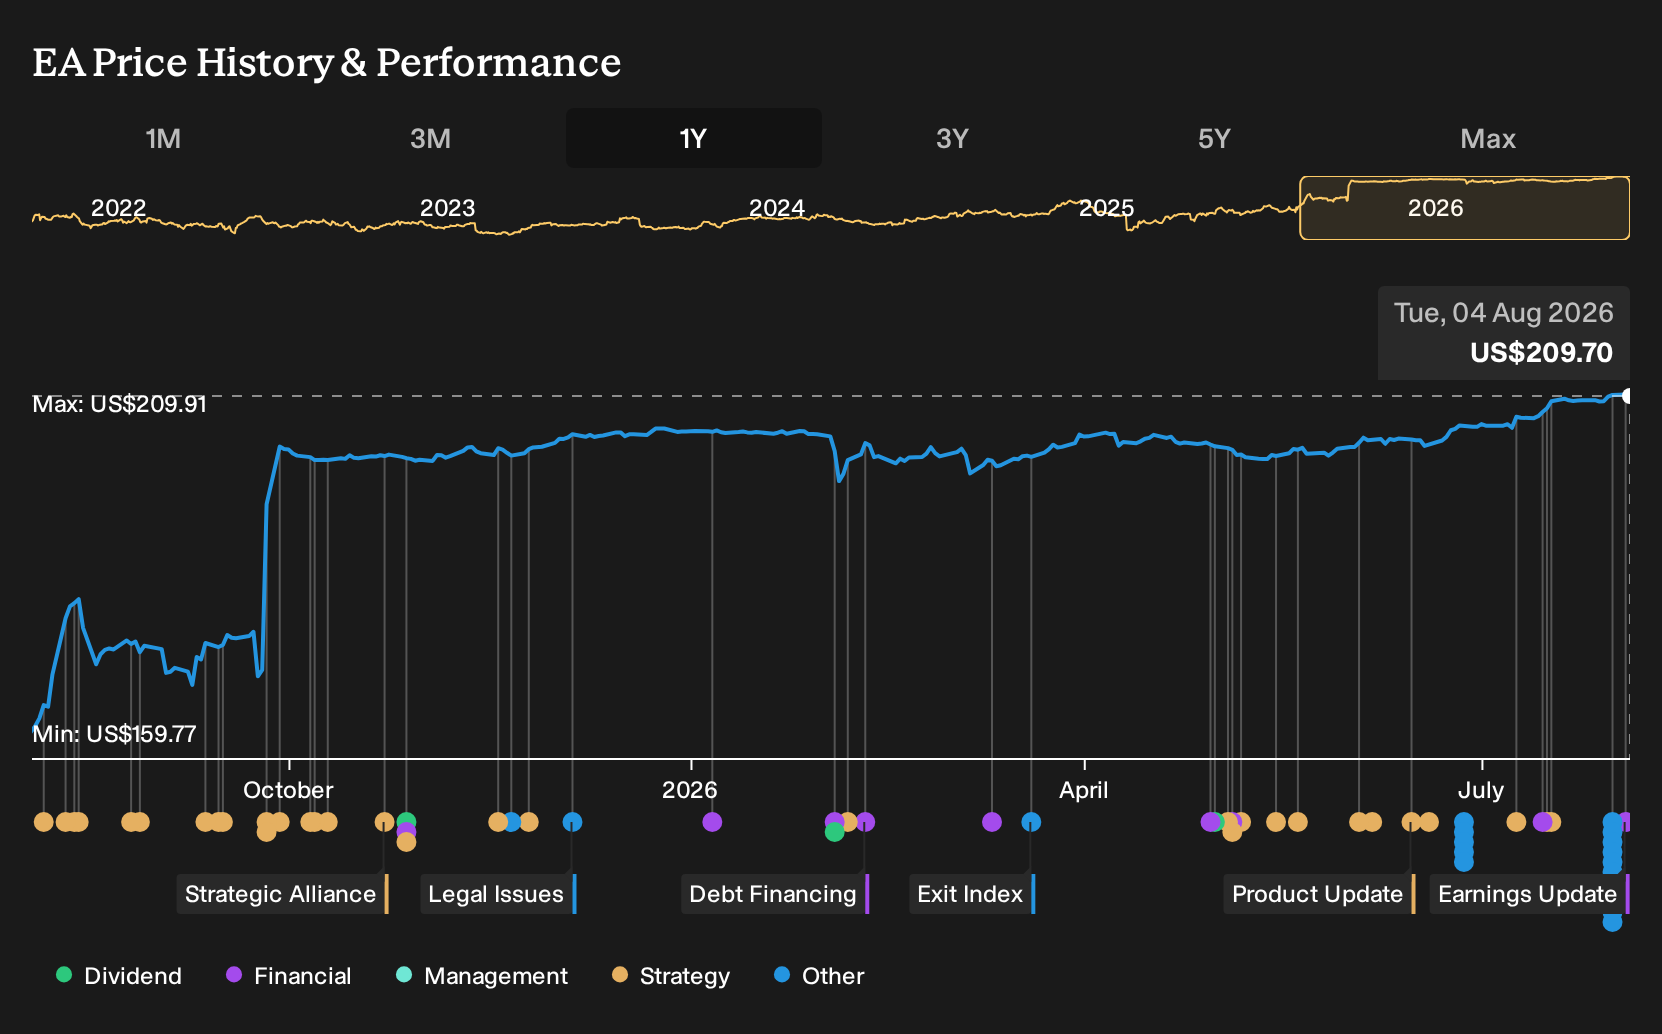
Exploring Other Perspectives
Simply Wall St Community users have only two fair value estimates for Electronic Arts, spanning roughly US$161 to just over US$202 per share. That small sample already shows a wide gap. When you layer in the rumored Savvy Games Group merger, along with the fresh FC 27 and NHL 27 launches, you get very different views on future earnings resilience. Explore those alternative opinions before framing your own thesis.
Explore another Electronic Arts fair value estimate, including one that suggests it could be worth as much as $202.80.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Electronic Arts research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Electronic Arts. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Electronic Arts' overall financial health at a glance.
Looking for more investment ideas beyond Electronic Arts?
If you want to stress-test your thesis on Electronic Arts and see how it stacks up against other opportunities, the Simply Wall St Screener can help you widen the field while keeping clear filters around quality, risk, and income.
- For investors who care most about financial strength and resilience, start with a list of solid balance sheet and fundamentals (24 results) and see which businesses might handle stress better than peers.
- If capital preservation and smoother rides matter to you, check stocks that screen well on stability and risk using the 30 resilient stocks with low risk scores to spot candidates with fewer red flags.
- Income focused readers can zero in on companies that combine higher yields with payout durability by scanning through the 8 dividend fortresses for potential ideas.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com