


3 Canadian Dividend Stocks With Yields Over 3%
With central banks tightening policy to keep inflation in check, borrowing costs have climbed and many growth stories look less appealing. Reliable Canadian dividend payers offering yields above 3% can feel like getting paid to wait while markets digest these rate moves. This article highlights three high-yield dividend stocks with payouts that screen as covered, growing and relatively steady, so you can focus on income while others chase the next headline.
The three dividend stocks covered below are just a sample set, and the full screen surfaced 17 more income ideas with equally compelling narratives that are not covered in this article. To go wider and deeper on the opportunity set, head straight to the Dividend Powerhouses (3%+ Yield) screener to filter, analyze, and identify the highest-conviction dividend plays.
Sun Life Financial (TSX:SLF)
Sun Life Financial is a global insurer and asset manager built around life, health, and wealth products that generate steady premiums and fees, creating the kind of recurring cash flow this dividend screen looks for.
Sun Life Financial generates most of its revenue in Canada at about CA$15.7b, with sizeable contributions from the U.S. at roughly CA$13.0b, Asia at CA$2.6b, and its asset management arm at around CA$7.7b. This supports a CA$62.8b market value and a dividend focus.
That cash engine matters even more when you connect it to where Sun Life is still expanding, particularly in regions that could reshape long term income streams for dividend investors.
"Strong growth across Asian markets, particularly in Individual Protection and wealth products, is expanding Sun Life's addressable market and creating significant new revenue sources; this is reinforced by double-digit sales and CSM growth in the region year-over-year."
The real tension for Sun Life’s dividend appeal now rests on how one quieter profit lever evolves beneath those headline growth numbers.
How that quieter profit lever evolves is exactly what the full narrative for Sun Life Financial unpacks. It highlights where Sun Life Financial’s dividend story could be masking accelerating or stalling cash generation.

Whitecap Resources (TSX:WCP)
Whitecap Resources focuses on turning Western Canadian oil and gas production into dependable cash flow. This is aligned with what the Dividend Powerhouses screen targets when identifying covered, growing income streams backed by physical production.
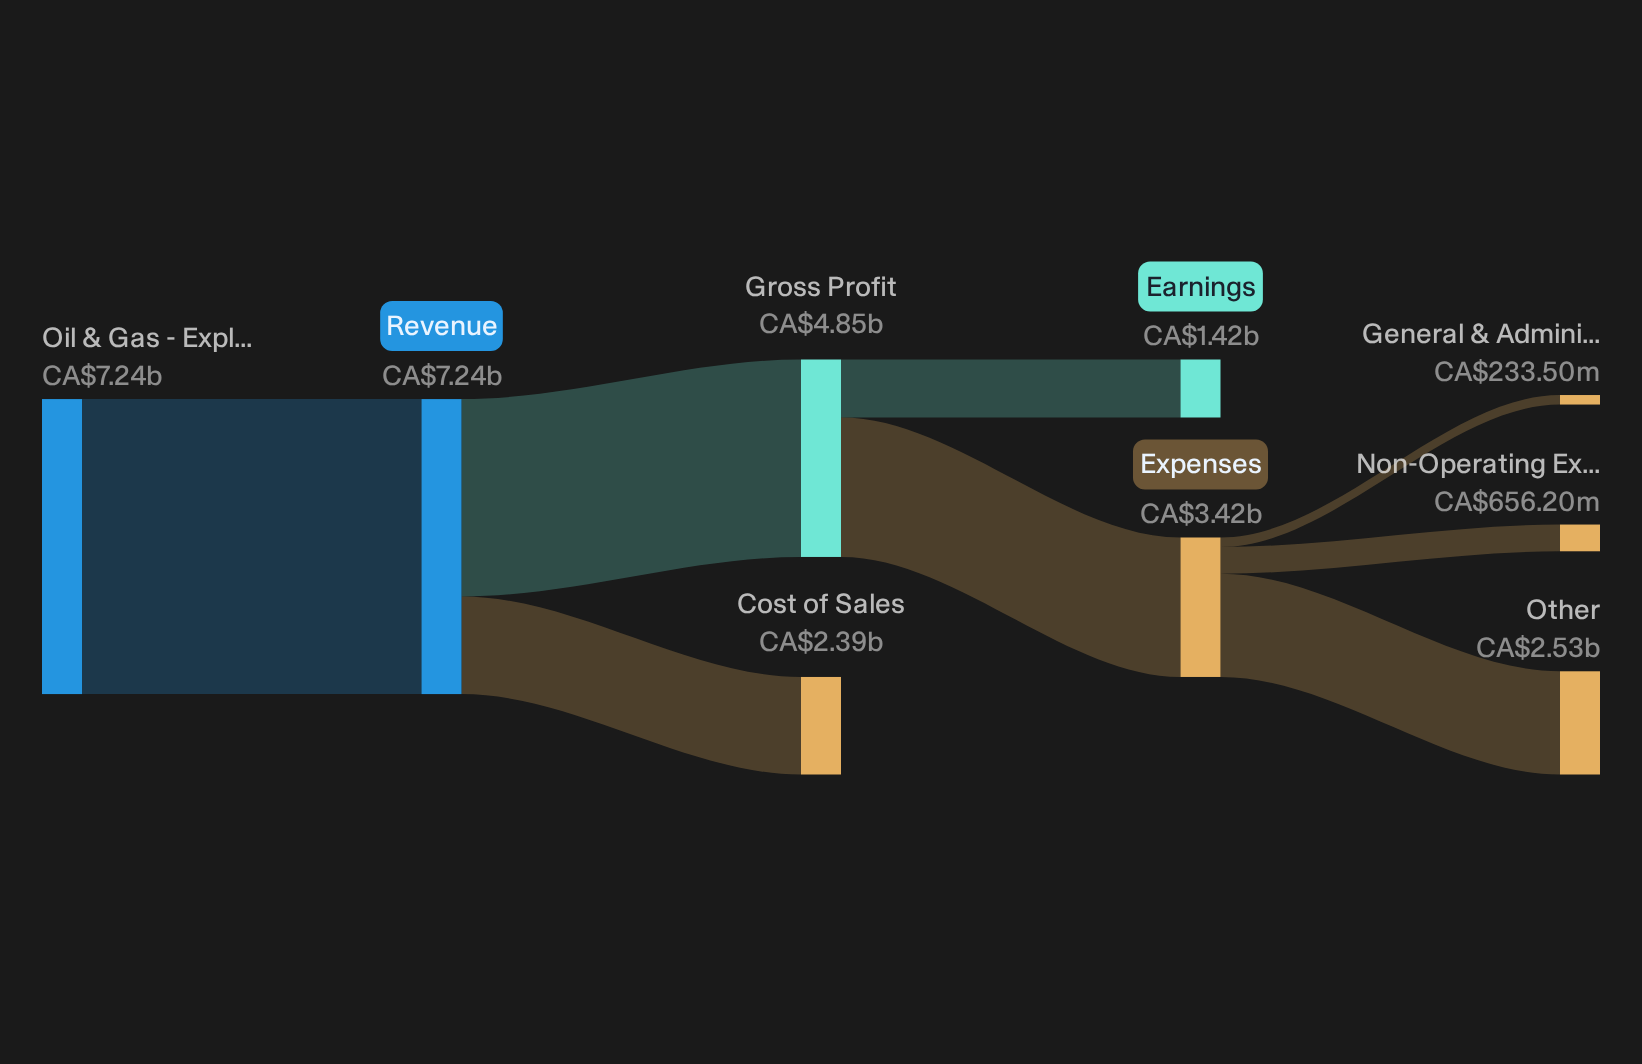
Whitecap Resources acquires and develops oil and gas fields across Western Canada, with all CA$7.2b of revenue coming from exploration and production. Every dollar is currently generated in Canada, and the business carries a market value of about CA$22.2b.
"Successful integration of Veren assets is resulting in early operational synergies, cost reductions, and improved capital efficiency, which are expected to unlock further sustainable cost savings and margin expansion over the next 6 to 12 months, directly supporting higher future earnings and free cash flow."
How the dividend profile responds if any single pressure on future cash generation moves in the wrong direction will be crucial.
If that risk dial matters to you, the full narrative for Whitecap Resources shows where Whitecap Resources’ cash engine could be accelerating, stalling, or quietly decoupling from the headline story.
North West (TSX:NWC)
North West runs grocery and everyday goods chains such as Northern, NorthMart, Giant Tiger, and Cost-U-Less that sell essential products in remote and rural regions. It generates about CA$1.5b of revenue in Canada and CA$1.1b internationally, and carries a market value near CA$2.5b.
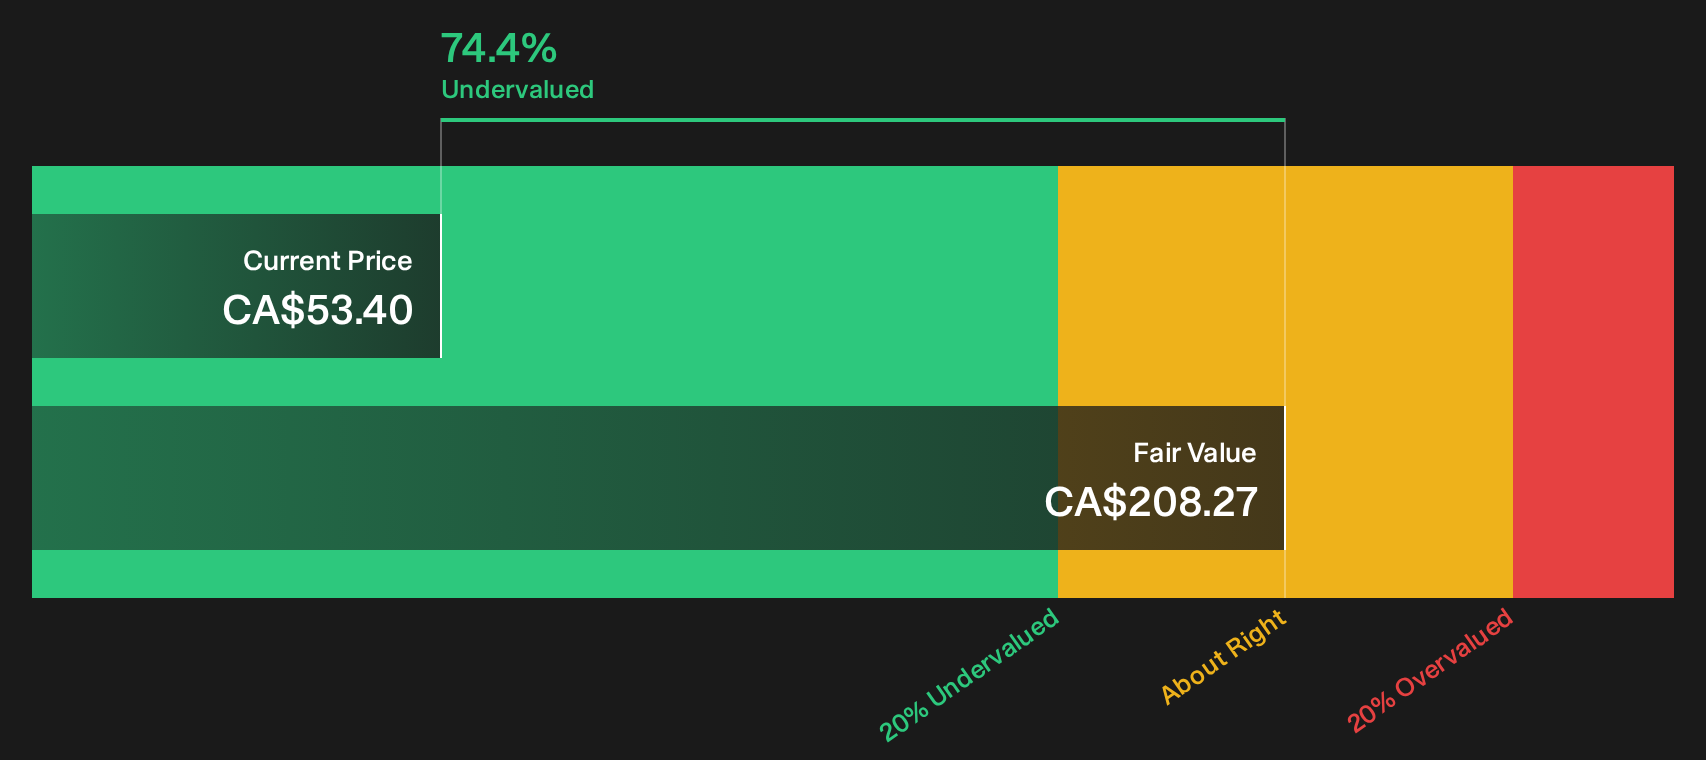
North West offers a 3.15% yield underpinned by essential retail cash flows that support growing dividends, including a Q2 2026 raise to $0.42 per share. The stock trades well below one estimate of fair value and on a cheaper P/E than peers, with dividend resilience hinging on how one cost pressure evolves relative to those steady sales.
That cost pressure is exactly where the 2 key rewards and 1 important major warning sign shows whether North West’s yield is quietly compounding strength or masking a brewing squeeze on future payouts.
Seeking Alternatives Before Everyone Else?
Fresh stock ideas do not stay under the radar for long. Screens update, momentum shifts, and the best entry points get caught quickly, so act now.
- Hunt for smaller companies already throwing off real profits through the 37 profitable AI stocks that aren't just burning cash before momentum sends these stories flying beyond your preferred entry range.
- Target resilient operators with cleaner balance sheets using the list of solid balance sheet and fundamentals (7 results) while their strengths are still priced as if they are ordinary.
- Position ahead of infrastructure themes that can build for years by scanning the 39 power grid technology and infrastructure stocks while these plays are still dropping quiet clues, not headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com