


Top 3 Japanese Growth Stocks To Watch In September 2026
Japanese government bond yields recently hit a 30 year high as part of a wider global bond selloff, which has pushed borrowing costs sharply higher. That kind of backdrop tends to reward companies that can fund growth internally and where executives have meaningful skin in the game. This article highlights three fast growing Japanese stocks with significant insider ownership that some investors use to seek resilient, aligned growth stories.
The three companies below are just a sample of this theme, with the full screen surfacing more than 100 additional businesses where fast growth potential lines up with substantial insider commitment and aligned incentives that are not covered here. To go broader and identify your own high conviction ideas, head straight into the Fast Growing Stocks With High Insider Ownership screener
Micronics Japan (TSE:6871)
Micronics Japan develops equipment that tests semiconductors and inspects liquid crystal displays and body measurements, placing it in the test side of chip production. The probe card business generates ¥84.9b of revenue compared with ¥1.4b from TE equipment, and the stock is valued at around ¥533.5b.
Earnings growth of 89.4% over the past year and guidance pointing to ¥103.8b in 2026 net sales link Micronics Japan to the fast growing stocks with high insider ownership theme through its probe card and semiconductor test line. Forecast earnings expansion of about 24.9% a year and a higher dividend outlook are key features of this high growth story, with outcomes likely to depend on how future demand and pricing develop.
With that kind of growth profile already on the table, go straight to the 2 key rewards and 1 important major warning sign to see what might accelerate or derail the story.

JX Advanced Metals (TSE:5016)
JX Advanced Metals is a long-established Japanese materials supplier focused on copper and rare metals, with its Semiconductor Materials arm feeding fast growing chip and electronics demand through sputtering targets, compound semiconductors and high purity copper products. The group is valued at about ¥3.39t.
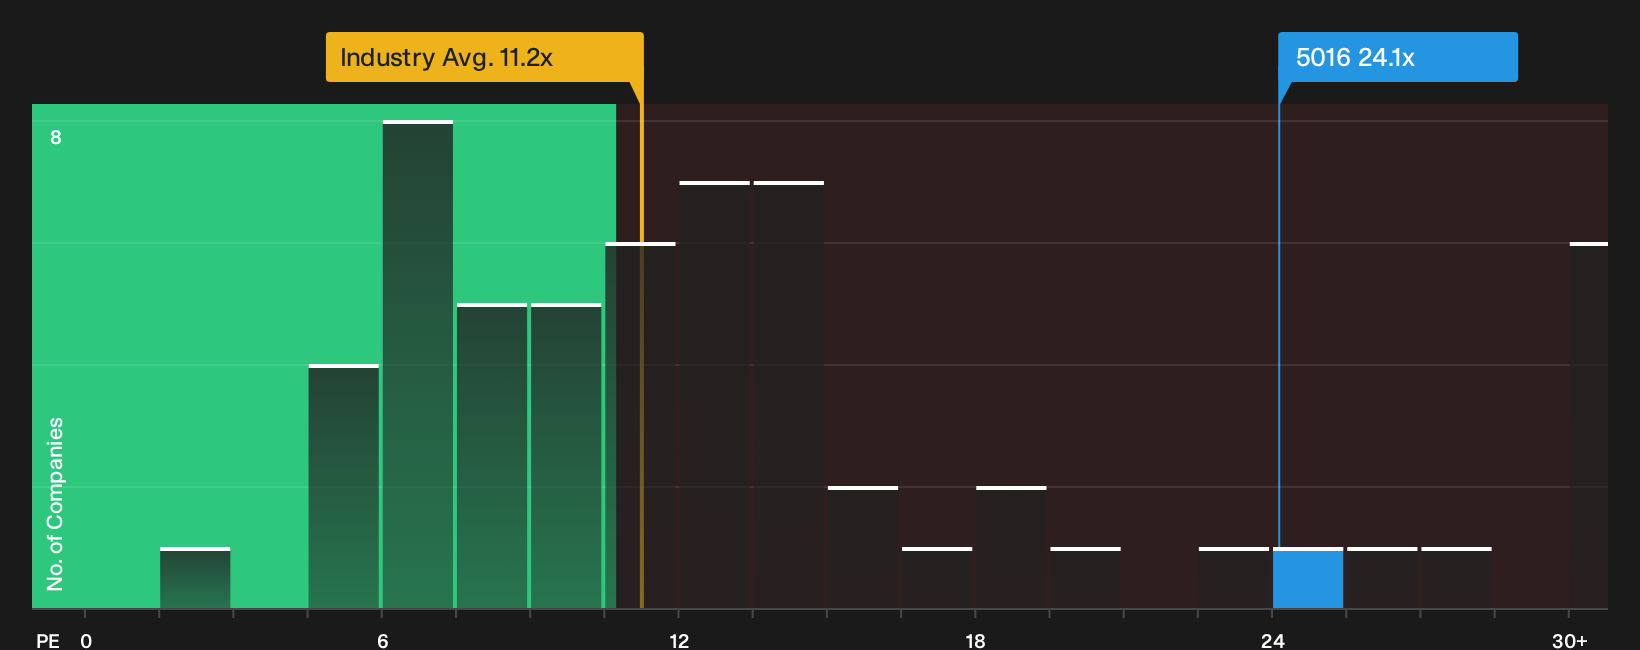
JX Advanced Metals connects cleanly to this screener because the Semiconductor Materials business serves high growth chip and electronics demand. Earnings grew 91.8% last year and forecasts point to faster profit expansion than the wider Japanese market. Investor interest hinges on what happens when that semiconductor appetite meets its premium P/E and rising margins.
That premium P/E and rising margins raise a simple question, so use the 3 key rewards and 1 important major warning sign to see whether JX Advanced Metals’ momentum is masking any pressure points
Rakuten Group (TSE:4755)
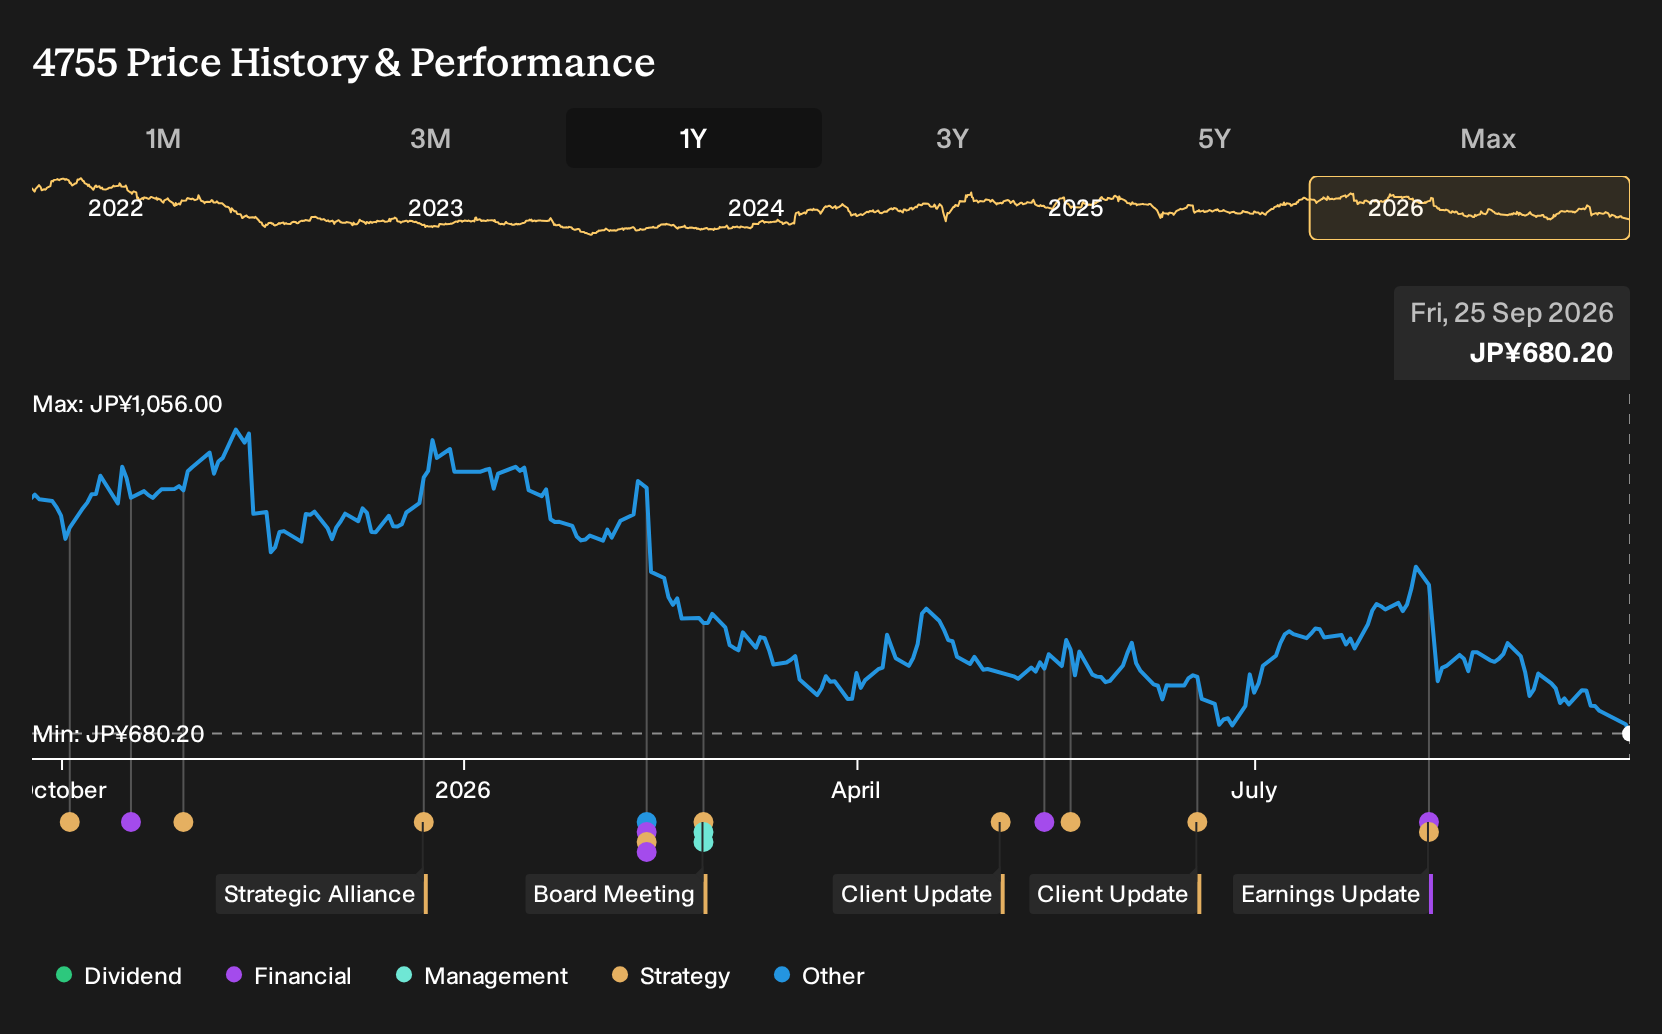
Rakuten Group fits into the fast growing stocks with high insider ownership theme through its ambitious Rakuten Mobile rollout, layered on top of a large e-commerce and fintech ecosystem that management is working to scale into a more profitable, tightly connected services platform.
Rakuten Group runs e-commerce marketplaces, fintech services and digital communications. Internet Services generated ¥1.40t in revenue, Fintech ¥1.09t and Mobile ¥512.6b, and the business is valued at about ¥1.51t.
"Rakuten Mobile is achieving rapid growth in subscribers, expected to drive the growth of the entire Rakuten ecosystem, contributing significantly to future revenue increases through cross-selling of Rakuten services to mobile users."
What happens to longer term earnings depends heavily on how one still unresolved pressure around funding and profitability in that rollout plays out.
That funding question is exactly what the full narrative for Rakuten Group unpacks, separating short term pain from areas where the Rakuten Group ecosystem could be accelerating beneath the surface.
Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first, and the market can catch up fast once momentum, breakouts and new themes get noticed. Scan these under the radar for now opportunities and consider them promptly.
- Identify resilient cash generators before defensive money rotates by running the list of solid balance sheet and fundamentals (22 results) while it still highlights businesses the crowd has not fully priced in.
- Monitor the next leg of the AI infrastructure build out and track the 84 AI infrastructure stocks before capital concentrates in the same short list of enablers.
- Prepare for potential shifts in the metal cycle and let the 36 elite gold producer stocks surface producers that could matter most if momentum returns to the sector.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com