


Paylocity Holding (PCTY) Lands The Jets, Is The Upside Already Priced In?
Why the New York Jets deal matters for Paylocity
Paylocity Holding (PCTY) just landed a headline customer, becoming the official human capital management platform for the New York Jets. This puts its HR, payroll and workforce tools in front of a high profile sports organization.
Recent trading tells a mixed story for Paylocity Holding. The 90 day share price return is up 35.06%, yet the 1 year total shareholder return is down 12.31%. This suggests that near term momentum is improving while longer term holders are still underwater.
The New York Jets agreement comes just weeks after Paylocity expanded its financing flexibility through a US$1.75b amended revolving credit facility. Together, these developments may be reshaping how investors think about both its growth options and risk profile at the current US$143.64 share price.
Capitalize on the attention around Paylocity Holding and this Jets deal by reviewing a curated 30 high quality undervalued stocks that may also be attracting interest as sentiment shifts around quality and price.After a 35% rebound in 90 days but a 12% decline over the past year, Paylocity Holding now forces a cleaner question. Is the meaningful upside still in front of you, or has most of it already been priced in as the valuation resets?
Most Popular Narrative: 16% Undervalued
On the most followed narrative, Paylocity Holding screens as undervalued, with a fair value estimate of $172 against the recent $143.64 close, which puts the Jets win into a wider pricing debate around growth, cash generation and capital returns.
The current valuation implies that, despite a share price that has declined about 44% over three years and guidance for slower revenue growth, the market still assigns meaningful value to Paylocity’s margin structure, cash generation and capital returns such as large buybacks.
See why 12 investors see Paylocity Holding as 16% undervalued.
Result: Fair Value of $172 (UNDERVALUED)
Still, if Paylocity Holding delivers slower recurring revenue than the guided 7% to 8% or AI add ons fail to gain traction, this underpriced narrative could unravel.
Find out about the key risks to this Paylocity Holding narrative.
Another View on Paylocity Holding’s Valuation
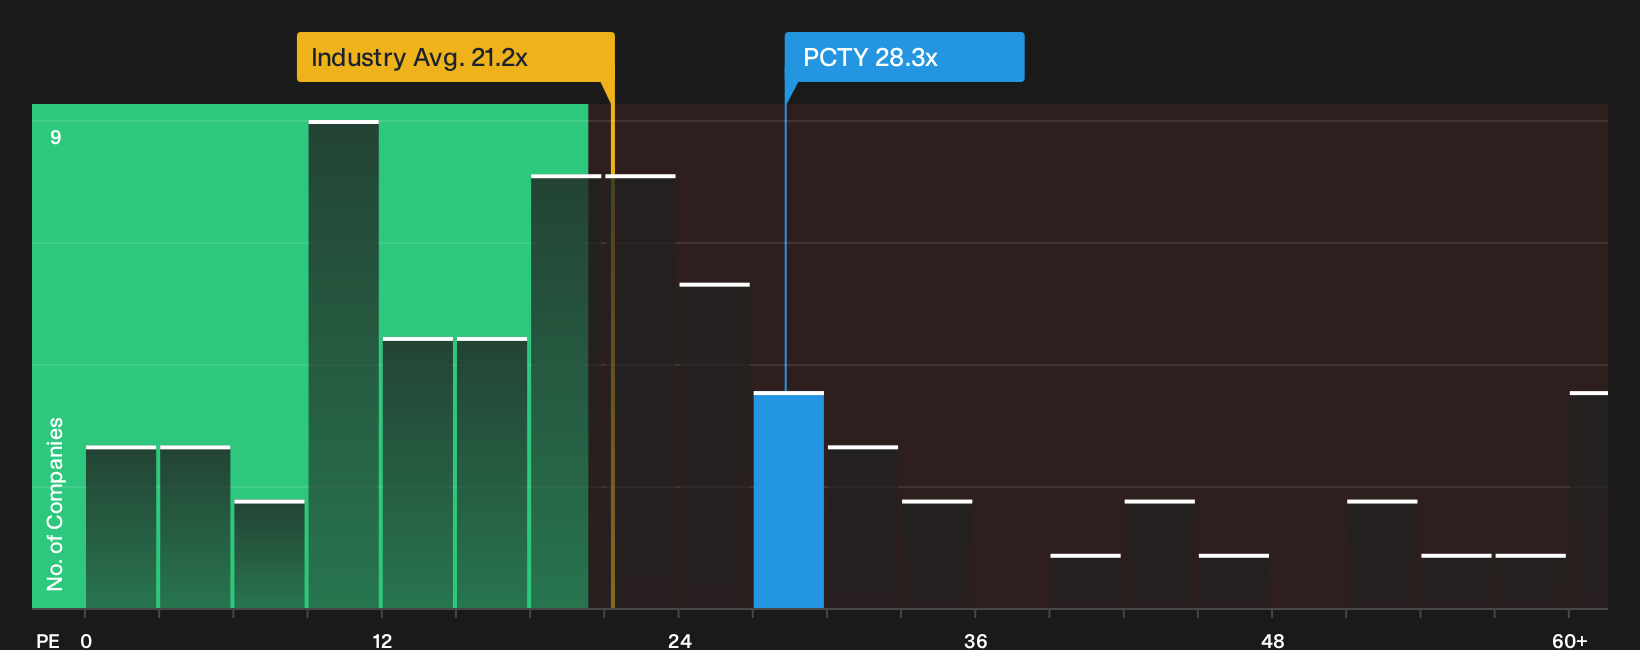
The first narrative leans on analyst targets and a fair value of $172 for Paylocity Holding. A simple earnings multiple paints a sharper picture. PCTY trades on a P/E of 28.3x, compared with a fair ratio of 21.9x, the Professional Services industry at 21x and peers at 15.2x. That is a sizeable premium. It raises the question of whether the DCF upside story or the richer multiple better reflects the risk being taken.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Paylocity Holding can be useful if you move fast and test the assumptions yourself instead of leaning on headlines or single metrics. To balance the optimism around upside with the concerns already flagged in the data, review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Paylocity Holding?
If Paylocity Holding has your attention, use that momentum. Cast a wider net and pressure test your thesis across other opportunities before capital moves on.
- Target potential mispricings by scanning a focused set of opportunities using the 30 high quality undervalued stocks.
- Protect your downside first by filtering for companies with stronger finances through the list of solid balance sheet and fundamentals (24 results).
- Hunt for overlooked potential by checking the 16 high quality undiscovered gems before others catch on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com