


Carrier Global (CARR) Issued Fresh Guidance, Is It A Bargain Or Fully Priced?
Carrier Global (CARR) set fresh expectations for investors after issuing third quarter 2026 guidance, projecting about US$6 billion in sales and giving the market a clearer read on upcoming performance.
Recent trading tells a mixed story for Carrier Global. The 1 month share price return is down 6.24% and the 3 month share price return has fallen 25.44%, while the 1 year total shareholder return is down 5.17%. This points to fading momentum despite a modest 2.52% share price gain year to date.
Scan how Carrier Global’s guidance-driven reset compares with peers by lining it up against 30 high quality undervalued stocks that also pair meaningful scale with solid balance sheets.
Bulls see Carrier Global’s guidance and recent growth rates as backing a re‑rating. Bears point to the sharp share price slide. Which case does the valuation put ahead?
Most Popular Narrative: 29% Undervalued
Against a last close of $54.87, the most followed narrative for Carrier Global points to a fair value of $77.62, framing today’s price as a sizeable discount and putting the burden of proof on whether the growth story and margin work can deliver.
Carrier Global is building a larger presence in AI and data center cooling, with about $2 billion of 2026 data center revenue already in backlog, an over $8 billion company backlog that is heavily tied to commercial and data center projects, and a dedicated U.S. manufacturing site planned to roughly double Americas data center capacity, which can support future revenue and earnings.
See why 30 investors see Carrier Global as 29% undervalued.
Result: Fair Value of $77.62 (UNDERVALUED)
Still, Carrier Global’s margin story depends on offsetting higher input costs and tariffs, while uneven regional demand in transport refrigeration could dilute the broader thesis.
Find out about the key risks to this Carrier Global narrative.
Another View: Carrier Global On Earnings Multiples
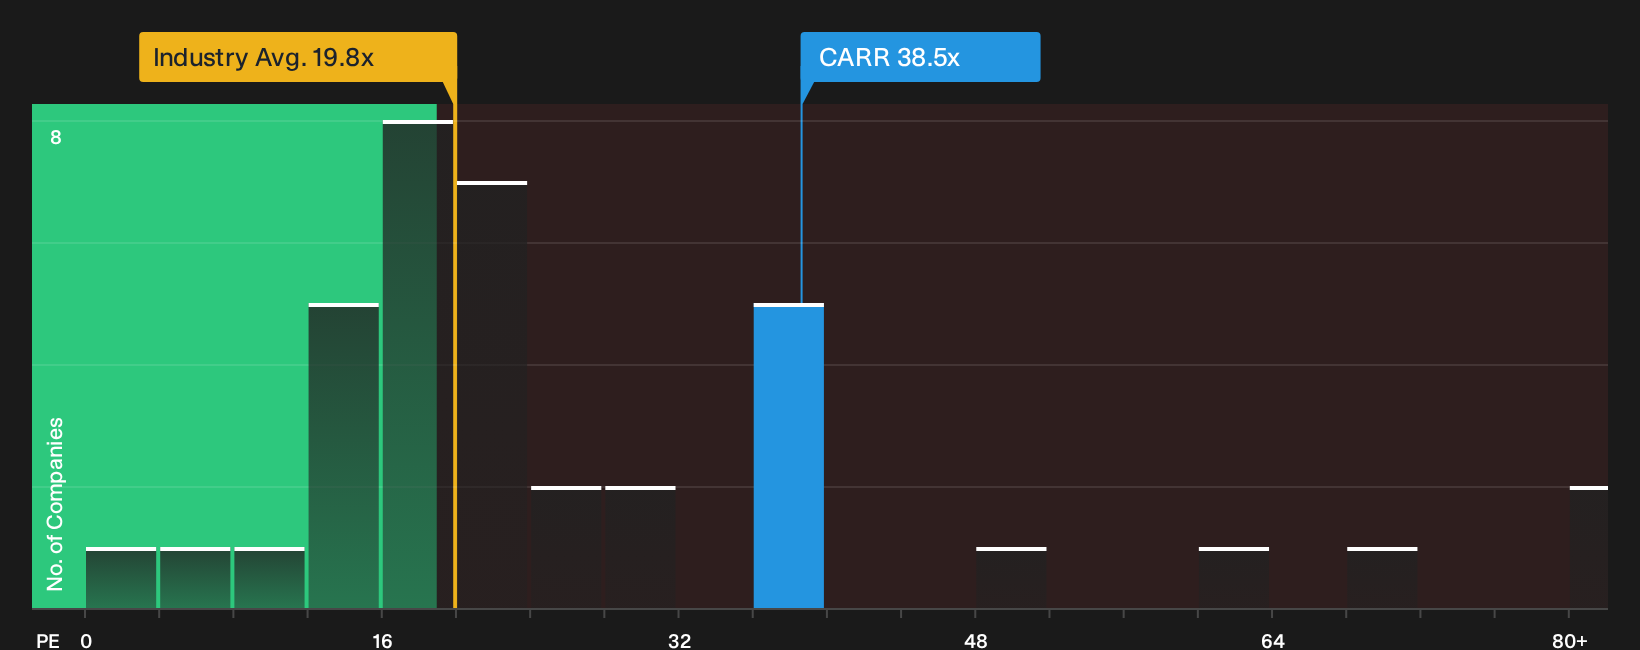
The first narrative frames Carrier Global as undervalued against a $77.62 fair value. On earnings multiples, the picture looks less generous. The stock trades on a P/E of 38.5x, compared with 19.8x for the US Building industry, 27.1x for peers, and a fair ratio of 34.7x that the market could move toward over time.
That gap means investors are paying a richer price than both sector averages and the fair ratio. The key question is whether Carrier Global’s growth and AI data center story fully justify that premium or leave limited room for error.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Carrier Global’s valuation story so far. Act quickly, review the full breakdown of sentiment and weigh both sides for yourself with 3 key rewards and 1 important warning sign
Looking For More Investment Ideas Beyond Carrier Global?
If Carrier Global’s setup has you thinking harder about pricing and quality, do not stop here. Broader idea hunting now could shape your next few portfolio moves.
Use the Simply Wall St Screener to pressure test your thinking against different styles of opportunities before the market moves on.
- Target potential mispricing by zeroing in on companies that combine quality fundamentals with room for upside through the 30 high quality undervalued stocks.
- Strengthen your income stream by scanning for resilient payers with higher yields using the 8 dividend fortresses.
- Dial down risk by focusing on financially robust businesses through the list of solid balance sheet and fundamentals (24 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com