


Casey's General Stores Stock: Is CASY Outperforming the Consumer Staples Sector?
With a market cap of $22.1 billion, Casey's General Stores, Inc. (CASY) is a leading convenience-store retailer headquartered in Ankeny, Iowa. The company operates nearly 3,000 stores across 19 states, with a particularly strong presence in smaller communities.
Companies valued between $10 billion and $200 billion are generally considered "large-cap" stocks, and Casey's fits this criterion perfectly. Its competitive strength lies in its large regional footprint, strong brand loyalty, and differentiated food offering, particularly its popular pizza and prepared foods. Its combination of fuel, convenience merchandise, and higher-margin food drives customer traffic and profitability, while its scale provides purchasing and operating advantages. The company’s proven ability to expand through new-store development and acquisitions further strengthens its position and supports long-term growth.
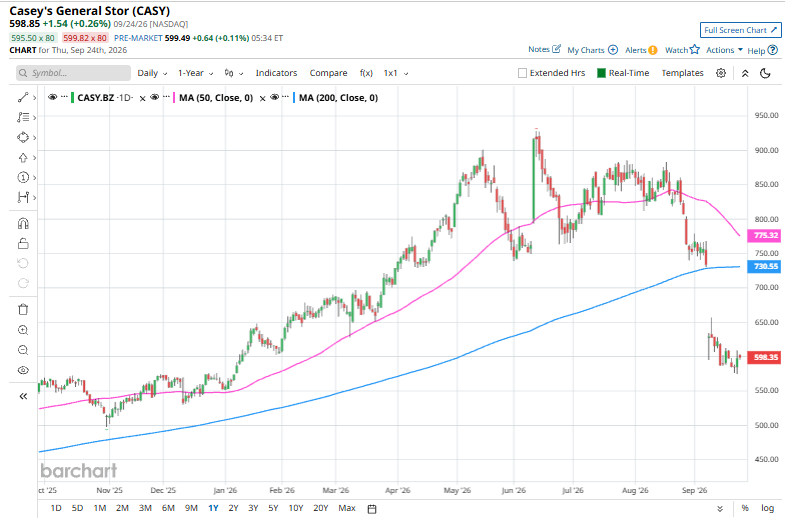
Casey’s shares have taken a sharp hit from their June peak, sliding 35.5% from the 52-week high of $927.85 and decreasing 25.3% over the past three months, significantly underperforming the State Street Consumer Staples Select Sector SPDR Fund (XLP), which climbed 3.2%.
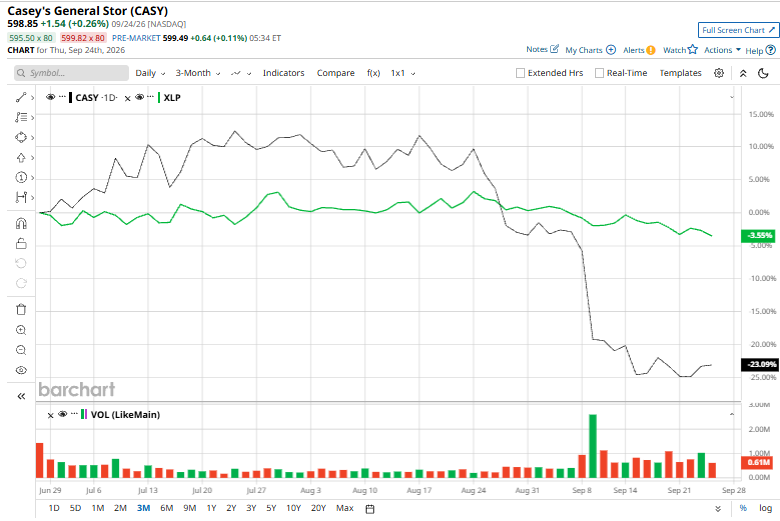
Still, the longer-term picture remains stronger. CASY is up 8.4% year to date and 9.5% over the past year, ahead of XLP’s 5.2% and 4.1% gains, respectively.
Casey’s stock had maintained a bullish position above its 200-day moving average for roughly a year, but that trend has recently weakened, with shares slipping below the key long-term indicator earlier this month. The stock has also fallen below its 50-day moving average at the end of last month, signaling growing near-term selling pressure.
Amid Fed uncertainty, elevated oil prices, inflation, and interest-rate concerns, Casey’s General Stores stands out as a defensive retailer with a relatively resilient business model. The company is consolidating a highly fragmented convenience-store market through organic growth and acquisitions while maintaining low debt, enabling it to self-fund expansion, pay dividends, and repurchase shares. At the same time, Casey’s is evolving beyond its traditional fuel-and-convenience model, with its growing prepared-food business, particularly pizza and sandwiches.
Its annual dividend of $2.60 yields 0.44%, but Casey’s impressive dividend track record stands out, with 27 consecutive years of increases and 35 years of uninterrupted payouts, reinforcing its appeal as a defensive, long-term compounder. Moreover, the company recently approved a quarterly dividend of $0.65 per share payable November 13, 2026, to shareholders of record on November 1, 2026.
Casey’s General Stores delivered strong Q1 FY2027 earnings on Sept. 8, but its shares plunged 14.2% in the following trading session as investors focused on softer same-store sales and an unchanged full-year outlook. Its total revenue rose 24.3% year over year to $5.68 billion. Inside same-store sales increased 3.2%, down from 4.3% a year earlier, while total inside sales climbed 5.6% to $1.78 billion. Net income rose 27.1% to $273.7 million, while EPS jumped 27.7% to $7.37. The company continued to expand its store network and integrate acquisitions, ending the quarter with 2,959 stores, 64 more than a year earlier, after opening nine new stores and completing 12 acquisitions during the quarter. Management also said the Fikes acquisition integration was ahead of schedule. Casey’s expects to open at least 120 stores during fiscal 2027 through a combination of acquisitions and new-store construction.
Casey’s grim performance stands out even more against rival Williams-Sonoma, Inc. (WSM), whose shares have continued to gain ground. WSM has soared 28%year to date and climbed 14.1% over the past 52 weeks, putting its recent performance well ahead of CASY.
Despite Casey's weak performance, analysts are cautiously optimistic about its prospects. CASY has an overall “Moderate Buy” rating from the 19 analysts covering it, and the mean price target of $825.89 represents a premium of 37.9% to current levels.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.