


TransAlta (TSX:TA) Gets A DOE Reprieve, Is The Current Price Fair?
TransAlta (TSX:TA) is back in focus after the United States Department of Energy ordered its Centralia Unit 2 in Washington State to remain available for operation for three months, through December 12, 2026.
Recent trading tells a mixed story. TransAlta’s share price has slipped over the past quarter, with a 90 day share price return of 15% in the red, even though the three year total shareholder return of 48.30% points to much stronger longer term momentum.
Scan how TransAlta compares across the wider utilities space by running your own checks against a curated list of 39 power grid technology and infrastructure stocks.
TransAlta’s pullback could be read as a verdict on its fundamentals or just a swing in sentiment after a strong three year run. Which story does the current valuation actually tell?
Most Popular Narrative: 3% Overvalued
Against a last close of CA$16.64, the most followed narrative pegs TransAlta’s fair value at CA$16.21, a small gap that still rests on some very specific earnings assumptions.
The assumed bearish price target for TransAlta is CA$16.21, which represents up to two standard deviations below the consensus price target of CA$23.91. This valuation is based on what can be assumed as the expectations of TransAlta's future earnings growth, profit margins and other risk factors from analysts on the more bearish end of the spectrum.
See why 1 investors see TransAlta as 3% overvalued.
Result: Fair Value of CA$16.21 (OVERVALUED)
Still, if electricity demand tightens or TransAlta secures a higher share of contracted revenue, the bearish valuation story could start to look conservative.
Find out about the key risks to this TransAlta narrative.
Another View On TransAlta’s Valuation
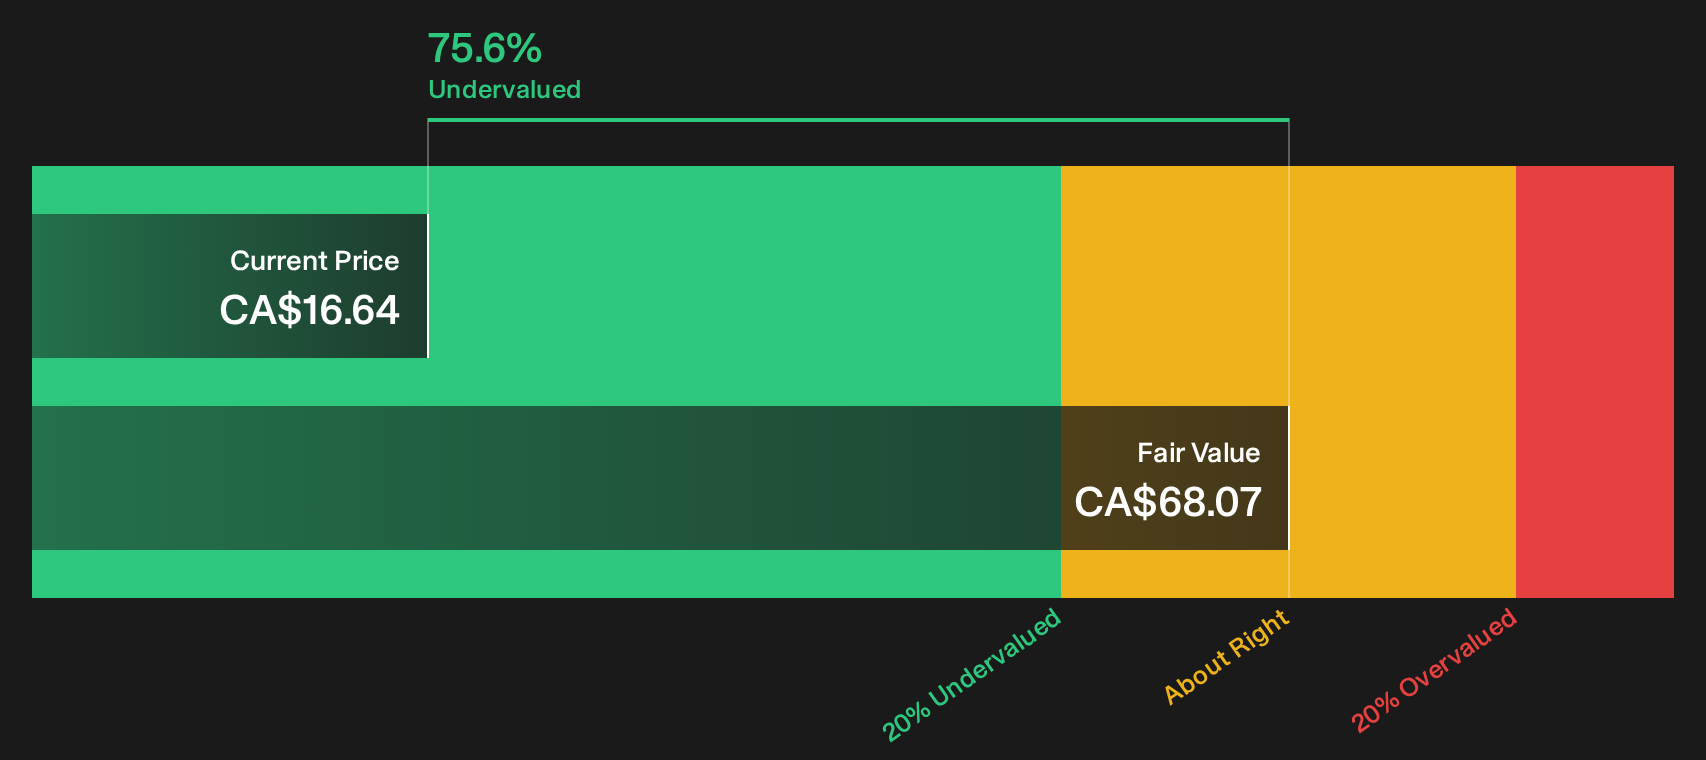
That bearish fair value of CA$16.21 contrasts sharply with our DCF model, which estimates TransAlta’s future cash flow value at CA$68.07 per share. The DCF view frames the current CA$16.64 price as deeply discounted. Which version of “fair” feels closer to your own expectations?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on TransAlta can leave the story feeling unclear. Review the cash flow, risks and upside yourself, then weigh the 3 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond TransAlta?
If TransAlta has sharpened your focus on valuation, broaden your watchlist with other ideas that match different goals and risk levels using the Simply Wall Street Screener.
- Target potential upside by scanning a curated pool of quality opportunities through the 5 high quality undervalued stocks that pass cash flow and balance sheet filters.
- Prioritise resilience and sleep-at-night confidence by tracking companies in the 8 resilient stocks with low risk scores that score well on financial health and volatility checks.
- Hunt for less crowded opportunities by reviewing the 9 high quality undiscovered gems where fundamentals look solid but attention from the wider market remains limited.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com