


Entra (OB:ENTRA) Stock May Still Have Room To Run On Sales
Entra has seen its share price move around in recent years, and the latest leg of that journey puts a sharper spotlight on what investors are really paying for its sales. With the stock recently closing at NOK 99.20, the open question is how well that price lines up with the revenue power of the underlying property portfolio.
- Over the past 5 years the share price has fallen 41.4%, which raises a clear question about how the current market value lines up against the sales Entra generates today.
- The business is heavily tied to income from leased properties, so expectations for rental levels, occupancy and long term contract quality may support or constrain what investors are willing to pay for each krone of revenue.
- The analysts covering Entra have run their own numbers. See what analysts think Entra's shares could be worth.
The issue now is whether Entra's current share price is adequately supported by its sales when set against the Fair Ratio benchmark.
If you are weighing Entra against other valuation stories tied to sales, it can help to compare it with a wider group of 180 high quality undervalued stocks.
Is Entra Still Cheap on Sales?
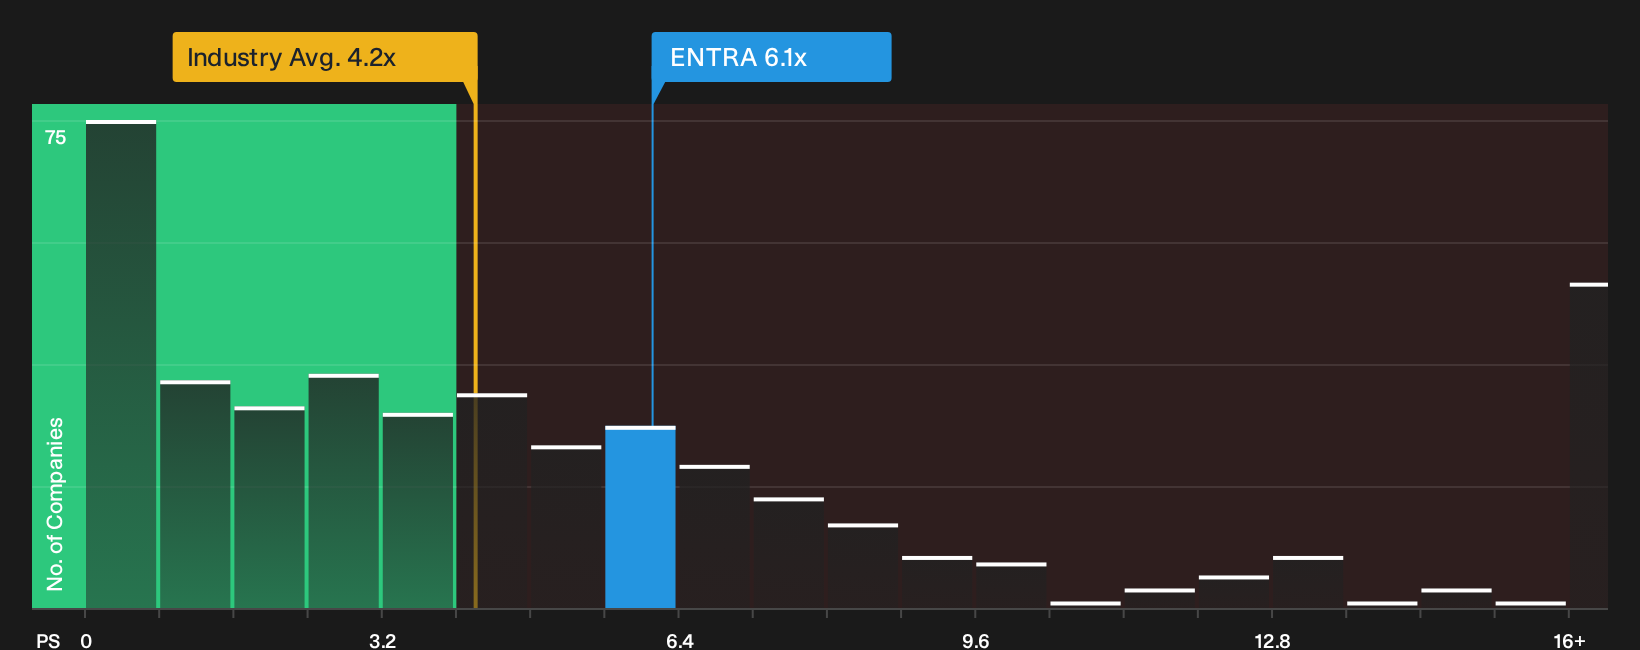
The P/S ratio works reasonably well for Entra because the business is built on relatively steady rental income rather than volatile one off sales. On this metric, the stock trades on a P/S of about 6.1x, which sits well above the broader real estate industry average of roughly 2.8x and also above the peer group level of around 4.1x.
The Fair Ratio model, which looks at Entra through its own mix of growth profile, margins, size and risk, points to a higher P/S than where the shares change hands today. That gap means the current valuation screens as undervalued on this lens, even though Entra already carries a premium to the wider sector and similar companies on simple sales multiples. Explore the numbers behind Entra's P/S valuation.
The Entra Narrative: What Would Justify Today's Price?
Narratives on Entra pick up where the valuation puzzle leaves off by spelling out which future paths for growth, profitability and earnings would need to play out for the stock to look meaningfully higher or lower than today’s price. Each storyline ties its number to a specific view on how Entra's growth, margins and risks could evolve, giving you something concrete to revisit as fresh information emerges.
Community views on Entra split between those who see enough lease momentum to support the current tag and those who think required returns still bite into the upside.
Bull case: roughly fairly valued
"Tightening green building requirements and tenant preferences for sustainable, energy-efficient offices position Entra's green-certified buildings to achieve rental premiums and support portfolio value uplift."
Discover why this Narrative puts Entra at roughly fairly valued.
Bear case: 10% overvalued
"Concentration of assets around central transport hubs in Oslo and Bergen exposes Entra disproportionately to structurally weaker office demand in these cores if public and private tenants continue downsizing and adopting flexible seating."
Explore why this Narrative puts Entra at 10% overvalued.
Entra’s price is only part of the story
Numbers tell you what Entra is worth today, but the people guiding the portfolio and the way their pay packets are designed can heavily influence what happens next. See who runs Entra and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com