


Nutanix (NTNX) Could Be 16% Overvalued As Ryax Deal Fuels AI Debate
Nutanix (NTNX) has expanded its artificial intelligence reach by acquiring France based Ryax Technologies, a specialist in GPU utilization and smart scheduling for complex workloads across hybrid cloud setups.
Recent trading tells a mixed story for Nutanix. The share price is around $68.59 after a 90 day share price return of 37.95% and a 3 year total shareholder return of 96.53%. In contrast, the 1 year total shareholder return has declined 10.29% as investors reassess both growth potential and execution risk around moves like the Ryax deal, the ongoing buyback program and recent leadership changes.
Scan Nutanix’s AI push against other potential breakouts by comparing it with 84 AI infrastructure stocks in the same space.
Bulls see Nutanix using Ryax to turn its AI platform into a higher value engine. Bears point to leadership turnover and a weaker 1 year return. Which story fits the current valuation work that follows?
Most Popular Narrative: 16.3% Overvalued
The most followed valuation storyline currently places Nutanix fair value at $58.98, below the last close of $68.59. This sets up a debate about how much of the AI and hybrid cloud promise is already reflected in the price.
Accelerating adoption of hybrid and multi-cloud architectures, highlighted by new integrations with Google Cloud and deepening partnerships with AWS, Azure, Dell, and Pure Storage, positions Nutanix to capture a broader share of enterprise infrastructure modernization budgets, expanding its addressable market and driving sustained revenue growth.
Ongoing enterprise digital transformation and demand for scalable solutions, as evidenced by large multi-year deals, major wins like Finanz Informatik, and increasing contributions from Global 2000 customers, provide a robust pipeline for future "land and expand" motions, improving both revenue visibility and opportunities for net new ARR expansion.
See why 37 investors see Nutanix as 16% overvalued.
The narrative applies an 8.64% discount rate and implies that at $58.98 Nutanix would be priced in line with projected earnings power and risk. The current $68.59 quote embeds a richer view on how AI, VMware migration tailwinds and subscription economics will play out over the coming years.
For readers, the key question is whether those assumptions around future contracts, margins and competitive pressures feel conservative, aggressive, or about right compared with your own expectations for Nutanix.
Result: Fair Value of $58.98 (OVERVALUED)
Still, the story can break if enterprise workloads tilt more heavily toward hyperscale public clouds or if rising operating costs continue to pressure Nutanix margin expectations.
Find out about the key risks to this Nutanix narrative.
Another View: Nutanix Through The Earnings Multiple Lens
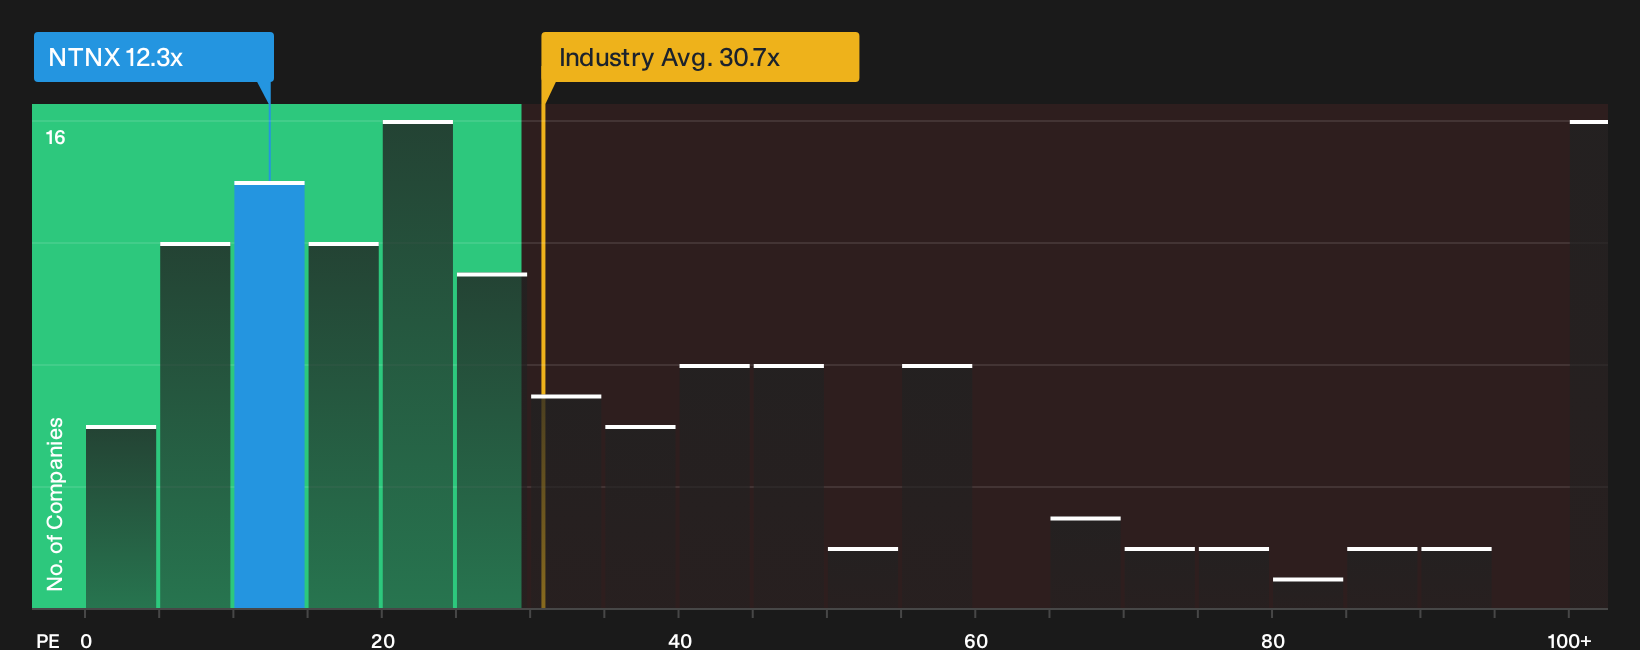
Nutanix looks expensive against its own fair ratio yet cheaper than many peers. The stock trades on a P/E of 12.3x. The fair ratio sits at 10.1x. US Software peers average 30.7x. That gap hints at both downside risk if sentiment cools and upside if investors migrate it closer to peers.
For a closer look at how these numbers line up against the current share price, read through See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Nutanix valuation and sentiment can be useful, but the real edge comes from pressure testing the numbers yourself and moving early once you have conviction. To frame both the upside and the potential downside before you act, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more Nutanix sized investment ideas?
Do not stop your research with Nutanix. Fresh ideas often come from comparing what you know well with high quality opportunities you have not reviewed yet.
- Target quality at a reasonable entry by scanning a curated 30 high quality undervalued stocks that filters for strong fundamentals with prices that look more forgiving.
- Prioritise resilience and sleep better at night by focusing on a 30 resilient stocks with low risk scores that screens for robust balance sheets and lower risk profiles.
- Spot early potential before the crowd catches on by checking a 16 high quality undiscovered gems that highlights underfollowed companies with solid financial traits.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com