


Datadog (DDOG) Climbed, So What Is Driving Attention Now?
Datadog (DDOG) climbed while major indices slipped, as traders reacted to the stock’s strength ahead of an upcoming earnings release that is expected to show higher year-over-year EPS and revenue.
That single session jump sits on top of a powerful run for Datadog, with a 7-day share price return of 8.86%, a 30-day gain of 15.22% and a year-to-date share price return of 92.06%. The 1-year total shareholder return of 88.08% and 3-year total shareholder return of 188.80% point to momentum that traders are now reassessing ahead of earnings.
Scan how Datadog’s momentum compares with other fast-moving software names by reviewing our hand picked list of 84 AI infrastructure stocks.
After a 92.06% year-to-date run and a US$256.92 share price, Datadog now trades only 11% below the average analyst target, yet about 18% above one intrinsic value estimate. So where does fair value really sit in that spread?
Most Popular Narrative: 10% Undervalued
Datadog’s most followed narrative pegs fair value at about $285 per share, which sits above the latest $256.92 close and places the current optimism in the context of cash flow and risk assumptions.
The main thing that has to go right is that Datadog continues to convert complex AI and cloud workloads into deeper multi-product usage while managing concentration in very large customers.
The current valuation suggests that the share price already reflects concerns about guidance, insider selling and customer concentration, while the business reports high gross margins and rising multi-product adoption.
See why 166 investors see Datadog as 10% undervalued.
Result: Fair Value of $285.28 (UNDERVALUED)
Still, Datadog’s story can change quickly if the largest customers keep trimming usage or if guidance keeps landing below what investors have pencilled in.
Find out about the key risks to this Datadog narrative.
Another View: What Multiples Say About Datadog
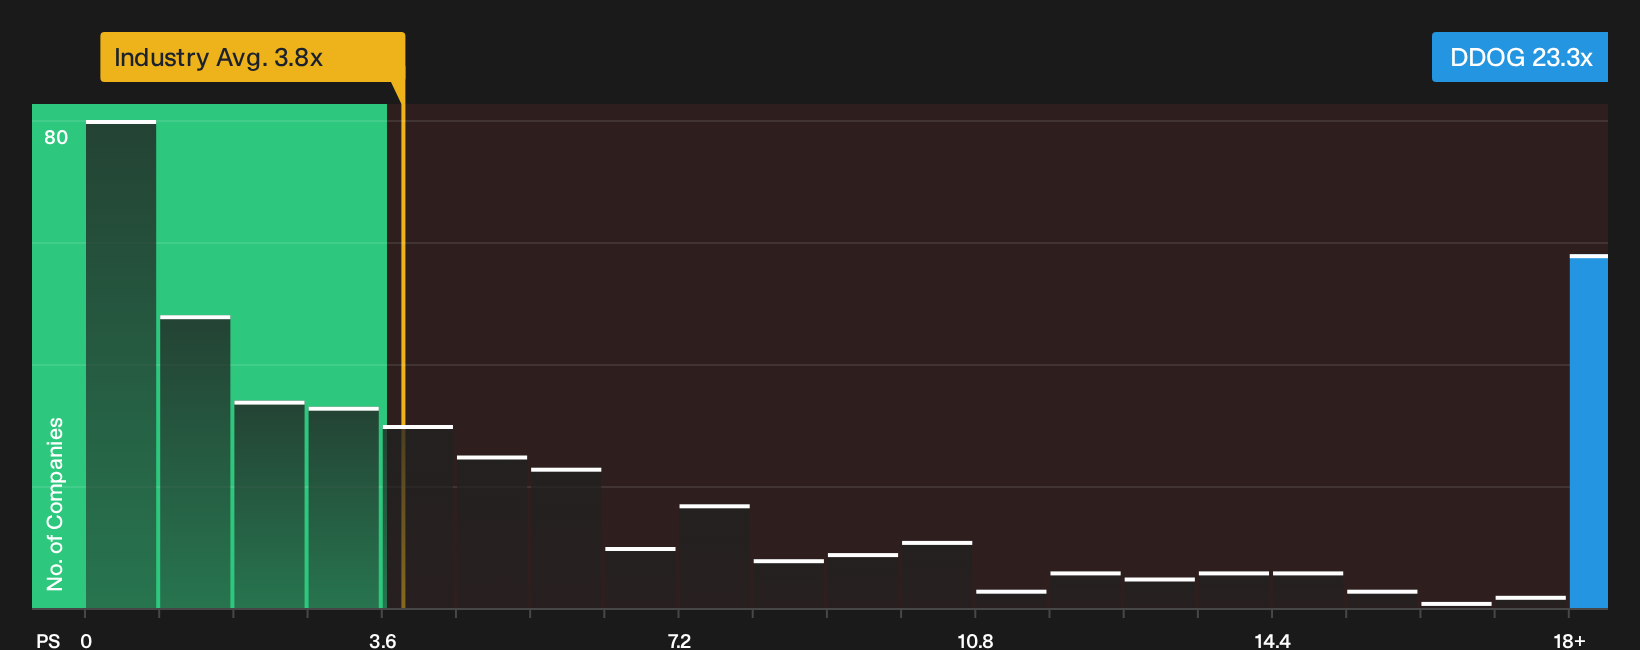
There is a very different message if you look at Datadog through simple trading ratios instead of fair value estimates. The stock changes hands at a P/S of 23.3x, compared with 3.8x for the wider US Software group and 7.7x for peers, while the fair ratio sits at 15.2x.
That gap points to investors already paying a heavy premium for Datadog, which can amplify downside if sentiment cools faster than the business delivers. It raises a simple question: Is that kind of mark up a risk you are comfortable carrying through the next earnings cycle or not?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between Datadog’s premium pricing and its fair value story is normal. Move quickly, review the underlying numbers, and weigh both the risks and the upside captured in 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Datadog?
Do not park all your attention on Datadog. Use the Simply Wall Street Screener to spot other opportunities that match your risk appetite and income goals.
- Target potential mispricing by scanning a curated selection of 30 high quality undervalued stocks that pair strong fundamentals with room for sentiment to catch up.
- Strengthen capital preservation by reviewing a focused 30 resilient stocks with low risk scores that may help steady your portfolio when volatility picks up.
- Boost income potential by tracking a hand picked 8 dividend fortresses that combines higher yields with robust payout support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com