


Sinda (SIND) Stock Could Be Overvalued As Drilling Progress Draws Focus
Sinda has given investors a choppy ride recently, with the share price moving sharply while fresh drilling results and index inclusion news keep attention on its mining plans. That mix raises a simple question for anyone looking at the ticker today: whether the current market value lines up with what Sinda’s balance sheet and book value suggest.
- Over the past month the stock has fallen about 21.9%. That puts the recent drop in sharp focus against what the underlying net assets might support.
- The company’s highest grade intercept to date at the Caracol area and ongoing work to open an exploration decline may support expectations for future resource conversion and could influence how much weight investors put on book value relative to potential project build out costs.
- There is a second opinion on Sinda worth weighing. See what analysts think Sinda's shares could be worth.
The stock’s next move may depend on whether that recent share price still makes sense when set against Sinda’s book value compared with the industry average.
If you are weighing Sinda against other miners on balance sheet strength and project potential, it can help to line it up beside solid balance sheet and fundamentals stocks screener (24 results).
Has Sinda Run Too Far on Book Value?
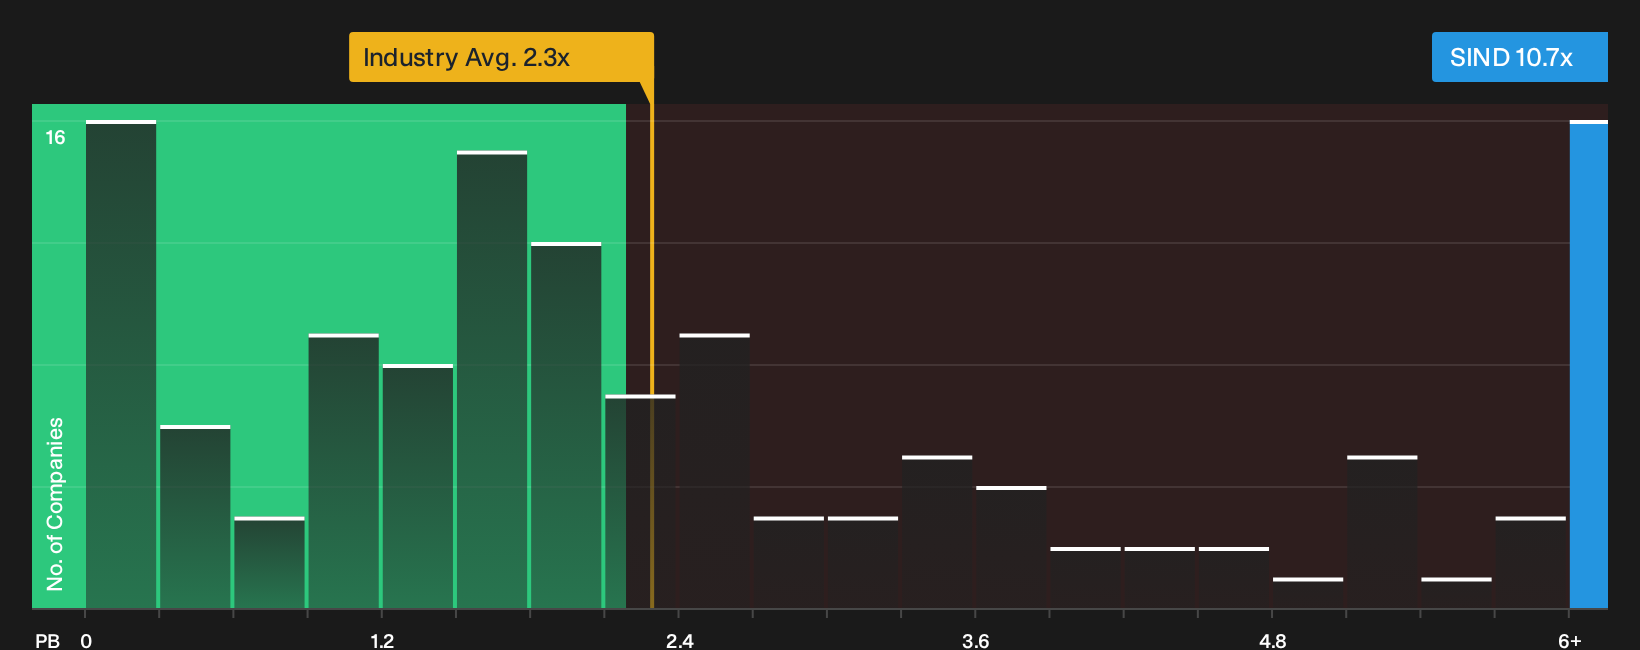
P/B is a cleaner yardstick for Sinda because the business is still loss making and free cash flow forecasts are negative, so earnings based ratios are harder to interpret. On this measure, Sinda trades at about 10.7x book value compared with a Metals and Mining industry average of roughly 2.3x and a peer group around 4.6x. That is a steep premium to both the wider sector and closer comparables, which signals that the current share price embeds a lot of optimism about future project execution and asset quality.
Inclusion in the VanEck Junior Gold Miners ETF has raised Sinda’s profile, yet the 10.7x P/B still screens as overvalued against the sector yardstick, and the gap is large enough that the model output looks more like a warning flag than a precise target. For anyone weighing the recent Caracol drill results and exploration decline plans, the key question is whether those development ambitions justify paying more than 4x the industry’s book based multiple for this stock. Explore the numbers behind Sinda's P/B valuation.
The Sinda Narrative: What Would Justify Today's Price?
Sinda’s Simply Wall St Narratives pick up where the valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the share price to end up meaningfully higher or lower than it is today. Each scenario ties a fair value to a specific set of possible catalysts and risks for Sinda, so you can watch over time which version of the story appears to be unfolding.
A written, number driven Narrative on Sinda gives you a clear way to test whether the current price lines up with the assumptions you are making about the Caracol drilling progress and the planned exploration decline. It also creates a reference point that can be revisited as the GDXJ inclusion, project work and future results either support or challenge those expectations over time.
Share your own Narrative for Sinda and set out the assumptions behind your valuation.
Before acting on Sinda's valuation, there is one more angle to check
Sinda’s pricing story is only half of the picture. Recent research has also flagged specific risk checks that may matter just as much to your decision. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com