


CrowdStrike (CRWD) Stock Looks Stretched Against Its Sales Outlook
CrowdStrike Holdings has been one of the stronger performers in large-cap cybersecurity, and the recent surge leaves a simple question for you as an investor: Is the current share price still grounded in what the business is generating in sales today and what the market expects that revenue line to do next?
- Over the past 3 years, CrowdStrike stock has delivered a very large gain of about 528.6%, which puts a lot of pressure on its sales-based valuation to justify how far the market has moved.
- Fresh headlines around AI driven security offerings, industry alliances, and partnerships with other vendors may support expectations for stronger future revenue, which feeds directly into how much investors are willing to pay for each dollar of current sales.
- Your read on CrowdStrike Holdings is one view; the desks covering it have another. See what analysts think CrowdStrike Holdings's shares could be worth.
The issue now is whether CrowdStrike's recent share price around US$259.67 is appropriately aligned with its sales when judged against the Fair Ratio benchmark.
If you are considering whether CrowdStrike Holdings at US$259.67 is aligned with its sales, a focused screen of other AI related security plays can help provide context through 36 AI small caps.
Has CrowdStrike Holdings Run Too Far on Sales?
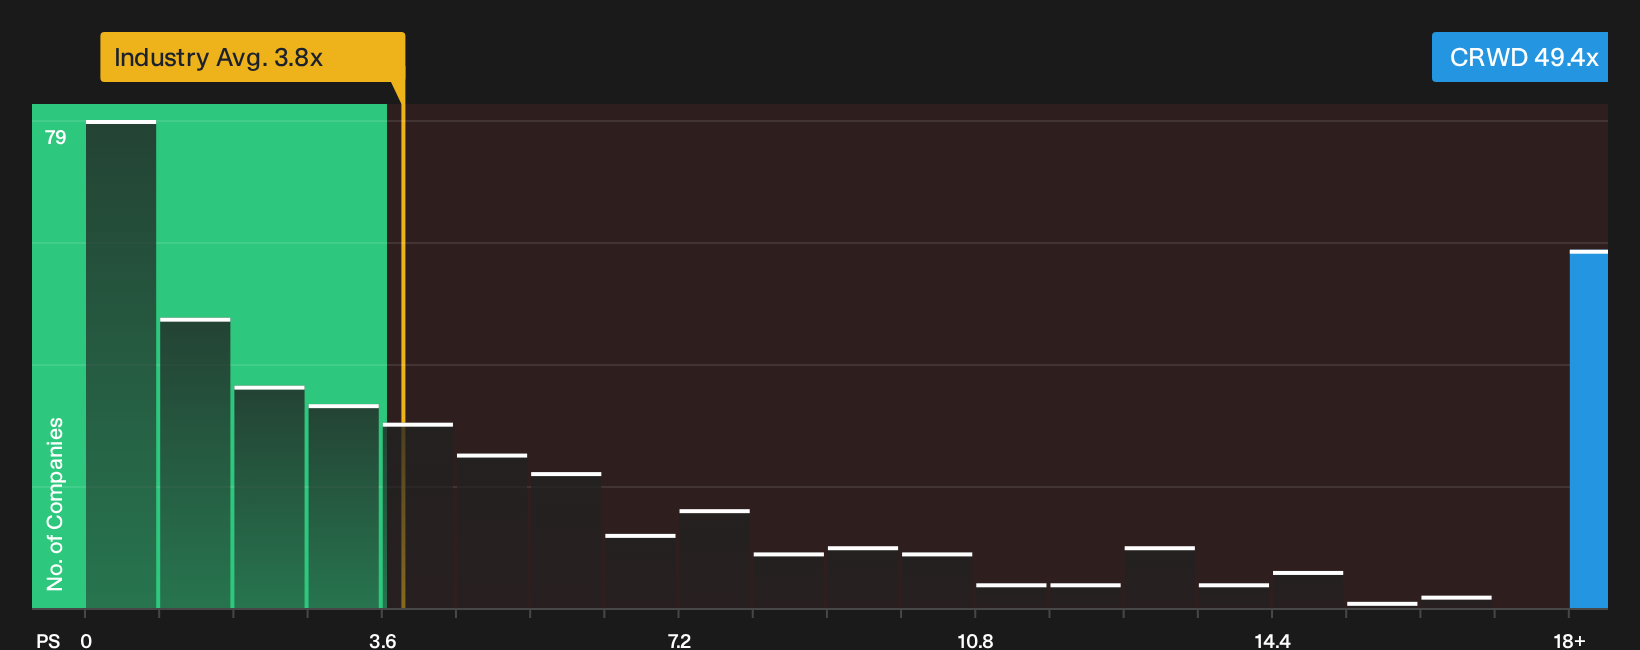
P/S works well for CrowdStrike Holdings because investors often focus on its ability to turn cybersecurity demand into recurring subscription revenue. On this measure, the stock trades on a P/S ratio of about 49.4x, compared with a Software industry average of roughly 3.8x and a peer group around 15.2x. That is a steep step up in how much the market is currently willing to pay for each dollar of CrowdStrike sales.
The Fair Ratio model, which blends factors like growth profile, margins, risk and size, flags that CrowdStrike’s current P/S sits above the level you might expect for the business and screens as overvalued on this framework. Recent enthusiasm around its AI driven security story, including alliance work such as the Blueprint Alliance, helps explain why investors are accepting such a premium to sector and peer benchmarks. However, it also raises the bar for what future execution has to justify. Explore the numbers behind CrowdStrike Holdings's P/S valuation.
The CrowdStrike Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CrowdStrike Holdings pick up where this valuation puzzle leaves you by explaining which paths for growth, profitability and earnings would need to occur for the stock to appear materially more expensive or cheaper than today’s price. Each narrative links its figures to a clear stance on how CrowdStrike Holdings' revenue trajectory, margin profile and key risks could evolve, giving you something specific to revisit as new information becomes available.
Community views on CrowdStrike Holdings are split between investors who see more upside left and others who think expectations already stretch the story.
Bull case: 12% undervalued
"The company's accelerating success in the Managed Security Service Provider channel, now over 15% of new bookings compared to single digits two years ago, is transforming CrowdStrike into an indispensable platform…"
Discover why this Narrative puts CrowdStrike Holdings at 12% undervalued.
Bear case: 34% overvalued
"Any failure to successfully execute the Falcon Flex subscription model, or to maintain high customer retention rates, could negatively affect the company's ARR growth and long term revenue projections…"
Explore why this Narrative puts CrowdStrike Holdings at 34% overvalued.
Before you decide on CrowdStrike Holdings, there is one more signal to check
Analyst projections give you a separate lens on where CrowdStrike Holdings might be a few years from now, and that set of expectations can either reinforce or challenge how you read today’s pricing. Explore where analysts expect CrowdStrike Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com