


Starbucks (SBUX) Weighs Japan Stake Sale And Cafe Remodels, Is It 17% Undervalued?
Starbucks (SBUX) is back in focus after reports it may sell a majority stake in Starbucks Japan, a business valued around US$3.0b, while also committing US$1b to remodel North American cafes.
Recent trading shows that momentum in Starbucks has softened, with the share price falling about 14% over the past month and roughly 10% over the past quarter. This comes even as the year-to-date share price return is 11.5% and the 1-year total shareholder return is 15.2%.
Scan how Starbucks stacks up against a hand-picked 30 high quality undervalued stocks that some investors may be watching for the next potential sentiment shift.
So is Starbucks now reflecting pressure on the underlying business, or has sentiment swung harder than the fundamentals justify as it weighs a Japan stake sale and invests US$1b into cafe remodels? The valuation work comes next.
Most Popular Narrative: 17% Undervalued
On the most widely followed view, Starbucks screens below an implied fair value of $112.23 compared with the last close of $93.65. This puts the current sell off against a backdrop of margin and cash flow work already in motion.
The Back to Starbucks plan, including Green Apron Service, standardized store scorecards, and a $2b cost-savings program through fiscal 2028, is still in progress and is expected to continue affecting operating margins and earnings as more of the targeted savings and process changes flow through the P&L.
See why 227 investors see Starbucks as 17% undervalued.
Result: Fair Value of $112.23 (UNDERVALUED)
Still, Starbucks faces real pressure points, including ongoing unionisation efforts and higher labor costs that could keep store level margins and earnings under strain.
Find out about the key risks to this Starbucks narrative.
Another View: Starbucks On Earnings Multiples
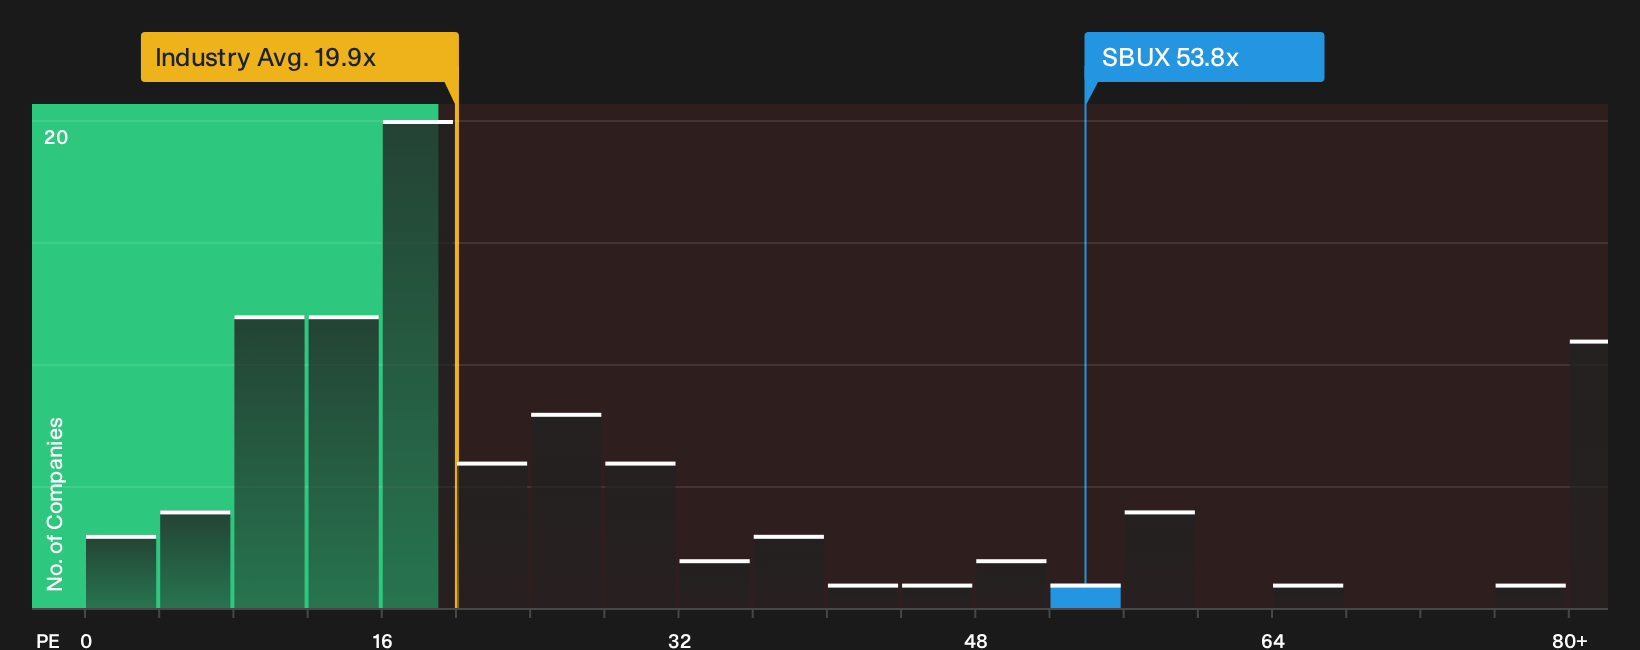
The earlier fair value of $112.23 presents Starbucks as undervalued, but the market’s own yardstick shows a tougher picture. At a P/E of 53.8x, the stock trades well above the US Hospitality industry on 19.9x, peers on 40.3x, and even a fair ratio of 34.6x that the market could move toward.
That gap points to valuation risk if earnings or sentiment weaken. The key question for investors is whether Starbucks can grow into this premium, or whether the multiple adjusts instead.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling the mixed message on Starbucks, with both pressure points and upside arguments in play. Move quickly to check the underlying numbers and decide where you land by reviewing the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Starbucks?
If Starbucks has you rethinking valuation and risk, do not stop at a single ticker. Use the screeners to widen your opportunity set intelligently.
- Target stability by scanning companies with resilient balance sheets and consistent fundamentals using this focused list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by running a fresh search across a curated 30 high quality undervalued stocks before the crowd catches on.
- Strengthen your income playbook by reviewing a curated field of 8 dividend fortresses that some investors watch for yield and resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com