


Paycom Software (PAYC) Rebounds On AI Narrative As Valuation Debate Heats Up
Paycom Software (PAYC) has drawn attention after recent trading left the stock about 4.7% lower over the past month, while it is still showing a gain over the past 3 months and year to date.
That recent 4.7% 30 day share price pullback comes after a sharp 70.9% 90 day share price return and a 44.9% year to date move. At the same time, the 1 year total shareholder return of 3.7% and 5 year total shareholder return decline of 54.2% suggest longer term investors have faced a bumpier ride, hinting that sentiment toward Paycom Software is improving in the short run after a tougher multi year stretch.
Compare Paycom Software's recent rebound with a curated 16 high quality undiscovered gems that have been quietly reshaping their trajectories away from the headlines.
Bulls point to Paycom Software's double digit recent gains and ongoing profitability. Bears focus on the steep 5 year drawdown. Which side do the current valuation markers lean toward as the dust settles on this rebound?
Most Popular Narrative: 46% Overvalued
Against a last close of $220.81 for Paycom Software, the most followed narrative framework pegs fair value at $151.44 using a 7.55% discount rate. This frames the recent rebound as stretching well beyond that intrinsic estimate.
Automation and AI-driven product innovation, combined with Paycom's unified single database architecture, are driving salesforce productivity gains, increased client satisfaction, and higher client retention rates, which should meaningfully strengthen long-term net margins and future earnings stability.
See why 84 investors see Paycom Software as 46% overvalued.
Result: Fair Value of $151.44 (OVERVALUED)
Still, the Paycom Software story carries real pressure points, including AI tools becoming commoditized and higher ongoing AI infrastructure spend weighing on profitability and cash generation.
Find out about the key risks to this Paycom Software narrative.
Another View: SWS DCF Points in the Opposite Direction
The analyst narrative frames Paycom Software as 46% overvalued against a fair value of $151.44. Our DCF model, which projects future cash flows and discounts them back at 7.55%, lands in a very different place. It suggests value of $462.24 per share, which is more than double the recent $220.81 price. When one framework sees excess optimism and the other flags a large valuation gap in the opposite direction, which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
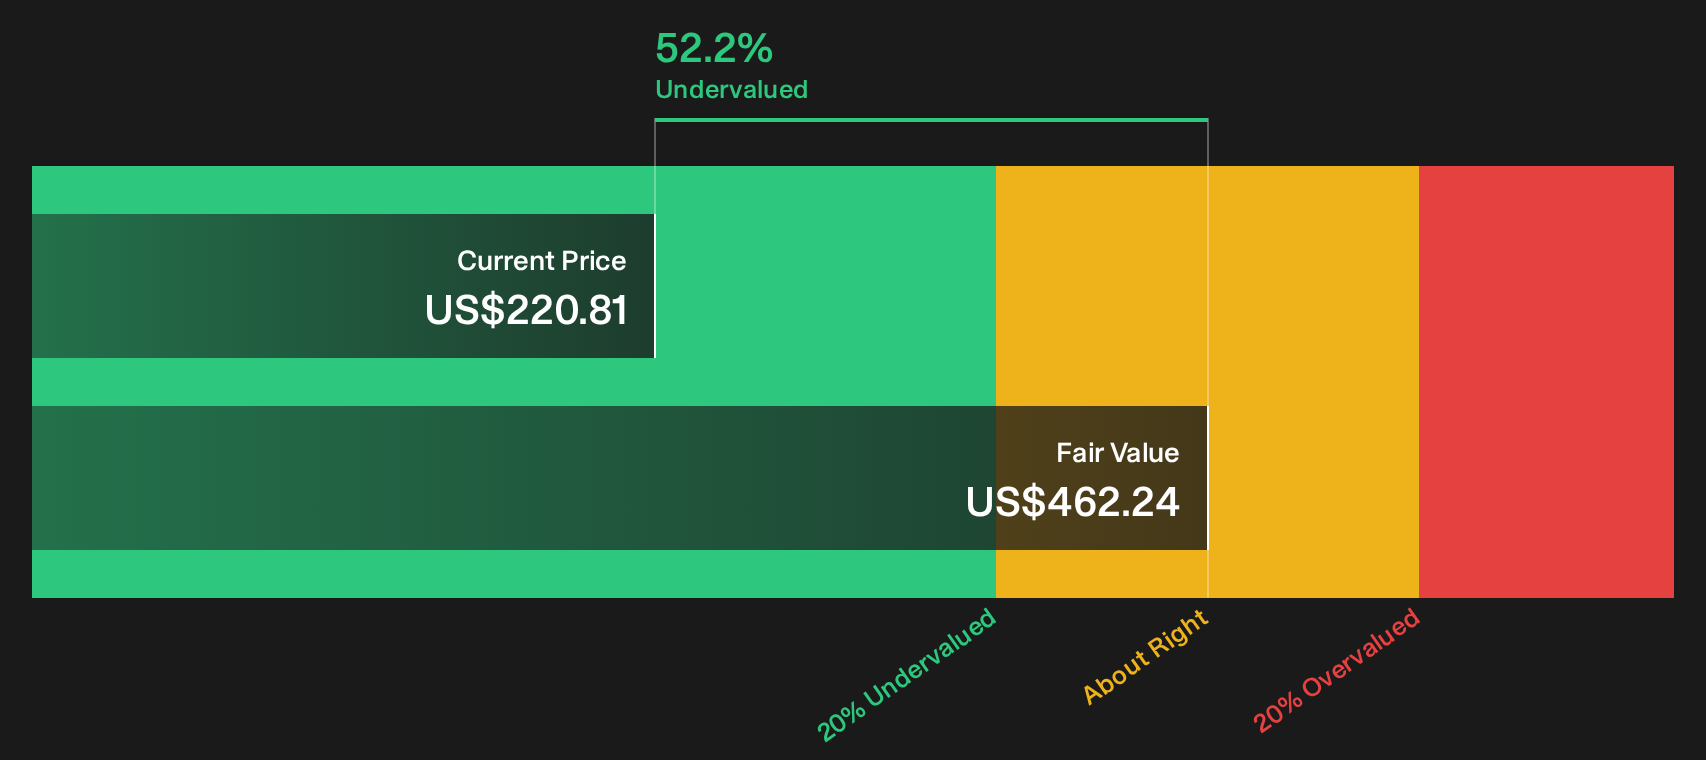
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paycom Software for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages around Paycom Software can feel like noise, so move quickly to review the full picture for yourself and weigh both sides. To see how the positives compare with the concerns, start with 3 key rewards and 2 important warning signs.
Ready for more ideas beyond Paycom Software?
If Paycom Software has you thinking more carefully about value and expectations, do not stop here. Broader context from other opportunities can sharpen every decision you make.
- Target resilient potential by scanning companies that score well on balance sheet strength and fundamentals through the list of solid balance sheet and fundamentals (24 results).
- Hunt for possible value gaps by assessing stocks with solid quality markers using the 30 high quality undervalued stocks.
- Secure potential income streams by reviewing steady payers that feature in the 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com