


Hecla Mining (HL) Just Gave Investors Something To Think About
Hecla Mining (HL) has secured a new Credit Agreement that gives the precious metals producer access to a US$500 million senior secured revolving credit facility, with an option to lift commitments by another US$100 million.
Recent trading in Hecla Mining has cooled, with the share price down 1.81% on the day, 5.38% over the past week and 14.24% across the last month. However, the 90 day share price return of 15.44% sits alongside a 1 year total shareholder return of 55.73% and a very large 3 year total shareholder return of about 4.7x. Momentum has therefore faded in the short term, but longer run holders have still seen strong gains.
Compare Hecla Mining’s new funding firepower with peers by scanning our hand picked list of 10 top silver producer stocks that may also be repositioning their balance sheets for the next phase of the cycle.
That mix of fresh credit headroom, softer recent trading and very strong multi year gains leaves Hecla Mining at an interesting crossroads. The key question for investors is whether the current price still compensates for the risks on the table.
Most Popular Narrative: 22% Undervalued
On the most followed narrative, Hecla Mining screens as undervalued, with a fair value estimate of $22.98 against the latest close of $17.94. This puts the new $500 million credit facility in the spotlight as investors weigh how that balance sheet flexibility lines up with longer term production and pricing assumptions.
Hecla is poised to benefit from accelerating demand for silver driven by ongoing global electrification and renewable energy growth, as silver is critical for EVs and solar panels. This positions the company for potential top-line revenue expansion and greater leverage to rising silver prices.
Elevated inflation and persistent macroeconomic uncertainty are fostering stronger investor demand for precious metals as safe havens. This can underpin higher realized silver prices and margin expansion for Hecla's silver-focused portfolio.
See why 62 investors see Hecla Mining as 22% undervalued.
The narrative uses a discount rate of 8.77% to bring those future cash flows and margins back to today, then compares that outcome to the current share price to frame the upside and risk trade off that holders are accepting at $17.94.
That approach leans heavily on expectations for the silver cycle, production delivery from assets such as Greens Creek, Lucky Friday and Keno Hill, and the view that Hecla Mining can sustain high quality earnings even as revenue is expected to decline each year in the current forecasts.
Result: Fair Value of $22.98 (UNDERVALUED)
Still, higher capital needs at Keno Hill and potential shareholder dilution from deleveraging plans could pressure cash flows and weaken the Hecla Mining upside story.
Find out about the key risks to this Hecla Mining narrative.
Another View: Hecla Mining Through The Earnings Lens
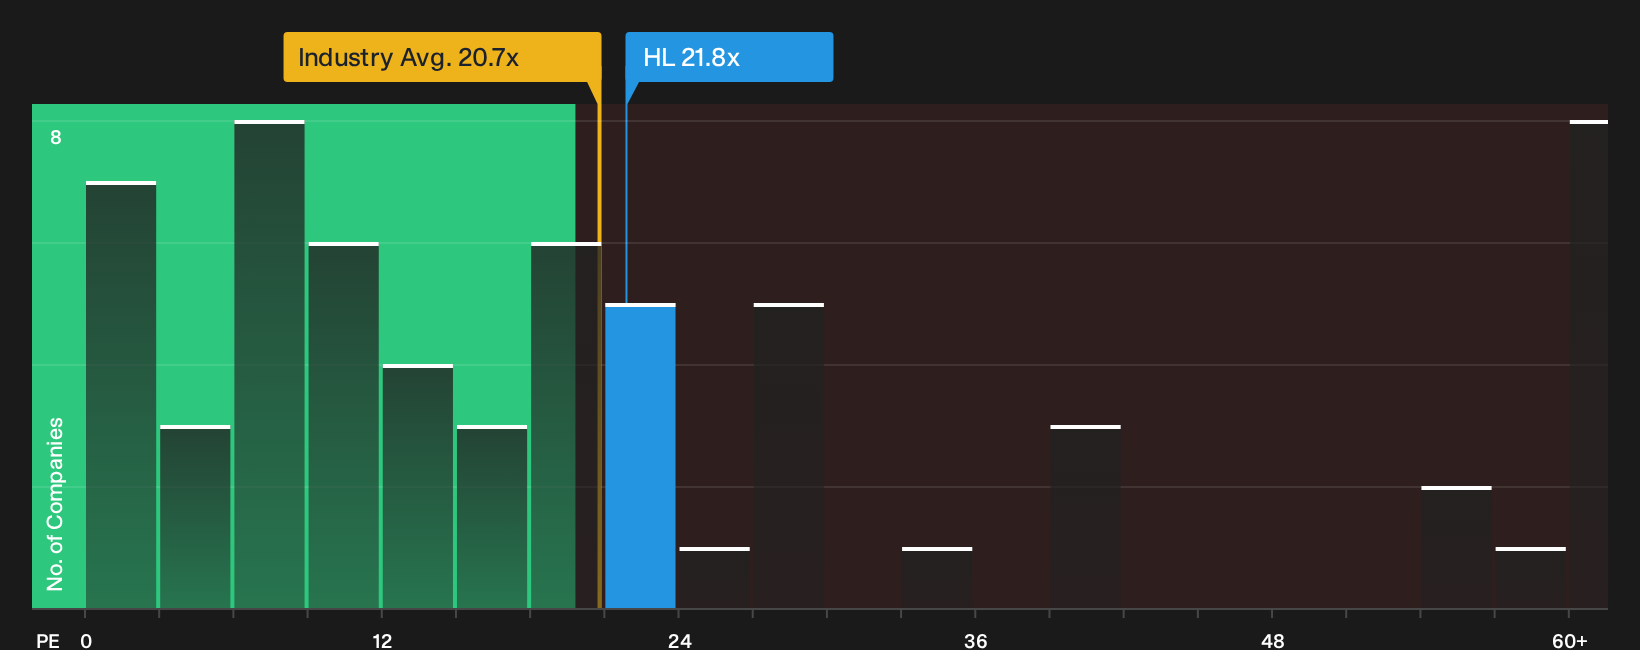
Hecla Mining looks cheap on that $22.98 fair value narrative, yet the current P/E of 21.8x tells a different story. The industry sits at 20.7x, and the fair ratio sits slightly lower again at 20.6x. That premium hints at less margin for error if the silver thesis softens.
For a deeper look at what this pricing gap could mean in practice, including how it aligns with earnings quality and sector peers, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the mix of optimism and caution around Hecla Mining match your own read of the story, or does it feel out of step with the numbers? Move quickly, and stress test the upside cases and pressure points yourself by reviewing the 2 key rewards.
Looking for more investment ideas beyond Hecla Mining?
If Hecla Mining has you thinking more broadly about where to put your next dollar to work, back that curiosity with a focused search using targeted screeners.
- Hunt for potential value opportunities that combine quality fundamentals with pricing that still looks reasonable by scanning our curated set of 30 high quality undervalued stocks.
- Zero in on companies that prioritize balance sheet strength so you are not relying solely on optimistic forecasts by reviewing a list of solid balance sheet and fundamentals (24 results).
- Spot opportunities that are not yet crowded and may still be flying under the radar by checking out our 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com