


Dianthus Therapeutics (DNTH) Files A Large Equity Offering, Is The Upside Already Priced In?
Why Dianthus Therapeutics is back in focus
Dianthus Therapeutics (DNTH) has put fresh fundraising plans on the table, filing an omnibus shelf registration and a follow on equity offering of up to US$500 million in common stock.
The move gives the biotech flexibility to issue common and preferred shares, debt, warrants, or units over time, alongside an at the market program that could steadily tap investor demand as funding needs arise.
Recent trading shows that momentum in Dianthus Therapeutics has cooled in the short term, with the share price down 19.09% over 30 days and 10.29% over the past week, even after a sharp year to date share price return of 128.60% and a 1 year total shareholder return of 153.10%. This leaves longer term holders sitting on very large 3 year gains as the fresh capital plans reset expectations around future funding and risk.
Compare Dianthus Therapeutics' capital raise with other biotech opportunities by scanning our hand picked 16 high quality undiscovered gems that may be flying under most investors radar.
Dianthus Therapeutics has added a US$500 million equity tap just after a sharp multi year rerating. The real puzzle now is whether most of the upside is already in the rearview mirror or not.
Most Popular Narrative: 49% Undervalued
The most followed narrative on Dianthus Therapeutics pegs fair value at about $178.42 per share, compared with the last close at $90.71. This sets up a wide gap between what that framework implies and where the stock currently trades.
The approximately US$1.2b cash balance and stated runway into 2030 allow Dianthus Therapeutics to run multiple late stage programs in parallel rather than in sequence. This can compress the timeline over which new indications and pipeline assets contribute and may influence the cadence of future earnings growth if programs succeed.
See why 0 investors see Dianthus Therapeutics as 49% undervalued.
Result: Fair Value of $178.42 (UNDERVALUED)
Still, the Dianthus Therapeutics story can break if rising R&D and administrative costs keep widening losses, or if future capital raises materially dilute existing holders.
Find out about the key risks to this Dianthus Therapeutics narrative.
Another View: Dianthus Therapeutics And The DCF Check
The bullish narrative around Dianthus Therapeutics points to a fair value of $178.42, yet the Simply Wall St DCF model points in the opposite direction. On that cash flow view, the stock trades above an estimated value of $32.24, which frames Dianthus as overvalued instead of undervalued.
Both methods look at the same business but through very different lenses, one anchored in long term earnings expectations and the other in modeled future cash flows. That gap raises a simple question for investors: Which lens feels closer to how you actually judge risk and potential payoff?
Look into how the SWS DCF model arrives at its fair value.
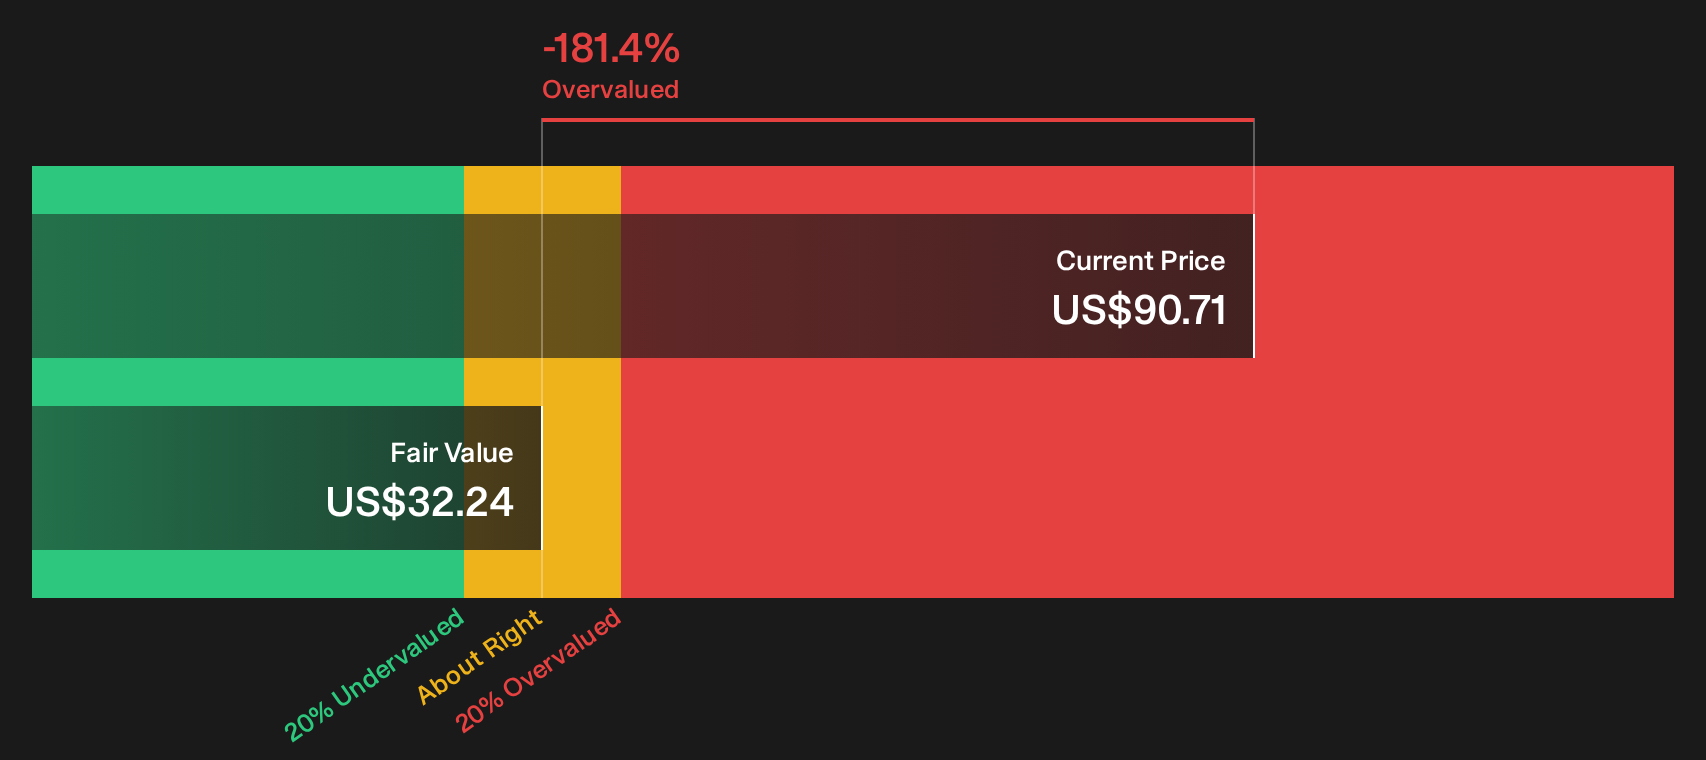
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Dianthus Therapeutics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 30 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the split sentiment around Dianthus Therapeutics leaves you torn, check the numbers yourself, move quickly, and weigh both sides of the story with 2 key rewards and 3 important warning signs.
Looking for more Dianthus Therapeutics style ideas?
If Dianthus Therapeutics has your attention, do not stop here. Cast the net wider with stock ideas that match your risk profile and return goals.
- Target potential mispricings by scanning a curated pool of companies that screen on quality and value via the 30 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (24 results) so you can focus on businesses that keep financial risk in check.
- Look for lesser known opportunities through a 16 high quality undiscovered gems before they sit on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com