


Can Synchrony Financial (SYF) Stay Reasonable After A 146% Run?
Synchrony Financial has seen its share price pull back in recent weeks after a strong multi year run, which puts fresh attention on whether the current US$71.55 level lines up with what its earnings can support. For investors watching the stock today, the key issue is whether that earnings profile still backs up where the market is pricing Synchrony Financial.
- Over the past 3 years the stock has delivered a total return of about 146.4%, which raises the question of how much of that gain is grounded in the business’s earning power versus changing sentiment.
- The new partnership that integrates Synchrony’s CareCredit product into Intelibly’s dental platform may support future fee and interest income from health focused lending, which can influence how durable the company’s earnings base looks.
- The analysts covering Synchrony Financial have run their own numbers. See what analysts think Synchrony Financial's shares could be worth.
The stock’s next move may depend on whether Synchrony Financial’s current price is adequately explained by what the company earns today and what those profits reasonably suggest for the future.
If you are considering Synchrony Financial after this pullback, it can be helpful to compare its earnings-driven story with other companies screened for 30 high quality undervalued stocks.
Is Synchrony Financial Still Cheap on Earnings?
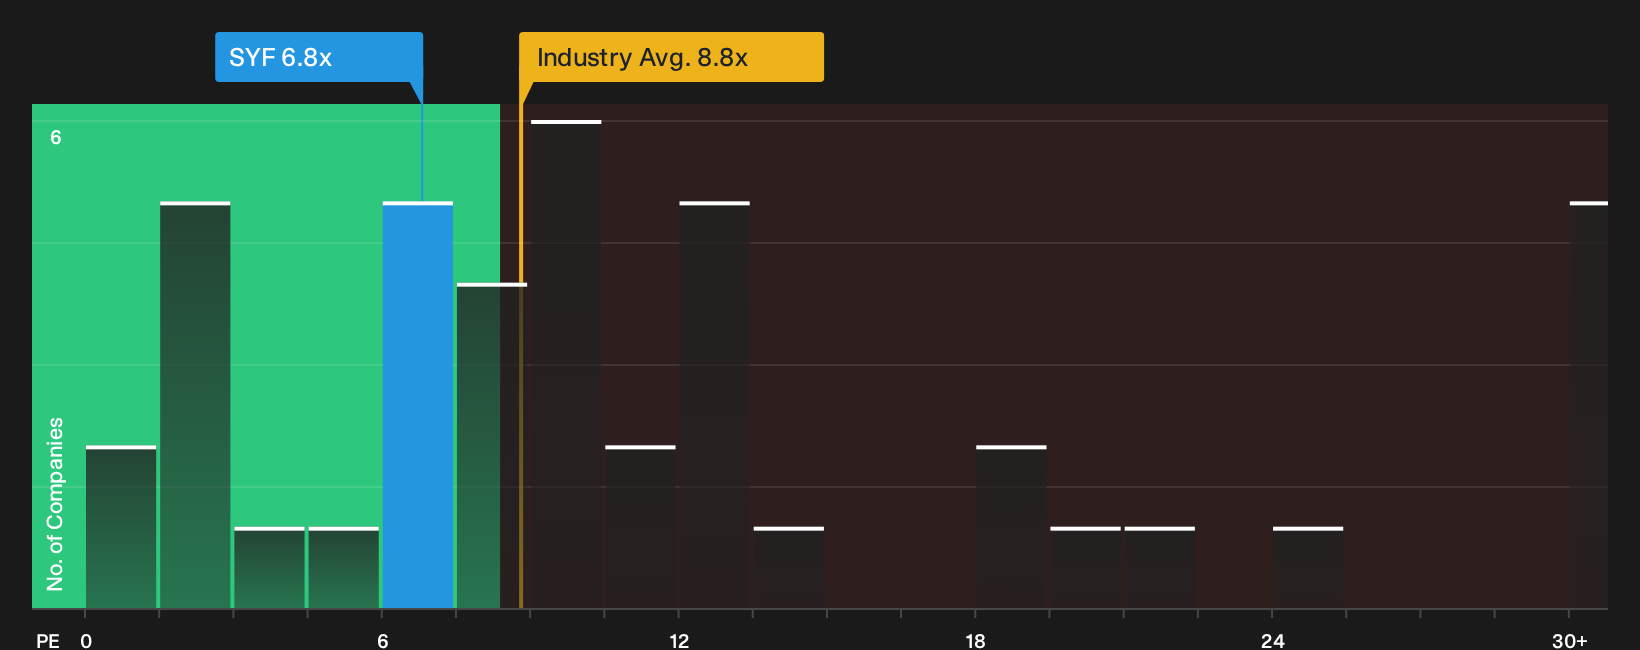
The P/E ratio is a useful lens for Synchrony Financial because earnings are a key driver for consumer lenders. On that measure, the stock trades on about 6.8x earnings, which is below the consumer finance industry average of roughly 8.8x and far below a peer group average near 18.6x. For a reader, that means the market is currently attaching a lower price tag to each dollar of Synchrony Financial’s profit than to many comparable businesses.
The tailored fair P/E multiple, which blends factors like expected profitability, sector profile and risk, sits above where the shares trade now, so the current 6.8x level aligns with an undervalued reading on this framework. Because the CareCredit integration into Intelibly’s dental platform is a specific new channel for health focused lending, the discount persists despite fresh product reach that could be relevant for the earnings base. To see how much headroom this model implies at the current share price, you can explore the full multiple breakdown and fair value estimates for Synchrony Financial. Explore the numbers behind Synchrony Financial's P/E valuation.
The Synchrony Financial Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the valuation puzzle leaves off and spell out what future growth, margins and earnings Synchrony Financial would need to justify a meaningfully higher or lower share price than today’s. Each one treats fair value as a thesis about how the business might play out over time, so you can watch that story either strengthen or weaken as new information comes through on the Community page.
One of the top community narratives on Synchrony Financial: 32% undervalued
"Your DCF/Excess Return analysis suggests Synchrony Financial’s intrinsic value is around $145 per share, meaning the stock could be trading at a steep discount..."
Discover why this Narrative puts Synchrony Financial at 32% undervalued.
One more Synchrony Financial check to weigh before you stop at the share price
Price and profit only tell part of the story for Synchrony Financial, because the research also flags specific concerns that can change how you view the whole risk profile. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com