


3 British Founder Led Stocks To Watch In September 2026
Global bond markets are under pressure, with long dated US Treasury yields at their highest level since 2004 and borrowing costs climbing in major economies. Higher rates can hit highly leveraged businesses hardest. Founder led British companies often look different. Leaders with large personal stakes tend to think in decades, not quarters. This article highlights three such stocks from our founder focused screener that may warrant closer attention.
The three founder led British stocks below are only a small sample, with the full screen surfacing 60 more businesses where owners are still in the driving seat and the story can be just as compelling.
If you want to identify which leaders and balance sheets best fit your own playbook, go straight to the Founder-Led Companies screener to filter and analyze the wider opportunity set.
Fevertree Drinks (AIM:FEVR)
Overview: Fevertree Drinks develops and sells premium Fever-Tree branded mixer drinks globally, with founders still closely shaping product direction and brand.
Operations: Fevertree Drinks generates £109.8 million in the United Kingdom, £102.3 million across Europe, £94.9 million in the United States, and £38.8 million in the Rest of the World.
Market Cap: £951.1 million
Fevertree Drinks matters for this founder led screen because the original creators still guide how the brand grows, prices, and expands worldwide.
"Fevertree's future revenue growth faces structural risk from shifting consumer behavior as increased health consciousness drives a long-term decline in both sugary and alcoholic beverage consumption, which may result in lasting volume contraction for mixers and threaten the company's ability to expand its total addressable market."
What happens to Fevertree Drinks if a single unseen pressure quietly reshapes how much pricing power the brand can keep?
That unseen pressure might also be masking upside, which is exactly what the full narrative for Fevertree Drinks sets out by weighing brand strength against those long term consumption risks.

Computacenter (LSE:CCC)
Overview: Computacenter provides founder-led managed IT services and device lifecycle support for large corporate and public sector clients across multiple regions.
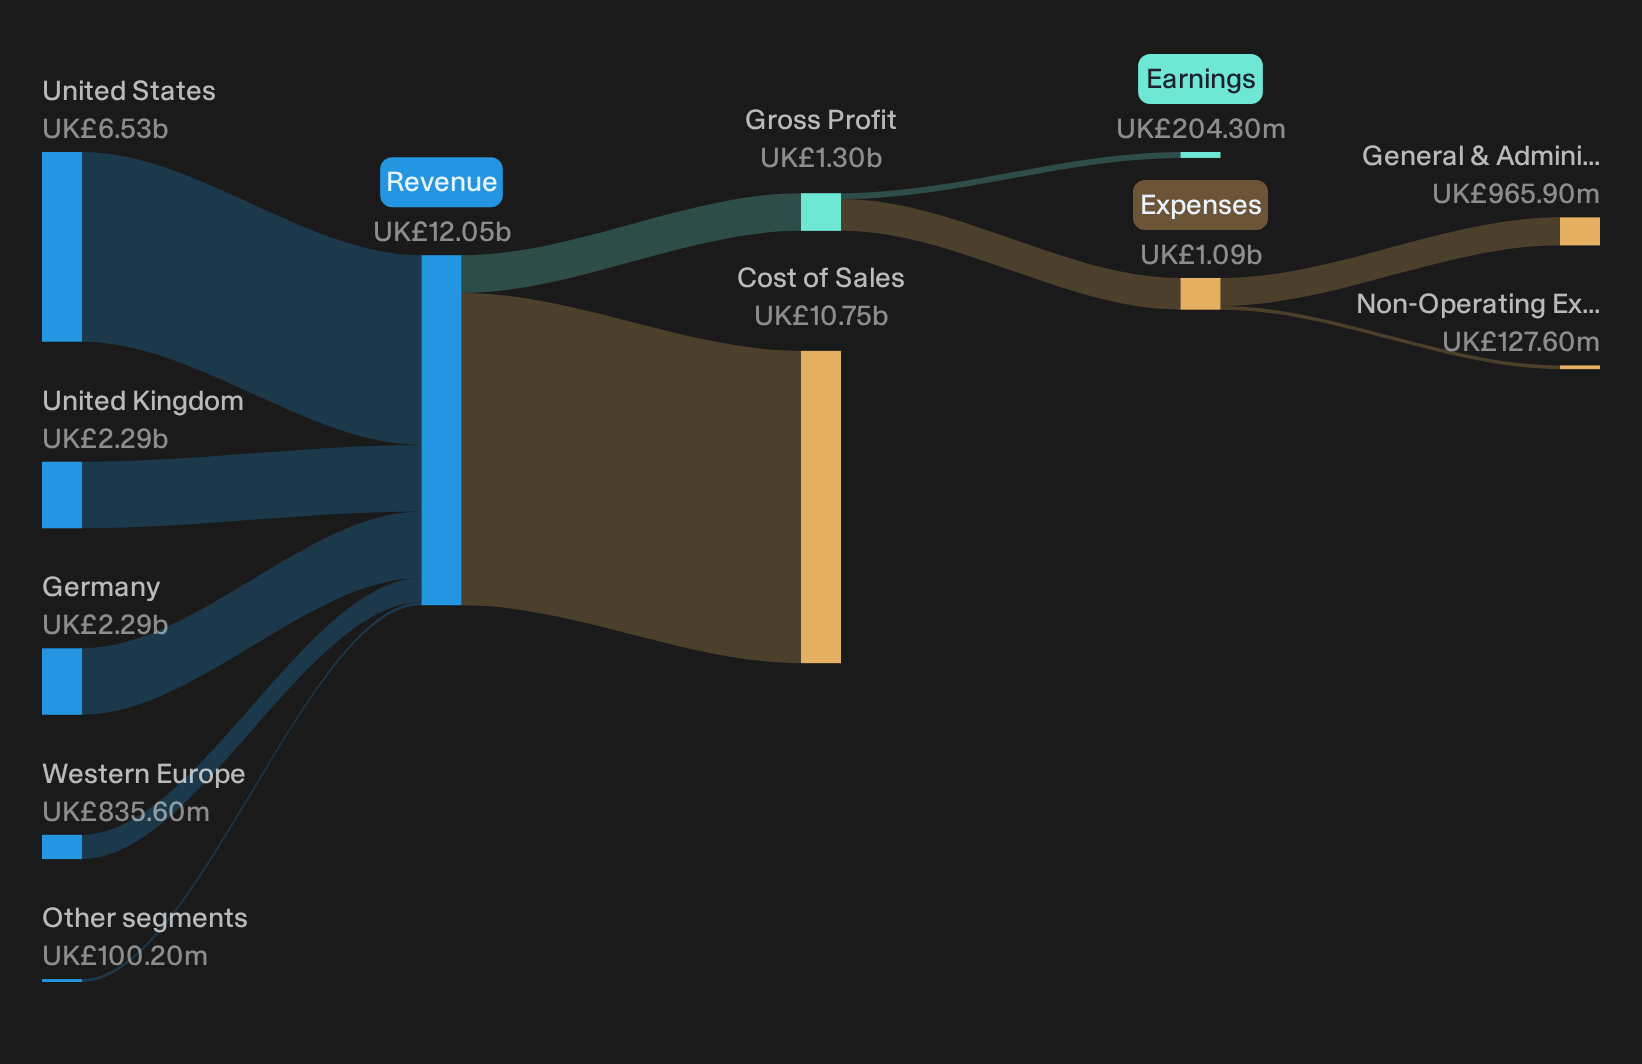
Operations: Computacenter generates £12.1b from Computer Services, with key markets including the United Kingdom, Germany, Western Europe and North America.
Market Cap: £5.8b
Computacenter appeals to founder-led investors because long-tenured leadership is tied directly to multi-year IT workplace contracts, high quality earnings and a 21.1% ROE. Strong first half 2026 results and a higher interim dividend suggest a management team that is focused on long-term performance. One unresolved funding reliance could still reshape how safely that growth compounds.
That funding question is exactly why the Computacenter financial health report can help you see how Computacenter’s balance sheet interacts with contracts, margins and future optionality.
Foresight Group Holdings (LSE:FSG)
Overview: Foresight Group Holdings is a London based infrastructure and private equity manager that funds and scales founder led and owner managed businesses.
Operations: Foresight Group Holdings generates £114.8 million from Real Assets and £50.1 million from Private Equity, with revenue mainly sourced in the United Kingdom and Australia.
Market Cap: £471 million
Foresight Group Holdings matters here because its private equity and venture capital arm is built around backing founders with capital, expertise and time, then sharing in the upside as those owner operators grow into much larger platforms.
"The combination of public-to-private acquisitions (such as Harmony Energy Income Trust), performance-driven fund launches, and ongoing buybacks (where buybacks are outpacing share-based dilution) is described as set to deliver compounding EPS growth and potentially higher dividend per share increases as capital is recycled into accretive, high-ROIC strategies and return of capital accelerates."
What happens to Foresight Group Holdings if a single assumption about how quickly fresh capital can be raised quietly shifts the margin story?
When that capital-raising assumption moves, the full narrative for Foresight Group Holdings lays out how Foresight Group Holdings could still accelerate value as distributions, buybacks and fee streams interact.

Seeking Fresh Alternatives Beyond These Founders
New themes are breaking out, momentum is building, and the most interesting ideas can get caught quickly once the crowd arrives. Scan these under the radar filters while it matters and aim to get in early.
- Target resilient income streams before yields get compressed by demand and use the 1 dividend fortresses to see which payers still combine strength with payout power.
- Spot early movers in automation before the story goes mainstream and review the 93 robotics and automation stocks that are already building the next wave of productivity winners.
- Track potential beneficiaries of the AI buildout while they are still flying below most radars and assess the 84 AI infrastructure stocks powering the data center backbone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com