


Upcoming Earnings Might Change The Case For Investing In monday.com Stock (MNDY)
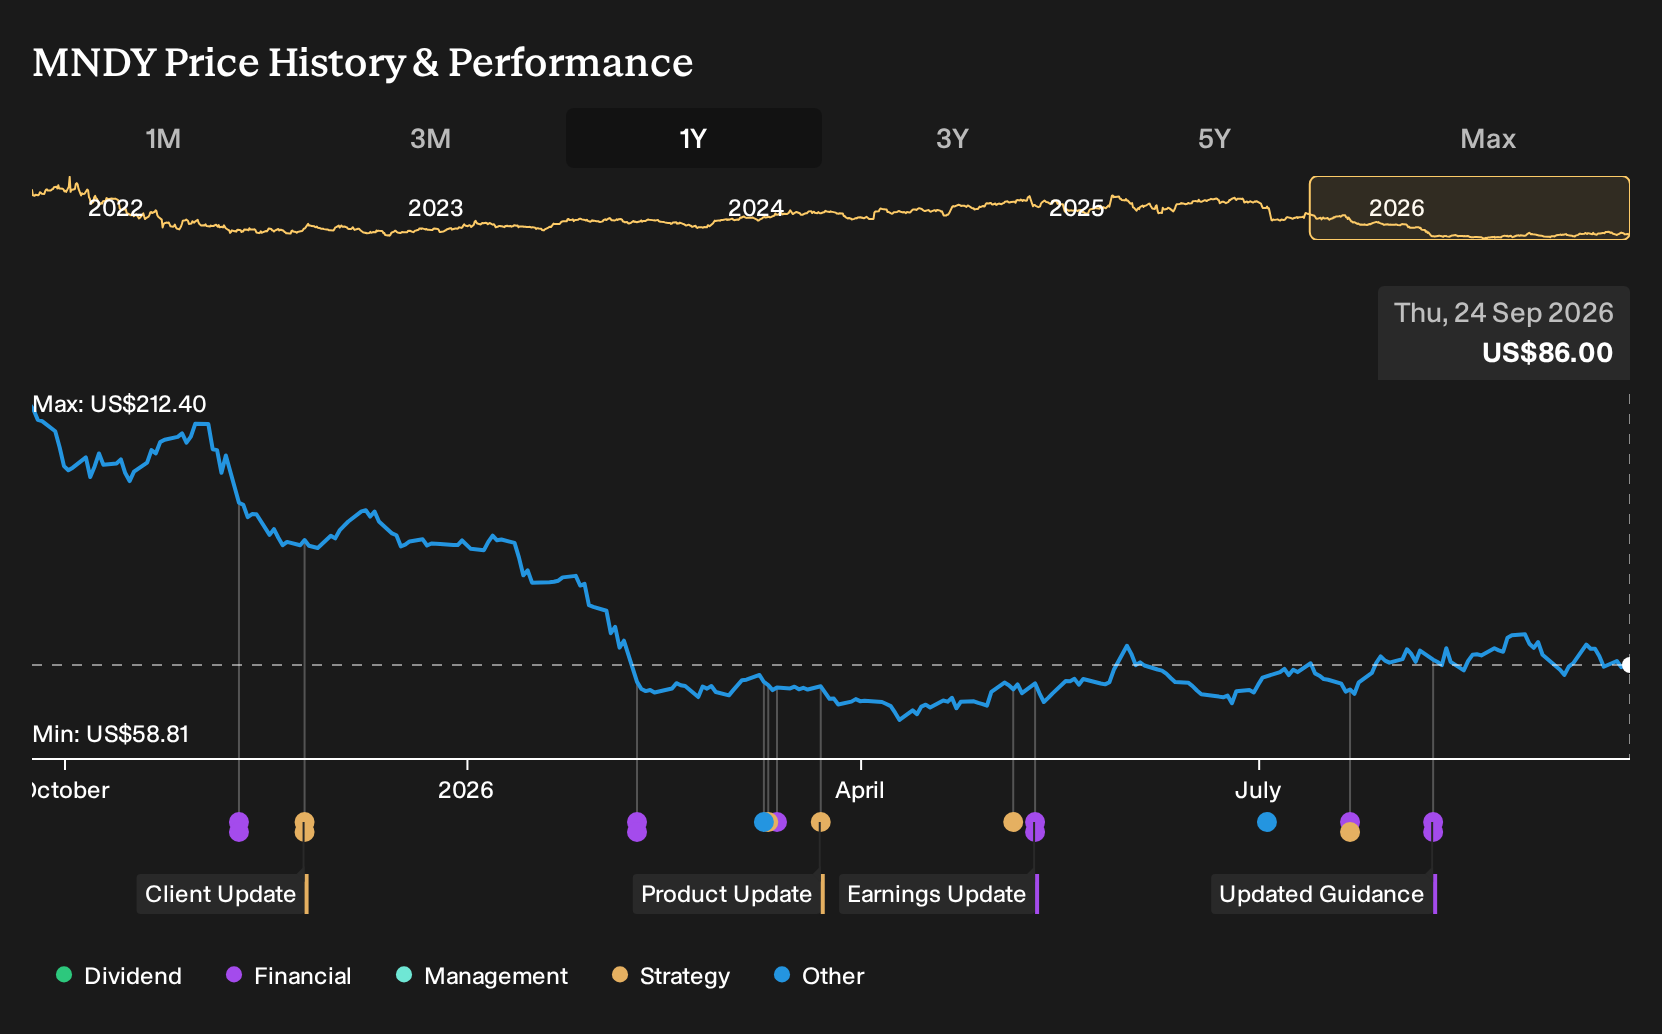
- monday.com recently closed at US$87.06, with investors focused on an upcoming earnings report where analysts project earnings per share growth of 19.83% year over year.
- The software platform currently trades at a lower forward P/E than its broader industry while carrying a top analyst ranking, which highlights how expectations for operational execution and cost discipline are shaping sentiment ahead of the results.
- We will look at how monday.com's long term investment narrative lines up with investor optimism around its upcoming earnings milestone.
Scan how monday.com compares with other fast growing software platforms by reviewing our hand picked list of 16 high quality undiscovered gems before the next earnings catalysts are released.
monday.com Investment Narrative Recap
To own monday.com, you need to believe its Work OS can keep winning budget inside teams that want flexible tools for projects, CRM, dev and service work on a single platform. The near term story is about execution. The upcoming earnings print and EPS outlook matter because they signal whether product adoption and pricing are holding up after a tough share price run.
The biggest swing factor right now is whether monday.com can keep growing larger customers and cross selling newer products while keeping cost growth in check. Reliance on performance marketing and some softness in smaller customers sit on the risk side. The latest share price move around US$87 does not change those underlying questions in a material way.
Recent attention has centered on the expected 19.83% year over year EPS gain in the upcoming report. That projected jump matters less on its own and more as a read on operating leverage after heavy spending on R&D and sales, plus headcount expansion. You are really watching whether monday.com is turning past investment into cleaner, repeatable profit.
There have been no fresh company specific announcements tied to this earnings setup, so the focus stays on existing trends. Those include prior commentary around generative AI features, multi product expansion across CRM and Service, and the push further into enterprise accounts. Together, these themes frame the key catalyst: proof that higher value use cases can offset risks from slower small business additions and rising competition in workflow software.
monday.com Earnings Setup Through the Analyst Lens
monday.com's current analyst narrative leans heavily on a few simple levers that you can track. Revenue is modeled to grow at 16.6% each year over the next three years. Profit margins are expected to compress from 9.2% today to 4.0% in roughly three years, which pushes the debate away from headline growth and toward the quality of that growth.
On earnings, the consensus view points to a move from US$119.4 million today to US$83.3 million by around 2029. That is a decline of about US$36.1 million in profit on these forecasts. Analysts are also assuming earnings per share of US$1.91 by that time, helped in part by an expected 6.85% annual reduction in share count over the next three years. For an investor, this mix of higher revenue, lower margins and fewer shares highlights how much depends on execution in larger accounts and on the cost base.
The same set of projections ties into how some on the Street are thinking about valuation. To line up with the consensus, you would need to accept that monday.com could be generating US$2.1b in revenue and US$83.3 million in earnings by 2029, and that the stock might trade on a P/E of 68.6x those earnings. That multiple is well above the current 25.7x attached to the business and above the 25.4x P/E quoted for the broader US software peer group in the report. The gap between those multiples is effectively the price of believing in the long term story.
monday.com's narrative projects revenue of about US$2.1b and earnings of US$83.3 million by 2029. This assumes 16.6% yearly revenue growth and an earnings decline of roughly US$36.1 million from US$119.4 million today.
Uncover why monday.com's fair value indicates a 26% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
For monday.com, the alternate story leans on AI as a powerful potential catalyst. The most optimistic analysts were penciling in revenue of about US$2.2b and earnings of US$279.8 million by 2029, well above the baseline view. Those projections came before this latest earnings setup, so treat them as one of several viewpoints to stress test, not a finished verdict.
Explore 7 other monday.com fair value estimates, including one that suggests as much as 134% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your monday.com research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for monday.com. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate monday.com's overall financial health at a glance.
Looking For More Investment Ideas Beyond monday.com?
If monday.com has sharpened your thinking about growth, risk and price, it can be useful to compare it with a wider set of opportunities that fit different goals, from stability to income to higher potential upside.
- If you care most about resilient balance sheets and steady fundamentals, scan a curated list of solid balance sheet and fundamentals (24 results) that can help you focus on financially robust businesses.
- If value is your priority, sort through a targeted 30 high quality undervalued stocks where strong cash flows and reasonable pricing sit at the center of the filter.
- If capital preservation ranks high on your list, narrow your watchlist with a 30 resilient stocks with low risk scores that concentrates on stocks with lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com