


Cash Flow Recovery Might Change The Case For Investing In Integra LifeSciences Stock (IART)
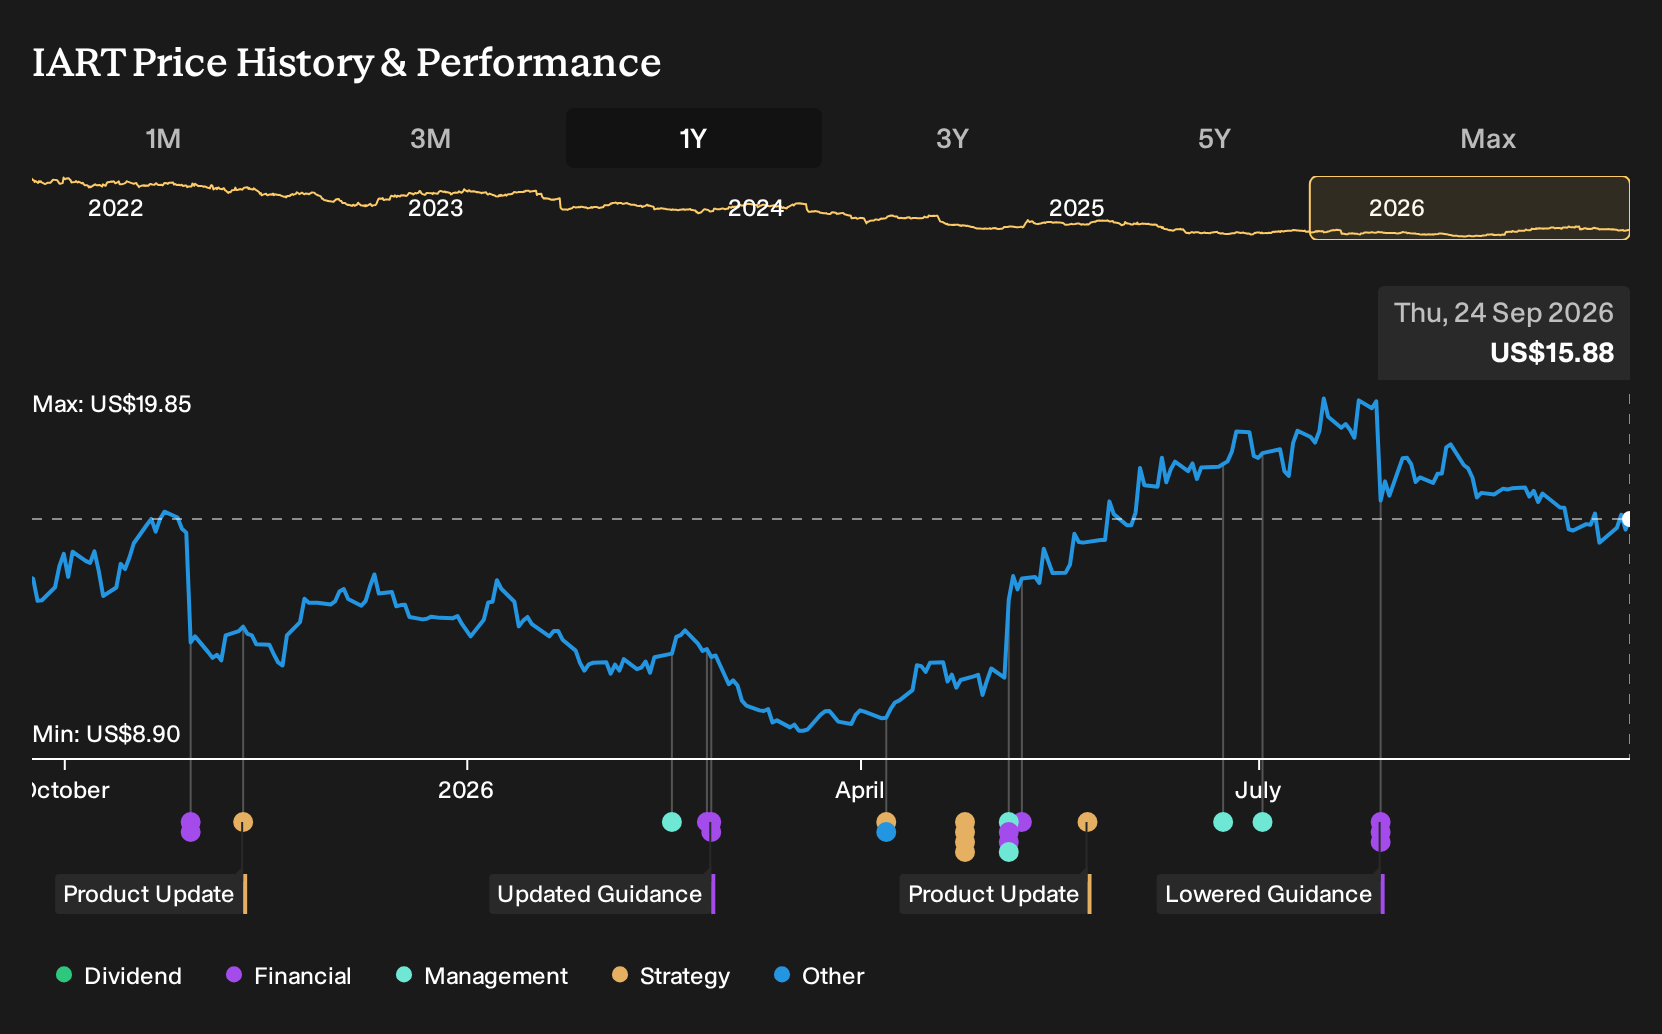
- Integra LifeSciences Holdings has drawn fresh attention after a long period of share price weakness followed by recent gains, which coincide with analysts reassessing how its projected cash flows compare with the current market value.
- The key twist is that projected cash flows now point to a recovery from earlier free cash flow outflows. This raises questions about whether Integra LifeSciences Holdings’ operations are being priced conservatively relative to its underlying cash generation potential.
- We will now look at how Integra LifeSciences Holdings’ investment narrative may shift as projected cash flow recovery gains investor attention.
Scan how Integra LifeSciences Holdings stacks up against a curated 30 high quality undervalued stocks that also appear mispriced relative to their underlying cash generation potential.
What Is Integra LifeSciences Holdings' Investment Narrative?
For Integra LifeSciences Holdings, the big picture you need to buy into is simple. A global surgical and wound care platform with US$1.65b in annual revenue, a large US footprint and two focused segments that can convert product demand into steady free cash flows over time. The recent share price recovery, alongside projections that point to cash flow improvement, puts execution front and center. Supply chain reliability, pricing power with hospitals and procedure volumes are what will decide whether those projections start to look like business reality.
In the short term, the key swing factors are clean operational delivery and how much investment is needed to support growth in neurosurgery and tissue reconstruction. Capital intensity and any need for heavier borrowing matter more now given that interest costs are not yet well covered by earnings. Analyst reappraisal and the renewed focus on cash generation amplify this tension. If management can show consistent progress toward profitability while keeping debt in check, the current debate around Integra LifeSciences Holdings could look very different.
Yet there is a less comfortable piece of the Integra LifeSciences Holdings puzzle that only really comes into focus when you consider ...
There's only one way to know the right time to buy, sell or hold Integra LifeSciences Holdings. Head to Simply Wall St's company report for the latest analysis of Integra LifeSciences Holdings's Fair Value.
Exploring Other Perspectives
For Integra LifeSciences Holdings, the most bullish analysts frame the news around cost efficiency as the real swing factor. Before this update, that group was pencilling in revenue of about US$1.8b and earnings of US$146.0m by 2029, which is far more optimistic than consensus. Use those gaps to explore how your own expectations might shift.
Explore another Integra LifeSciences Holdings fair value estimate, including one that suggests as much as 94% upside from the current price.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Integra LifeSciences Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Integra LifeSciences Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Integra LifeSciences Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Integra LifeSciences Holdings?
If Integra LifeSciences Holdings has sharpened your focus on valuation, balance sheet strength and cash generation, it can be useful to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- Prefer businesses that look mispriced against their fundamentals and cash flows. Scan a curated 30 high quality undervalued stocks that share similar value-driven characteristics.
- If capital preservation is high on your list, focus on companies with steadier risk profiles and resilient finances using a 30 resilient stocks with low risk scores tailored for that mindset.
- For those hunting for under-followed opportunities with solid underlying metrics, comb through a 16 high quality undiscovered gems that may not yet be widely on the market’s radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com