


Corpay (CPAY) Rolls Out New AI Agents, Is The Stock Fully Priced?
Why Corpay’s new AI agents matter for investors
Corpay (CPAY) just expanded its Corpay Complete platform with a new group of AI agents that focus on specific tasks in corporate, fleet, and vendor payments, putting automation and spend visibility in the spotlight.
Corpay’s latest AI agent rollout lands after a busy few months that also included a proposed US$100 million settlement with the FTC over marketing practices in its Vehicle Payments unit, which the company has said should not materially affect ongoing operations.
The share price sits at US$400.32. The 90 day share price return of 20.4%, alongside a 1 year total shareholder return of 37.01%, points to momentum that has been building rather than fading, as investors weigh product progress against regulatory clean up.
Scan how Corpay’s AI push compares with other payment and fintech players by running through our curated list of 16 high quality undiscovered gems, which are quietly building similar automation advantages.
Corpay’s rally and new AI launch present a straightforward choice. You can either lean into the momentum now, or wait for a pullback that may not align with your view of fair value.
Most Popular Narrative: 13.2% Undervalued
Corpay’s most followed valuation story anchors on a fair value of $461, which sits above the latest close at $400.32 and frames the current AI push as part of a broader cash generation and capital deployment case.
The main requirement for this approach is continued execution on portfolio simplification and capital deployment, including divesting non-core Vehicle Payments assets while using roughly $15b of available capital for buybacks and targeted corporate payments deals.
The current numbers, including raised 2026 cash EPS guidance to $27.35 and plans to use divestiture proceeds for repurchases, indicate a share price that does not fully reflect this cash generation and buyback capacity.
See why 14 investors see Corpay as 13% undervalued.
Result: Fair Value of $461 (UNDERVALUED)
Still, Corpay’s story can break if the proposed US$100m Vehicle Payments settlement tightens pricing power, or if expected double digit organic growth fails to materialise.
Find out about the key risks to this Corpay narrative.
Another view on Corpay’s valuation
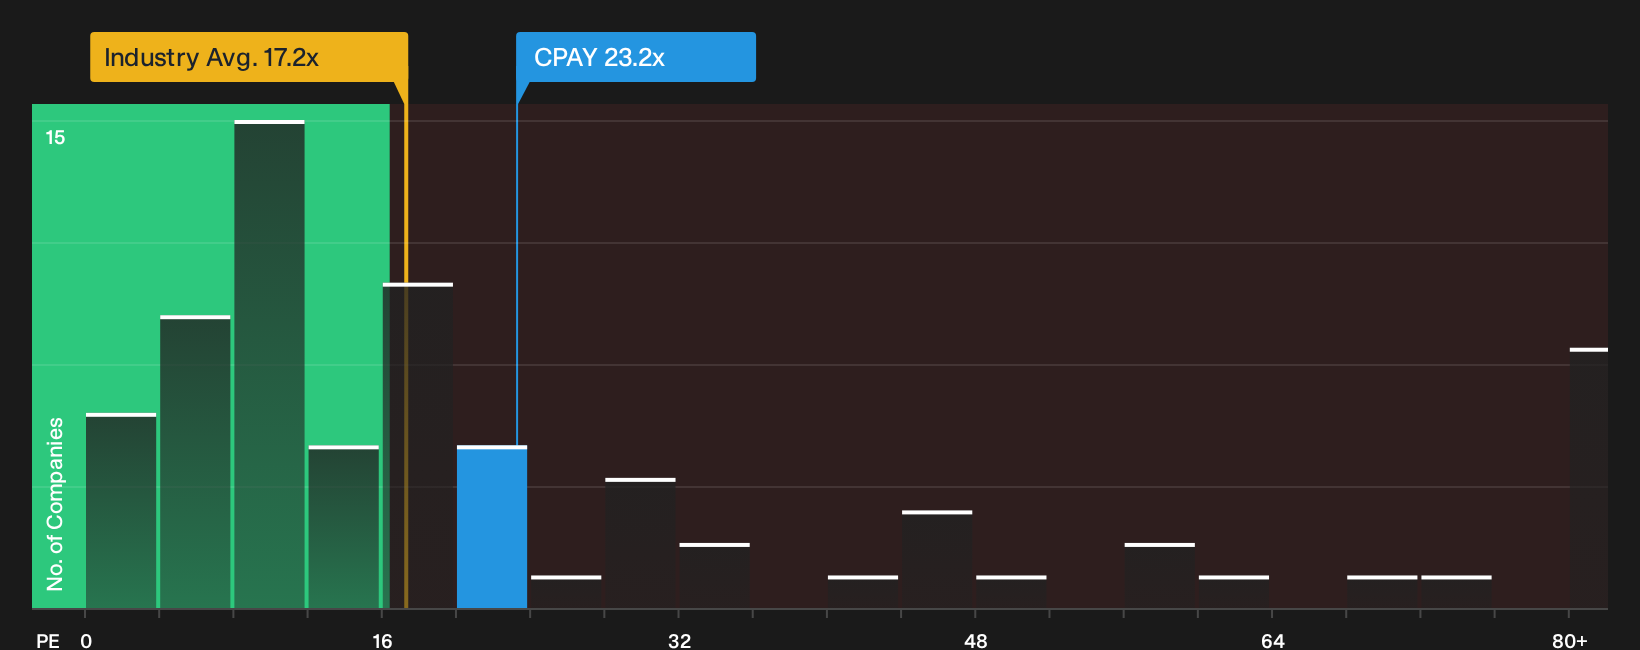
The story around Corpay’s $461 fair value leans heavily on analyst forecasts and cash flow assumptions. A second lens is the P/E ratio. The stock trades at 23.2x earnings, compared with 17x for the US Diversified Financial industry, a peer average of 18.1x, and a fair ratio of 18.7x.
That gap points to investors already paying a premium for Corpay relative to both sector and fair ratio benchmarks, which can limit upside if growth or buybacks do not match expectations. Are you comfortable paying more than the market for this earnings profile, or does that premium feel like valuation risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism around Corpay’s AI push and concern about regulatory and growth risks leaves you undecided, move fast and compare the data with your own expectations. To see both sides laid out in one place, review the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Corpay?
Do not stop with one opportunity. Corpay might fit your thesis, but a broader watchlist gives you more ways to put your views to work.
- Spot fresh turnaround potential by scanning 8 elite penny stocks with strong financials that already pair higher risk with solid underlying financial strength.
- Hunt for mispriced quality and compare Corpay with a curated mix of 30 high quality undervalued stocks that show stronger fundamentals relative to their current prices.
- Prioritise resilience by lining Corpay up against a 30 resilient stocks with low risk scores that scores well on balance sheet strength and earnings stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com