


Is Neogen (NEOG) Fully Valued On Leverage Concerns And Weakening Sales?
Neogen’s balance sheet under scrutiny after leverage concerns
Neogen (NEOG) is back in focus after fresh commentary flagged declining sales, weaker returns on capital, and a net-debt-to-EBITDA ratio of 6x. These factors are contributing to cautious investor sentiment.
Recent trading tells a more upbeat story. Neogen’s 30-day share price return of 16.75% and 90-day gain of 42.59% build on a 95.14% year-to-date share price move. However, the 5-year total shareholder return is still down 68.49%, suggesting current momentum is emerging from a weak long-term base.
Compare Neogen’s balance sheet challenges with a curated group of companies screened for stronger financial resilience using our 30 resilient stocks with low risk scores as a starting point for your next idea.
For Neogen, that surge on a still bruised five year record leaves a simple tension: Is this rerating about improving business fundamentals, or just sentiment snapping back? The valuation work starts there.
Most Popular Narrative: 5% Overvalued
Neogen’s most followed valuation story pegs fair value at $13 per share, slightly below the recent $13.66 close. This frames the current rally as somewhat ahead of the underlying assumptions built into that model.
The company's portfolio simplification, divesting lower margin and non core businesses (cleaners and disinfectants, genomics) and focusing on core food safety and animal health verticals, sets the stage for improved net margins and more resilient, higher quality earnings, supported by ongoing deleveraging and reduced operational complexity. Continued investments in R&D and new rapid testing assays (such as the recent launches on the MDS platform), combined with expansion in Europe and other international markets, will allow Neogen to capture share from competitors and participate in the secular growth of high throughput, automated diagnostic solutions, thus boosting both revenue and future earnings potential.
See why 5 investors see Neogen as 5% overvalued.
Result: Fair Value of $13 (OVERVALUED)
Still, Neogen’s story could change quickly if integration issues at the 3M Food Safety unit keep margins under pressure, or if Animal Safety revenue weakness persists.
Find out about the key risks to this Neogen narrative.
Another view on Neogen’s valuation
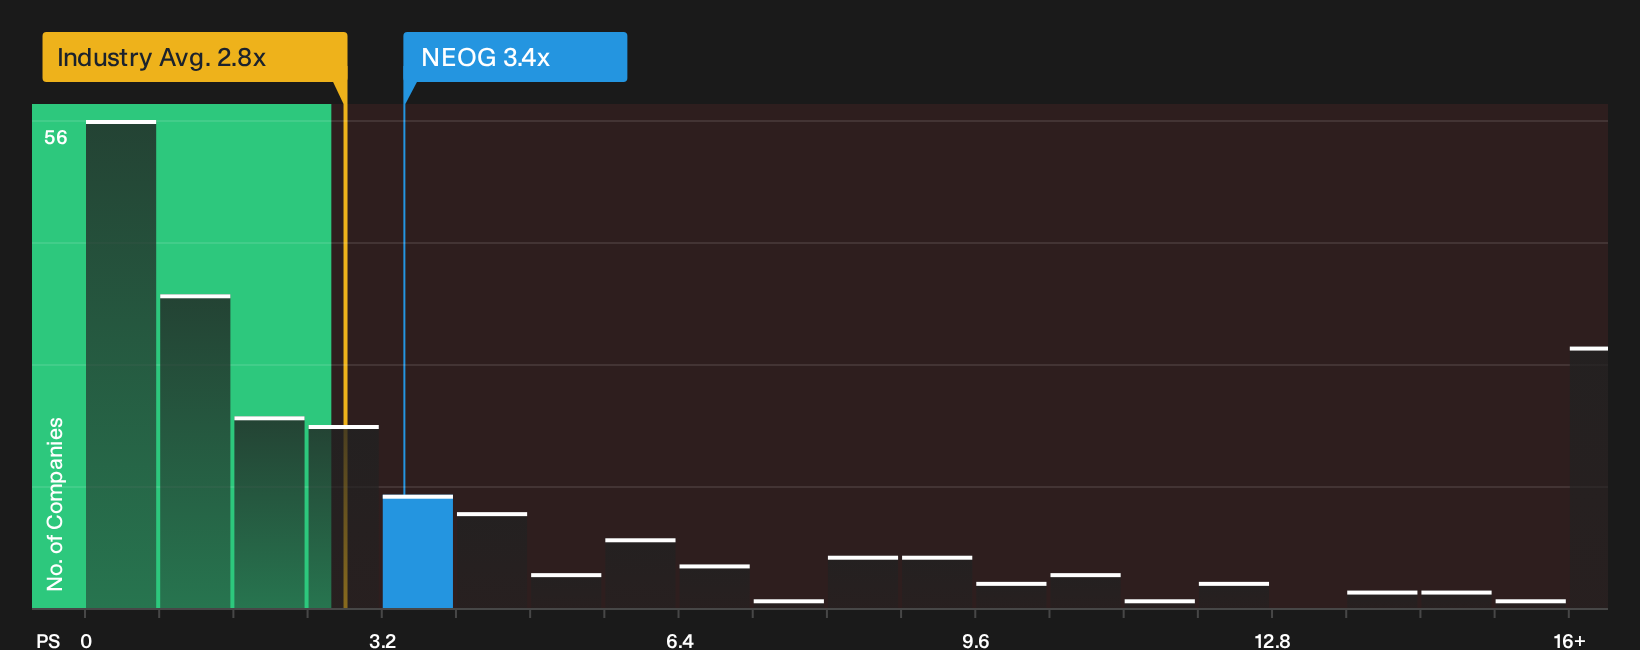
The fair value story does not stop at that $13 per share narrative. On a P/S of 3.4x, Neogen trades richer than the US Medical Equipment industry at 2.9x and well above its own fair ratio of 1.3x. That gap points to valuation risk if sentiment cools.
For a closer look at what the numbers imply for this price, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Reading this, you can see why opinion on Neogen is split. Take a few minutes to check the underlying figures yourself, then weigh them against the 1 important warning sign.
Looking for more investment ideas beyond Neogen?
Neogen’s story is only one piece of your portfolio puzzle. Broaden your opportunity set now so you are not relying on a single turnaround narrative.
- Target steadier potential with companies that pair durable earnings with stronger finances through our list of solid balance sheet and fundamentals (24 results).
- Hunt for pricing that looks more forgiving by scanning a 30 high quality undervalued stocks tailored to robust fundamentals.
- Prioritise resilience and capital protection by reviewing a 30 resilient stocks with low risk scores built around lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com