


MACOM Technology Solutions Holdings (MTSI) Stock Climbed, What Is Driving Attention Now?
MACOM Technology Solutions Holdings (MTSI) is back in the spotlight after announcing it will showcase its latest optical and high speed connectivity hardware at ECOC 2026 in Málaga this month.
Recent trading shows that momentum around MACOM Technology Solutions Holdings has cooled in the short term, even as the longer record remains strong. The share price is up 3.30% over the last day and 8.28% across the past week, yet the 90 day share price return is down 22.82% after a rapid run that left the year to date share price return at 62.86% and the 1 year total shareholder return at 130.01%. The 3 and 5 year total shareholder returns of 246.85% and 339.25% suggest that investors have been reassessing both growth potential and risk each time new product news like ECOC 2026 lands.
Seize the momentum in AI infrastructure by lining up MACOM Technology Solutions Holdings beside a curated set of 84 AI infrastructure stocks that are also tied to high performance networking and data build outs.That mix of short term cooling and strong multi year gains creates a simple tension around MACOM Technology Solutions Holdings. Are traders just rotating sentiment, or has the share price moved ahead of the underlying business?
Most Popular Narrative: 28% Undervalued
MACOM Technology Solutions Holdings closed at $284.94, while the most followed narrative anchors fair value at $395.33. The current share price sits well below that framework and places a lot of weight on whether the AI optics and compound semiconductor story keeps playing out as expected under an 11.32% discount rate.
The main factor that has to go right is that MACOM executes on its compound semiconductor capacity ramp and R&D program so that new products like high speed photodetectors, silicon photonics lasers and next generation GaN processes convert into sustained orders across a broader base of large customers.
The numbers imply that MACOM’s share price already discounts very strong growth and margin expansion. If the current high valuation multiples compress despite the company continuing to perform, equity returns could be weaker than the underlying business progress suggests.
See why 16 investors see MACOM Technology Solutions Holdings as 28% undervalued.
Result: Fair Value of $395.33 (UNDERVALUED)
Still, the MACOM Technology Solutions Holdings narrative depends on rich valuation multiples and heavy investment paying off, so any sentiment reset or weaker returns on R&D could quickly challenge it.
Find out about the key risks to this MACOM Technology Solutions Holdings narrative.
Another View: MACOM Technology Solutions Holdings Looks Expensive On Earnings
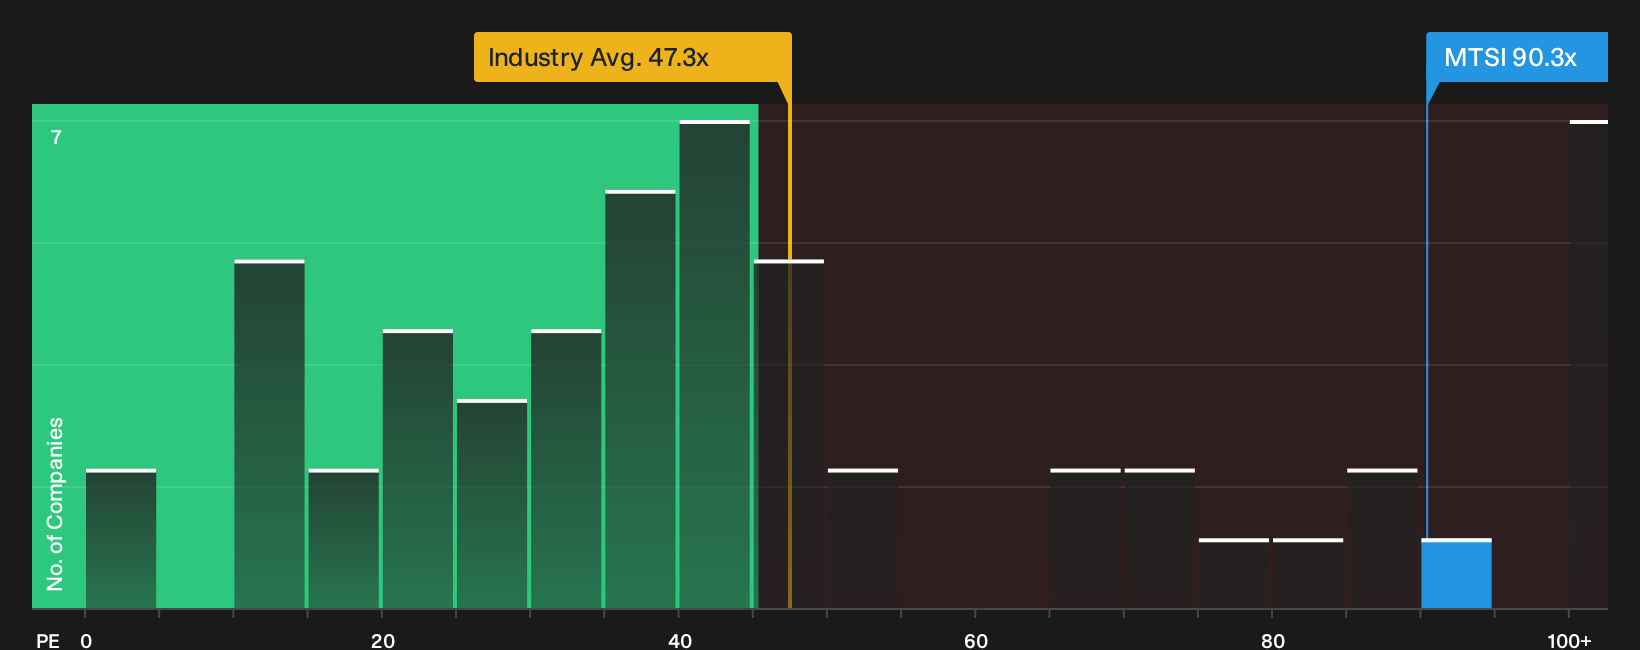
On the one hand, the MACOM Technology Solutions Holdings narrative leans on a fair value of $395.33. On the other, the current P/E of 90.3x is far above the US Semiconductor industry on 47.3x and a fair ratio of 38.2x, which points to valuation risk if sentiment cools.
That gap suggests the share price already bakes in a lot of optimism. The key question is how much earnings strength you want to assume before that multiple drifts closer to the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around MACOM Technology Solutions Holdings feels familiar, take a moment to inspect the numbers yourself and test the story against your own risk tolerance. To size up both sides properly, start with the 3 key rewards and 2 important warning signs.
Looking for more MACOM Technology Solutions Holdings sized ideas?
If you only stop at MACOM Technology Solutions Holdings, you risk missing other opportunities that fit your style just as well, or even better.
- Spot underpriced potential before the crowd moves by scanning a focused set of 30 high quality undervalued stocks that combine solid fundamentals with attractive entry points.
- Secure potential income streams by lining up candidates from a range of 7 dividend fortresses that emphasise yield alongside business resilience.
- Dial down risk without walking away from opportunity by filtering for 30 resilient stocks with low risk scores that score well on balance sheet strength and stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com