


Albertsons Companies (ACI) Retail Media Push Puts Its Undervalued Narrative Back In Focus
Why Albertsons Companies Stock Is Back in Focus
Albertsons Companies (ACI) is drawing fresh attention after its Albertsons Media Collective unit introduced an incrementality-based multi-touch attribution platform built with LiveRamp, aimed at giving advertisers a clearer view of cross-channel media impact.
The new retail media rollout comes against a tougher backdrop for Albertsons Companies’ shareholders, with the share price at US$11.95 after a 1-day share price return of 2.14% but a year-to-date share price return that has declined 30.96%. The 1-year total shareholder return is down 28.60%, suggesting recent momentum has been fading even as management pushes deeper into higher margin, data-driven services like Albertsons Media Collective.
Spot opportunities across retail and data-driven advertising by comparing Albertsons Companies with a hand picked group of 16 high quality undiscovered gems.Given Albertsons Companies’ falling 1-year and 3-year total returns, alongside this new retail media push, is the latest share price move a sign that sentiment is resetting or that the underlying grocery business is being mispriced on today’s numbers?
Most Popular Narrative: 16% Undervalued
On this framework, Albertsons Companies is assessed with a fair value of $14.19 against a last close of $11.95, which puts the current share price at a meaningful discount and frames the new media and restructuring moves as part of a longer reset story rather than a short term bounce.
Modernization through technology investments, such as automation, AI-driven inventory/pricing, and centralized buying, are streamlining operations, reducing labor and supply chain costs, and positioning the company for long-term margin expansion and improved net earnings.
Increasing penetration of private label and own brands, now at 25.7% of sales with a push to reach 30%+, along with targeted value investments, are driving higher-margin sales, deepening brand loyalty, and contributing to gross margin stabilization over time.
See why 20 investors see Albertsons Companies as 16% undervalued.
Result: Fair Value of $14.19 (UNDERVALUED)
Still, the risk narrative around Albertsons Companies is real, with ongoing labor cost pressure and market share losses, both capable of undermining the current restructuring story.
Find out about the key risks to this Albertsons Companies narrative.
Another View on Albertsons Companies Valuation
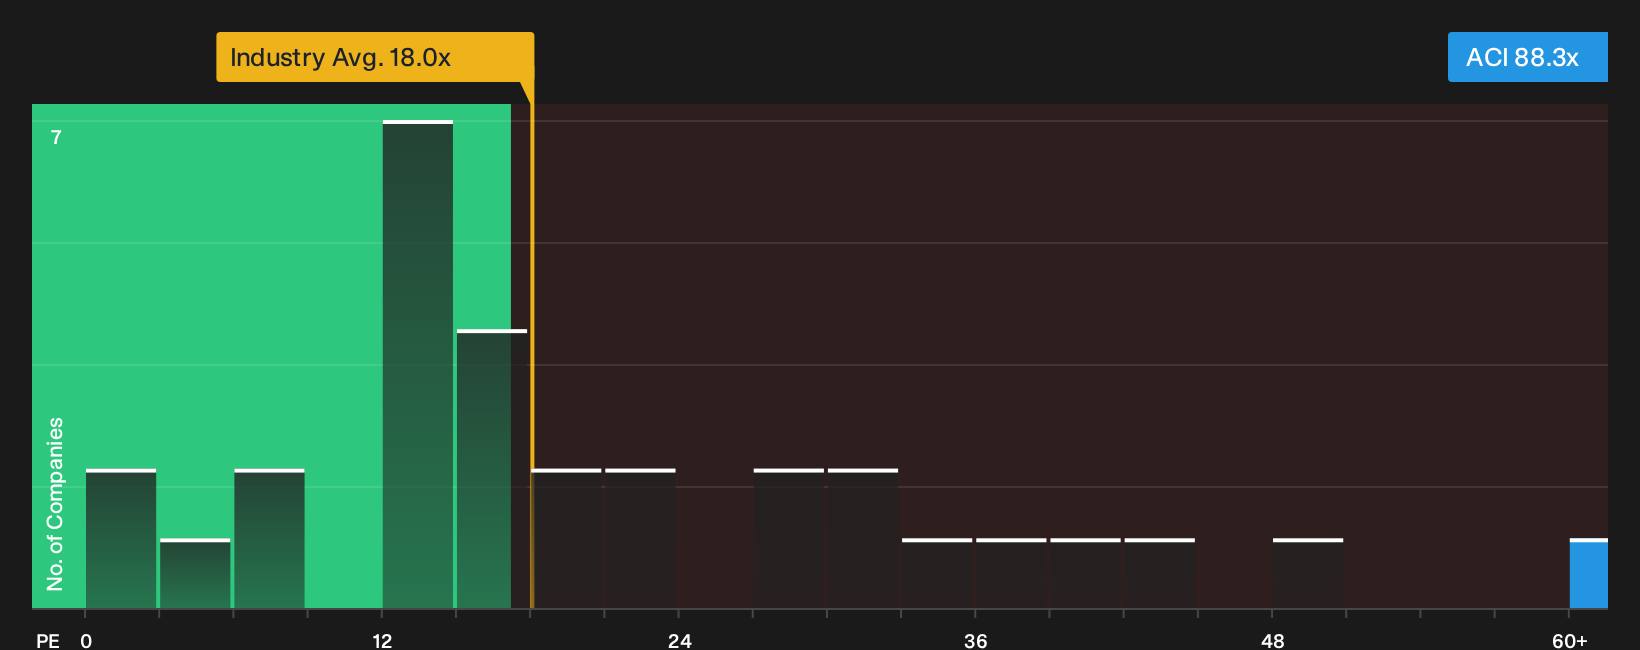
The first lens paints Albertsons Companies as undervalued against a fair value of $14.19. A different yardstick tells a harder story. On a P/E basis, ACI trades at 88.3x earnings compared with 18x for the US Consumer Retailing industry and about 20x for peers.
The fair ratio for ACI sits at 32.7x. That is far below the current multiple, which highlights valuation risk if sentiment shifts toward what the fair ratio suggests the market could move toward over time. The question for you is which signal to rely on when the numbers disagree.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals like these on Albertsons Companies rarely sit still for long. Review the numbers, weigh both sides, then ground your stance in the 2 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Albertsons Companies?
If Albertsons Companies has you rethinking where value and risk meet, do not stop here. Use the screener to hunt for setups that better fit your style.
- Pinpoint quality at a discount by checking companies that pass the 30 high quality undervalued stocks and stack up well on fundamentals.
- Strengthen your core holdings by filtering for businesses with healthy finances using the list of solid balance sheet and fundamentals (24 results).
- Dial back portfolio stress by focusing on steadier candidates highlighted in the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com