


Will New Rehab Hospitals Change Encompass Health (EHC) Narrative
- Encompass Health has expanded its inpatient rehabilitation footprint with a new 50 bed hospital in Lower Providence, Pennsylvania, and announced future capacity projects in Conroe and The Woodlands in Montgomery County, Texas.
- The Conroe project introduces Encompass Health’s first small format inpatient rehabilitation hospital, a model that links to existing facilities to extend specialized care into nearby growth markets while sharing resources.
- We will now look at how Encompass Health's new small format Conroe hospital could influence the broader investment narrative around expansion.
Scan how Encompass Health’s expansion blueprint compares with peers by reviewing our curated list of list of solid balance sheet and fundamentals (23 results) in similar long term care and healthcare service niches.
Encompass Health Investment Narrative Recap
For Encompass Health, the basic belief is that inpatient rehabilitation can keep supporting disciplined capacity growth while payer pressure and labor costs stay manageable. The Houston area projects and the new Lower Providence hospital reinforce that the near term story is still about execution on a build out plan. The most immediate swing factor remains how quickly new beds reach efficient occupancy and staffing levels.
The biggest business risk right now is capital going into projects that do not ramp as modeled, especially if tougher Medicare Advantage behavior or reimbursement adjustments slow volume growth or squeeze margins. These announcements do not radically change that risk reward balance. They simply add more sites that need to perform to keep returns on invested capital where investors expect them to be.
The Conroe small format hospital that Encompass Health plans to open in 2027 feels most relevant here. It is the first test of a model that links a 24 bed satellite to an existing Woodlands facility and uses shared infrastructure. That structure may matter for unit economics, staffing flexibility and how quickly new capacity supports discharge growth.
If this Conroe approach ramps smoothly, investors get more evidence that Encompass Health can extend into nearby communities without building only large stand alone hospitals. This ties directly to the expansion catalyst. If occupancy takes longer or payer behavior tightens in this catchment area, it would reinforce concerns that aggressive capital spending into new formats can weigh on margins and slow the earnings trajectory analysts currently outline.
Encompass Health's current analyst storyline points to revenues of US$7.9b and earnings of US$806.1m by 2029, based on an assumed 8.4% yearly revenue growth rate and an earnings increase of about US$202.4m from US$603.7m today.
Uncover how Encompass Health's fair value indicates a 21% potential upside to its current price before the market closes that gap.
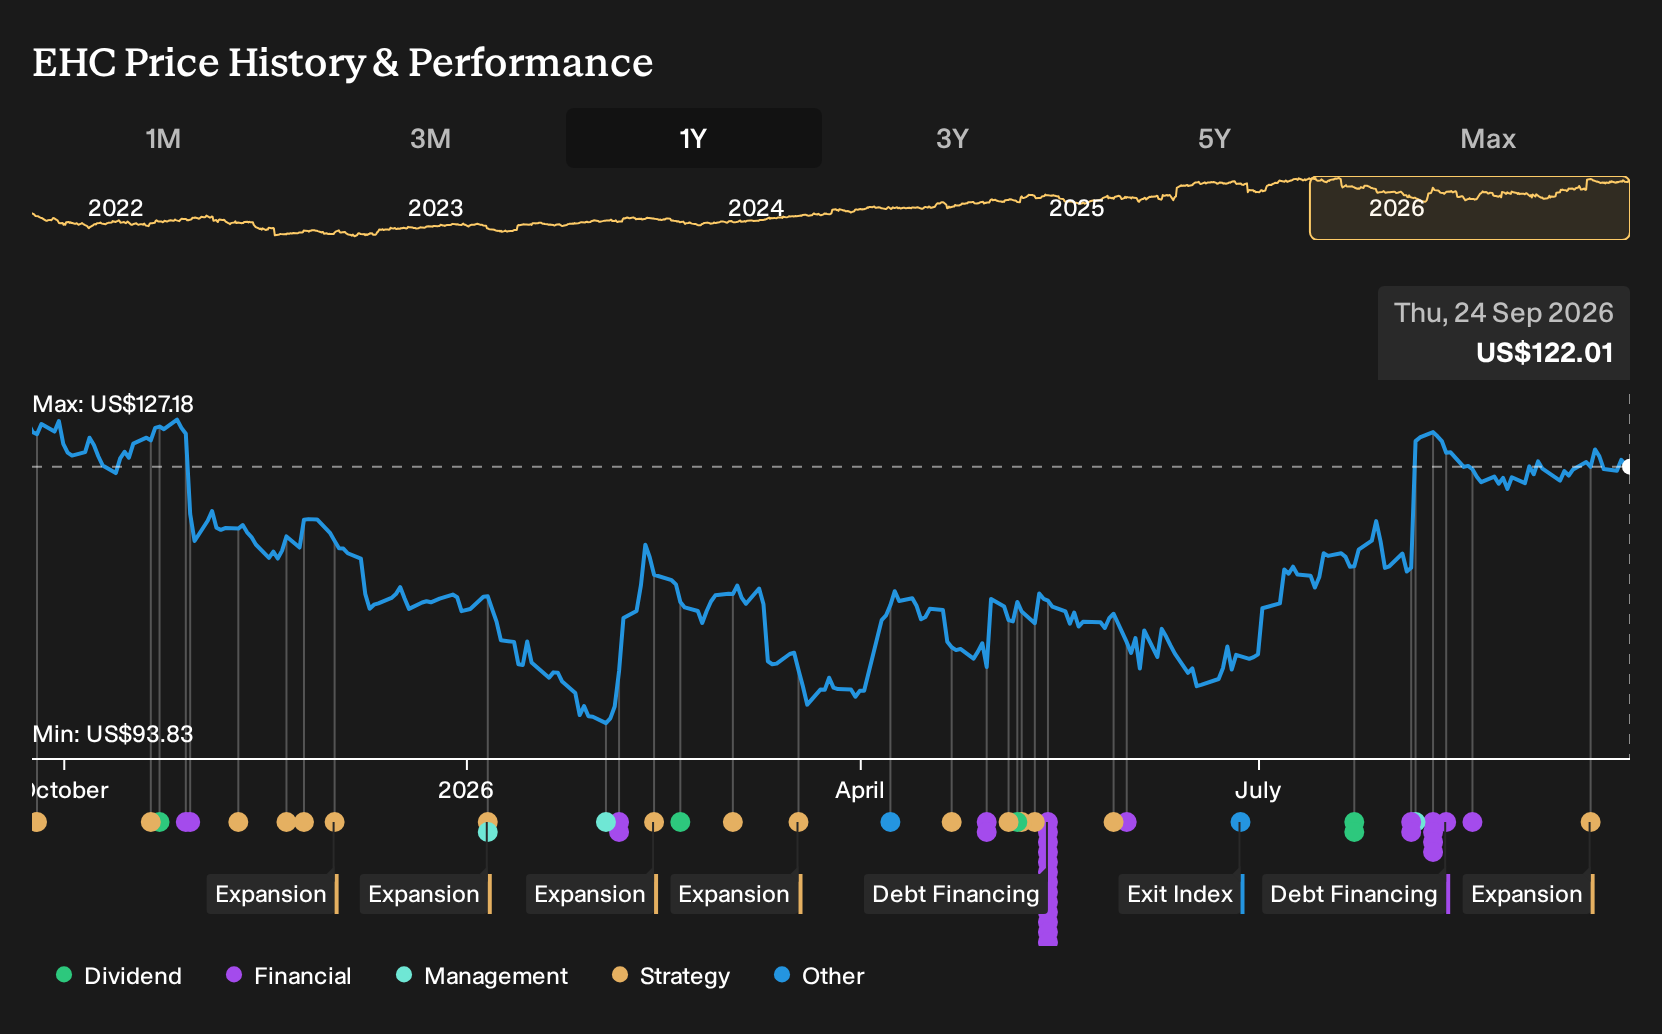
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between US$99.17 and US$148.17 per share, so community views on Encompass Health already span a wide valuation band. Set those opinions against risks around tougher Medicare Advantage behavior and reimbursement shifts, then weigh how this expansion heavy plan might affect long run performance. Explore those alternative viewpoints before forming your own stance.
Explore 3 other Encompass Health fair value estimates, including one that suggests as much as 21% potential upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Encompass Health research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Encompass Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Encompass Health's overall financial health at a glance.
Looking For More Ideas Beyond Encompass Health?
Once you have formed a view on Encompass Health, it can help to compare that thesis with other businesses that share similar quality traits or different risk profiles. The Simply Wall St Screener lets you do exactly that by filtering companies based on balance sheet strength, value characteristics, income potential and more.
- For investors who care most about staying power, start with resilient businesses and assess a 31 resilient stocks with low risk scores that may offer a calmer ride through market swings.
- If value is the priority, run through companies that combine quality fundamentals with more modest expectations using our 30 high quality undervalued stocks.
- For those focused on financial robustness and cleaner balance sheets, compare Encompass Health with a broader list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com