


Saputo (TSX:SAP) Could Be 15% Undervalued As Its New Structure Takes Shape
Why Saputo’s new structure matters for shareholders
Saputo (TSX:SAP) has reshaped its organization, creating a dedicated Ingredients Division led by Steve Douglas and introducing a Chief Enterprise Transformation Officer role. For investors, this raises fresh questions about execution, capital allocation, and long term positioning.
Saputo’s reworked structure arrives after a period where the share price has softened in recent months, but the longer trend has been much kinder to holders. The 90 day share price return declined 5.11%, while the 1 year total shareholder return of 23.57% and 3 year total shareholder return of 52.68% point to momentum that has built over time. Recent appointments around the Ingredients Division and enterprise transformation give investors fresh context for those past gains and may influence how the market weighs growth potential against execution risk from here.
Compare Saputo’s pivot toward higher value dairy ingredients with other potential breakout opportunities by scanning a curated list of 9 high quality undiscovered gems across global markets.
Saputo trades below the average analyst target and yet sits slightly above one intrinsic value estimate. Is that a sensible safety margin, or a signal that the market is already pricing in the new structure?
Most Popular Narrative: 15% Undervalued
Saputo closed at CA$40.27, while the most followed narrative pegs fair value at CA$47.63 using a 6.35% discount rate. This frames the new structure debate around whether the current price already reflects those assumptions.
Saputo's strategic focus on higher-value, branded, and convenience-oriented dairy products is supported by robust demand from a growing global population, accelerating urbanization, and shifting consumer habits. These factors are enabling volume and pricing growth across channels, directly benefiting revenue and supporting long-term market share gains.
See why 28 investors see Saputo as 15% undervalued.
Result: Fair Value of CA$47.63 (UNDERVALUED)
Still, the narrative could wobble if plant based alternatives erode dairy demand faster than expected or if tighter environmental rules lift long term production costs.
Find out about the key risks to this Saputo narrative.
Another View on Saputo’s valuation
That 15% undervalued narrative is not the only lens on Saputo. Our DCF model points to a future cash flow value of CA$38.63, compared with the current price of CA$40.27. On that measure the shares screen as slightly overvalued, which raises a simple question: Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
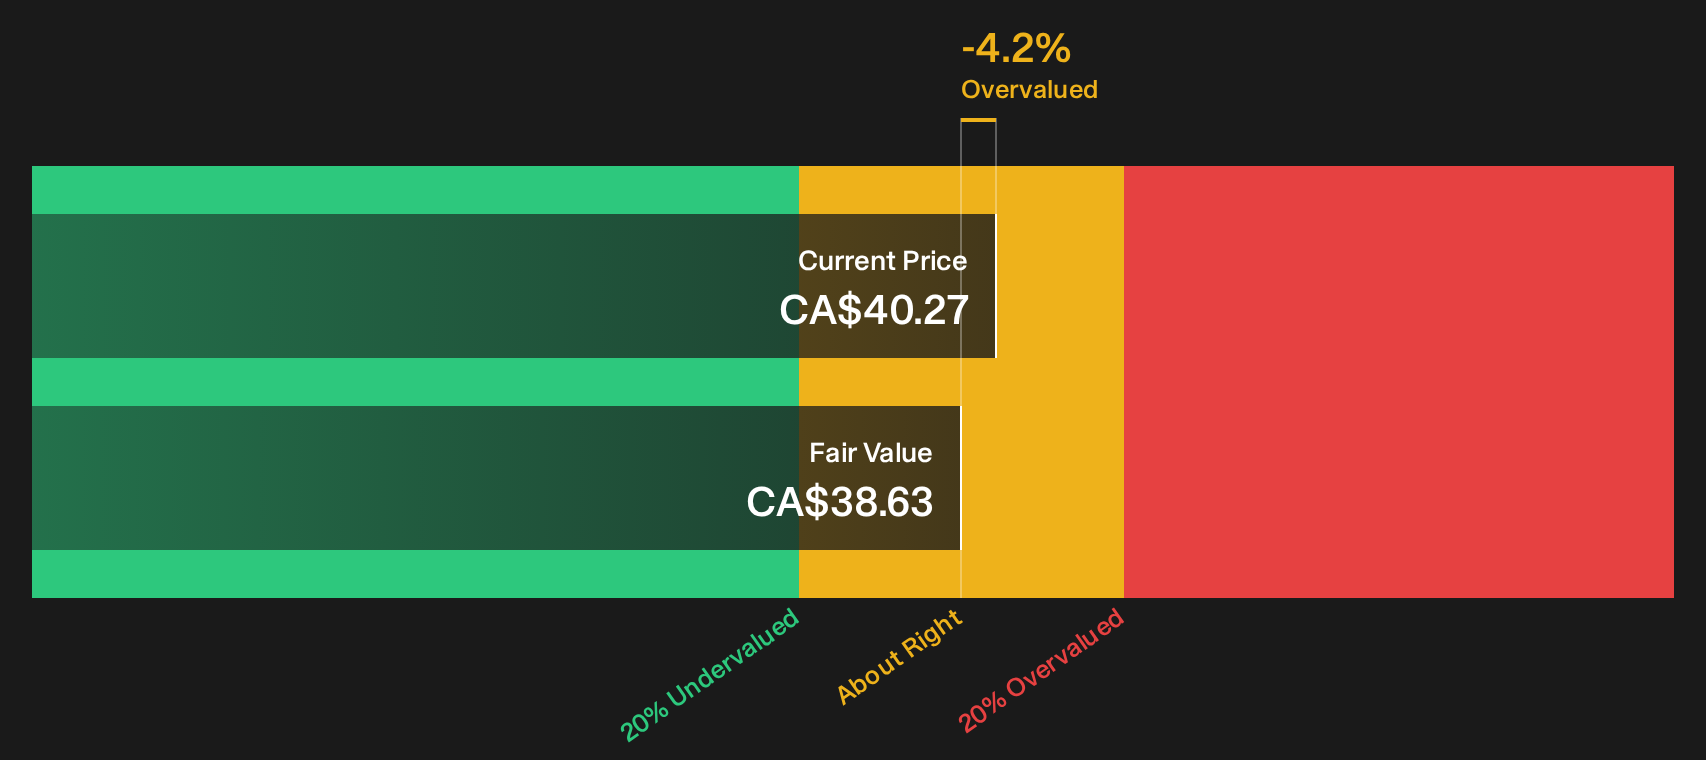
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Saputo for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and caution around Saputo feels familiar, move quickly and dig into the details yourself so your view is grounded in data. Then round out your work by checking the 3 key rewards
Looking for more Saputo sized investment ideas?
Do not stop at Saputo. Put your research momentum to work and line up your next watchlist candidates using data rich tools that surface ideas in minutes.
- Target potential mispricings by scanning a focused set of higher quality opportunities through the 5 high quality undervalued stocks.
- Prioritise resilience by filtering companies with stronger finances using the list of solid balance sheet and fundamentals (7 results).
- Spot early stage potential by reviewing a curated 19 elite penny stocks with strong financials that meet stricter financial quality hurdles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com