


Is AI Search Partnership Altering The Investment Case For Estée Lauder (EL)?
- In September 2026, The Estée Lauder Companies announced a global partnership with Profound, using its AI marketing platform to monitor and optimize how the entire brand portfolio appears across major generative AI assistants such as ChatGPT and Gemini.
- The tie up gives Estée Lauder Companies a single, data driven view of how products are recommended by AI tools so content on product pages, blogs and video channels can be adjusted to improve accuracy, compliance and customer engagement at scale.
- We will now look at how Estée Lauder Companies' AI native discovery push with Profound could reshape the existing investment narrative.
Estée Lauder Companies Investment Narrative Recap
To own Estée Lauder Companies, you need to believe the Profit Recovery and Growth Plan and One ELC model can keep turning restructuring pain into a cleaner cost base and healthier margins, without dulling brand appeal. The global Profound partnership sits squarely in that story as an execution tool for AI native discovery, rather than a standalone financial catalyst.
The near term swing factor still looks operational. Consistent delivery on restructuring, online mix and travel retail stability matters more than this marketing agreement on its own. The biggest near risk remains that workforce and door reductions or governance issues disrupt day to day performance and delay any improvement in earnings quality and cash generation.
The recent US$15m, five year commitment to the Breast Cancer Research Foundation adds a different type of signal to this AI heavy news flow. It reinforces Estée Lauder Companies’ long running focus on brand equity, social impact and partnerships with credible institutions, which can support pricing power and customer loyalty over time if execution holds.
For investors watching catalysts, this kind of global initiative sits alongside the Profit Recovery and Growth Plan and AI build out as a test of follow through. Large philanthropic commitments still need to be balanced with debt levels, restructuring charges and the aim of higher future margins, so the onus is on management to keep cash discipline tight.
Estée Lauder Companies' analyst narrative points to revenues of US$17.1b and earnings of US$1.5b by 2029, based on an assumed 4.4% yearly revenue growth rate. That implies an earnings increase of about US$1.3b from US$182.0m today to the 2029 consensus level.
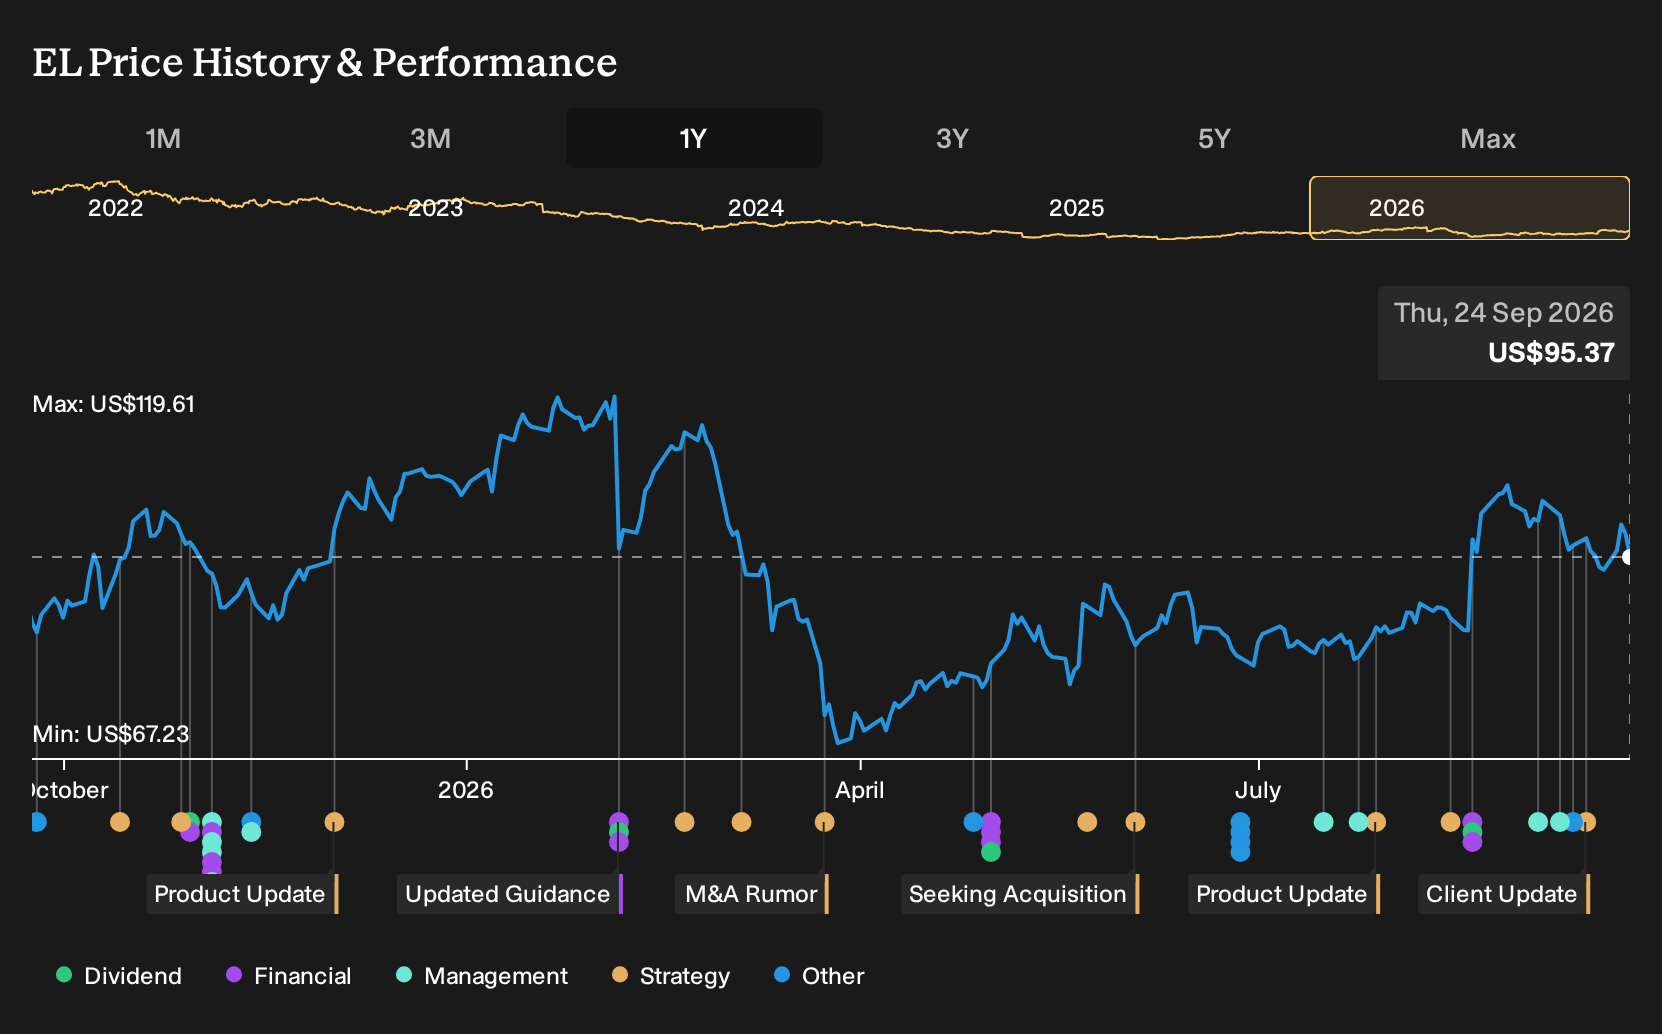
Uncover why Estée Lauder Companies' fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Estée Lauder Companies’ exposure to emerging markets as the real swing factor. Before this AI partnership news, they were pencilling in about US$17.4b of revenue and US$1.9b of earnings by 2029. You can treat this AI discovery push as a fresh input that might reshape those bullish assumptions.
Explore 4 other Estée Lauder Companies fair value estimates, including one that suggests there could be as much as 55% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Estée Lauder Companies research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Estée Lauder Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Estée Lauder Companies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Estée Lauder Companies?
If Estée Lauder Companies has sharpened your focus on quality and execution, it can be useful to line it up against other businesses with clear financial stories using the Simply Wall St Screener.
- If you want potential bargains with solid fundamentals, start with a curated set of 30 high quality undervalued stocks that may warrant a closer look alongside Estée Lauder Companies.
- For investors who care most about balance sheet strength, compare Estée Lauder Companies with a list of solid balance sheet and fundamentals (23 results) that aims to prioritise financial resilience.
- If you prefer quieter opportunities away from the spotlight, review a 16 high quality undiscovered gems that could sit beside Estée Lauder Companies on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com