


Is Media Spotlight Altering The Investment Case For AAON (AAON)?
- AAON recently received favorable media coverage that highlighted its heating and cooling business, strong order backlog, and projected revenue gains built on a solid sales pipeline.
- The spotlight on AAON's backlog growth and potential market share expansion drew attention to how operational execution and demand trends may be shaping its future earnings power.
- We will look at how AAON's investment narrative is influenced by media attention on its robust backlog and projected revenue gains.
Scan beyond AAON and this latest backlog driven spotlight to see how other industrials with strong pipelines line up in our curated list of solid balance sheet and fundamentals (23 results).
AAON Investment Narrative Recap
To own AAON, you need to believe the business can convert its large HVAC and data center cooling backlog into profitable shipments while ironing out operational friction. The recent media buzz and short term share price moves do not change the core near term catalyst. That catalyst is progress on ERP rollouts, factory efficiency, and smooth ramp up of newer facilities.
The biggest near term risk still sits inside the plants and systems, not the headlines. Extended ERP disruption, cash flow strain from high capex, or weaker demand in nonresidential and rooftop markets could compress margins and slow the benefit of that strong backlog, even if investor interest stays high after the Yahoo feature.
The Yahoo article that highlighted AAON as an industrial stock to consider and the subsequent 5.4% and 3.76% share price moves matter mainly because they shine a brighter light on execution. More eyes on the firm can sharpen focus on whether BasX expansion, Memphis capacity, and data center orders actually translate into the margin recovery analysts expect over the next few years.
Short term, this attention does not change the operational to do list. Investors still need to track backlog quality in data center and high efficiency HVAC, watch for clean ERP cutovers, and monitor whether higher SG&A and labor costs settle down as new capacity is absorbed. If those pieces do not improve, the recent momentum buying may have little lasting fundamental support.
What The AAON Forecasts Embed
AAON's narrative projects US$3.4b in revenue and US$496.3m in earnings by 2029, based on analyst estimates. That path assumes revenue expansion of 20.2% per year and an earnings step up of about US$337m from current earnings of US$159.3m.
Uncover how AAON's fair value indicates a potential upside of 70% to its current price that could narrow quickly.
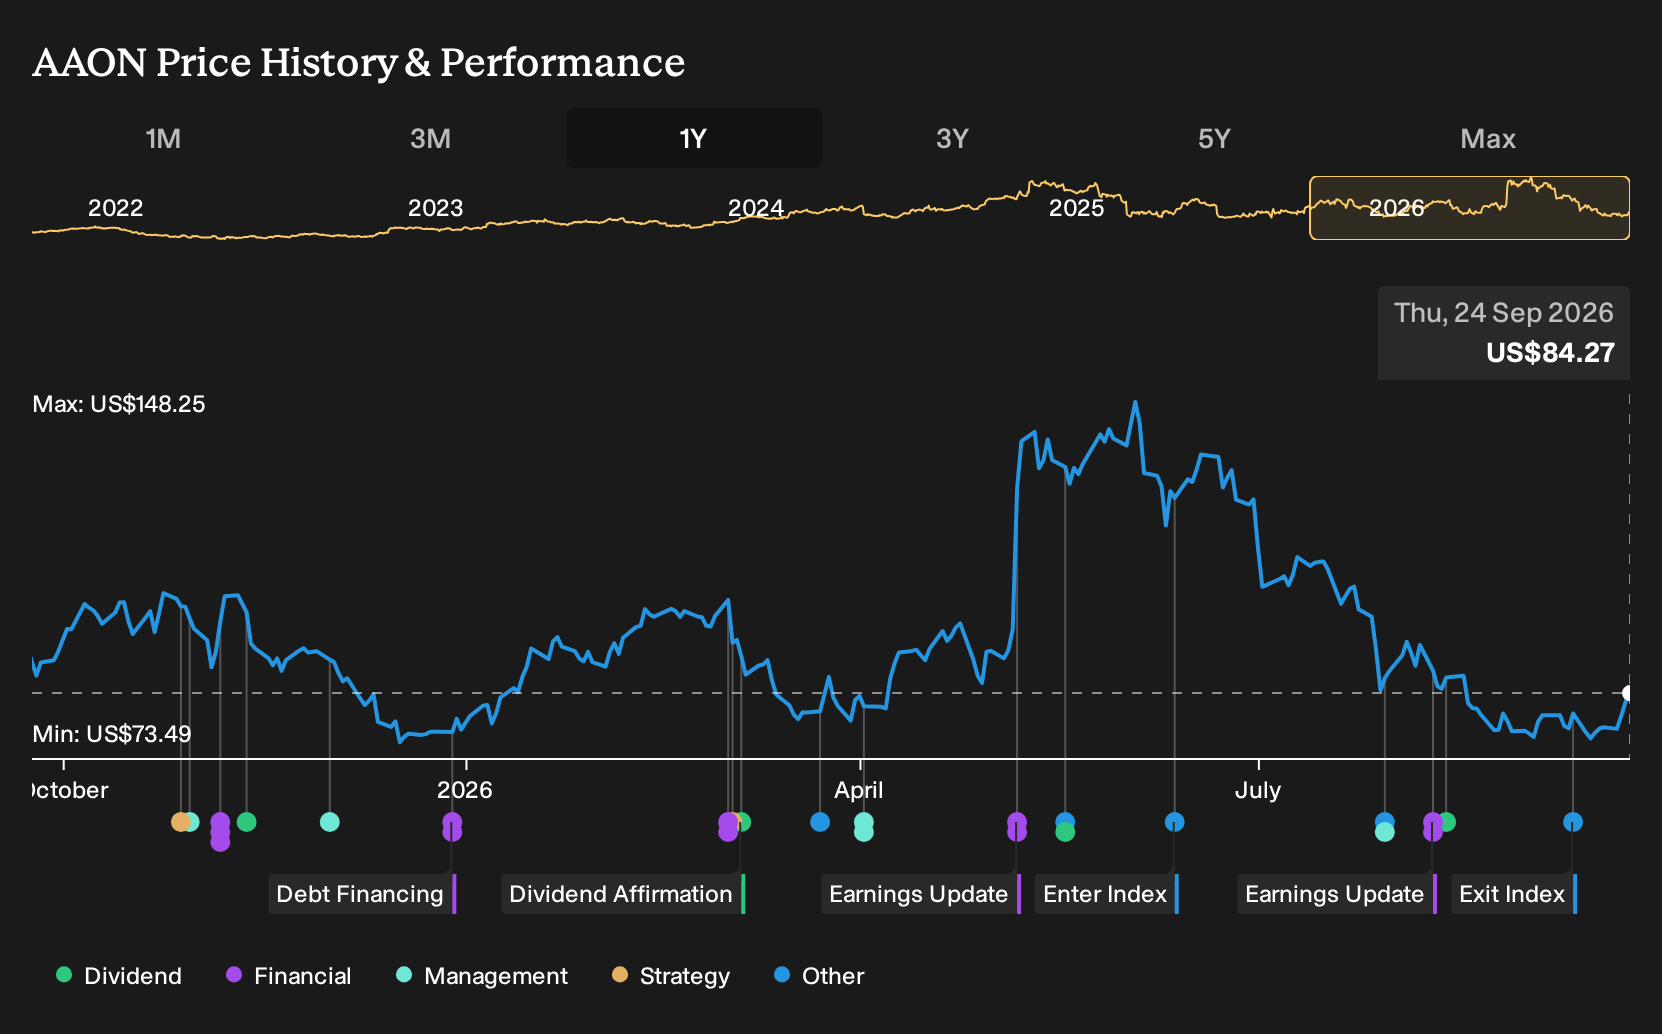
Exploring Other Perspectives
One alternate AAON angle puts the spotlight on upside from faster backlog conversion. The most optimistic analysts were already penciling in revenue of about US$2.9b and earnings of US$346.8m by 2029, versus US$118.1m today. That is a far more upbeat script than consensus, and the recent media driven price moves may eventually nudge those views again.
Explore 3 other AAON fair value estimates, including one that suggests as much as 196% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AAON research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for AAON. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate AAON's overall financial health at a glance.
Looking for more AAON style investment ideas?
If the AAON story has sharpened your thinking about backlogs, balance sheets, and earnings power, use that same lens on a broader set of businesses with the Simply Wall St Screener.
- For investors who want potential growth without ignoring quality, scan a curated set of 16 high quality undiscovered gems that pair solid fundamentals with underfollowed stories.
- If capital preservation sits high on your priority list, filter for companies assessed as having stronger financial resilience using our 31 resilient stocks with low risk scores.
- Income focused investors can zero in on payout heavy opportunities by reviewing a hand picked group of 7 dividend fortresses that combine yield with balance sheet checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com