


What Does U.S. Bancorp (USB) Gain From Naming A New PMI Sales Head?
- U.S. Bancorp (NYSE:USB) has appointed Calvert Lange as Senior Vice President and Payments, Merchant and Institutional Sales Group Head.
- Lange will lead payment and treasury management sales efforts for key industry sectors within the Payments: Merchant and Institutional group.
- She joins U.S. Bancorp with experience from major global financial institutions focused on institutional, corporate and merchant client solutions.
- The appointment of Calvert Lange to oversee Payments: Merchant and Institutional sales is important, but investors should weigh other factors too. We have also spotted 1 warning sign worth knowing about at U.S. Bancorp.
For readers watching how large banks approach fee-based income and shareholder returns, the next stop is 7 dividend fortresses.
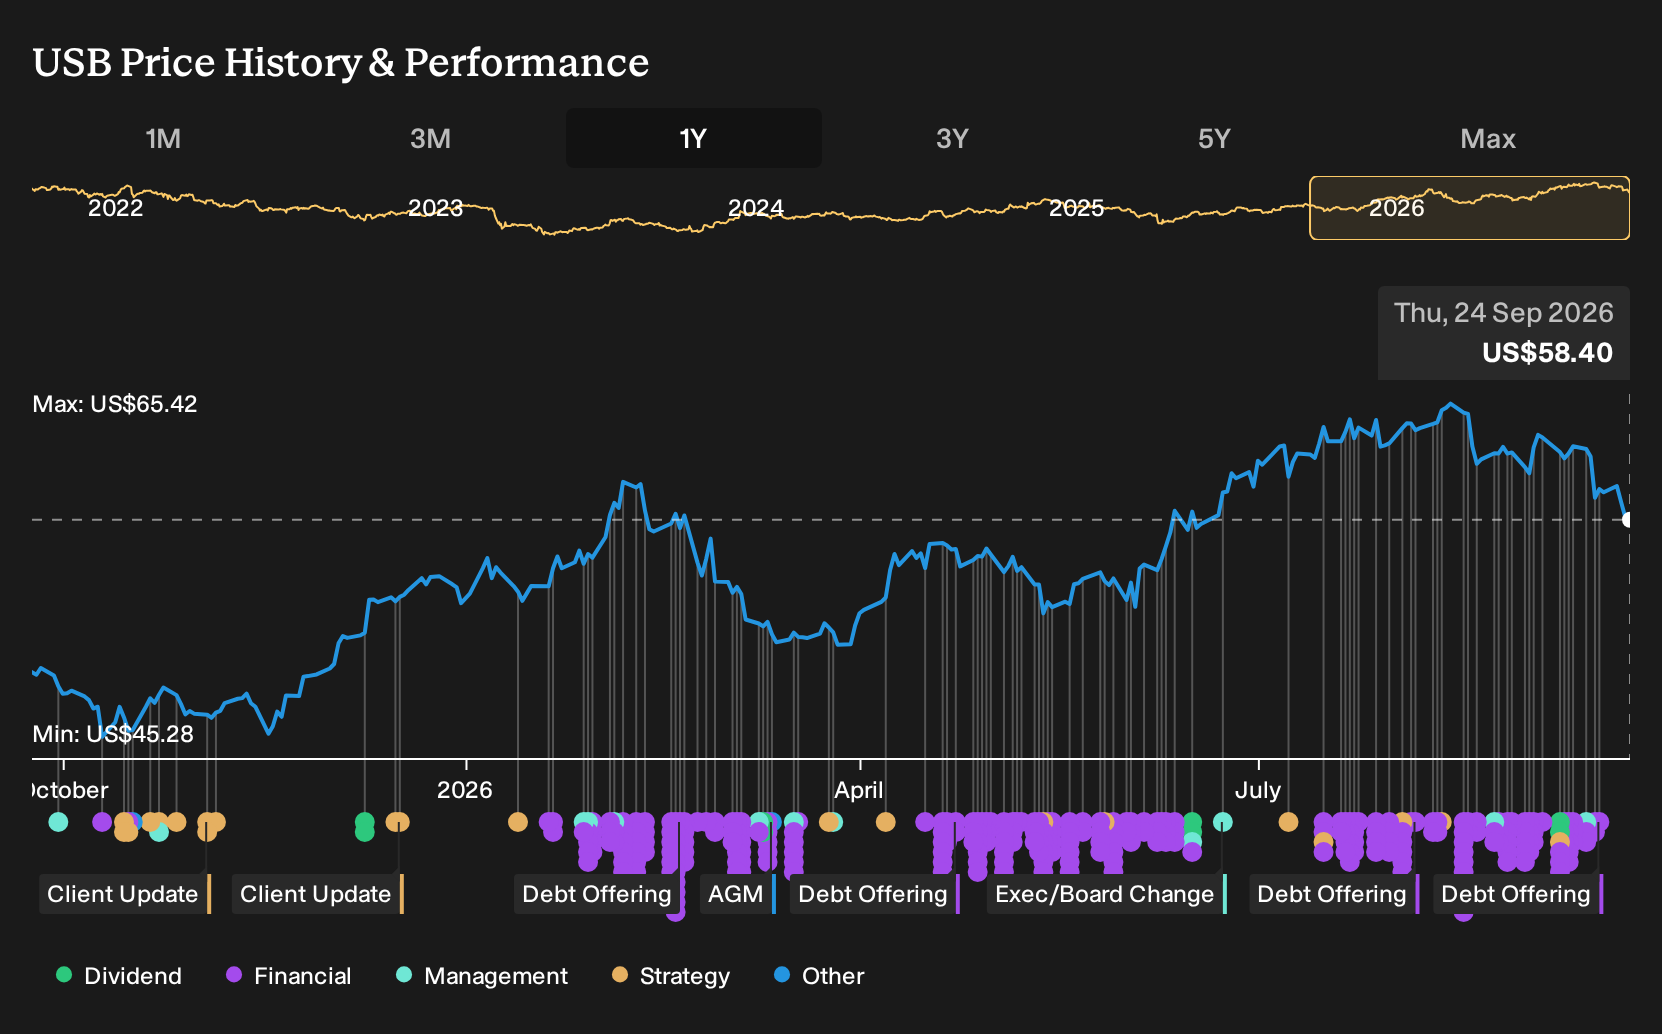
U.S. Bancorp, a US financial services holding company with a market value of about $91.1b, serves individuals, businesses and institutions. The Payments, Merchant and Institutional unit is closely aligned with how its large corporate and institutional clients move money and manage liquidity.
How the new PMI sales head ties into U.S. Bancorp’s fee income story
U.S. Bancorp’s Narrative is built around using its payments and tech franchise to keep fee-based revenue meaningful, while capital markets and capital returns round out the story. Calvert Lange’s hire drops directly into that bet, because it targets how large corporates move money every day.
"U.S. Bancorp's earlier focus on payments volumes, trust and investment management fees is now supported by fee income at 44% of total revenue in 2Q26 and low teens fee growth..."
See how the full story points towards a $70.33 fair value for U.S. Bancorp.
Lange’s background at Citi and Deutsche Bank lines up with the Narrative’s emphasis on commercial clients, payments flows and treasury services rather than one-off trading activity. For a bank that is leaning into BTIG and capital markets build-out, this appointment keeps the center of gravity on recurring payments and liquidity services that tie into those larger platforms.
The move also touches a key tension in the thesis. Analysts see opportunity in tech-driven efficiency and fee expansion, but they have flagged rising competition from fintechs and other large banks such as JPMorgan and Bank of America in payments. Whether this hire strengthens execution in high-growth sectors or simply maintains share will be an important test of that risk.
Ultimately, this leadership change matters only in the context of the story investors buy about U.S. Bancorp’s ability to turn payments, capital markets and tech spending into lasting fee income.
What are analysts really penciling in for U.S. Bancorp a few years from now?
Quarterly headlines only tell you what U.S. Bancorp looks like today. The deeper question is where consistent forecasts think this franchise ends up a few years down the road. See where analysts expect U.S. Bancorp to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com