


Granite Real Estate Investment Trust (TSX:GRT.UN) Confirms September Distribution, Is The Valuation Still Compelling?
Granite Real Estate Investment Trust (TSX:GRT.UN) has two fresh touchpoints for income focused investors this month: a confirmed September cash distribution and an upcoming virtual investor presentation led by CEO Kevan S. Gorrie.
Recent trading has been choppy for Granite Real Estate Investment Trust. The 30-day share price return is down 7.48% and the 90-day move is lower by 13.93%. However, the year-to-date share price return is slightly positive at 0.96%, and the 1-year total shareholder return of 11.95% points to momentum that has cooled in the short term but held up over a longer stretch.
Spot 8 resilient stocks with low risk scores that, like Granite Real Estate Investment Trust, focus on income, occupancy strength, and balance sheet resilience.Granite Real Estate Investment Trust is generating higher FFO and maintaining steady distributions while the unit price has cooled in recent months. Strong business, softer chart. Does the current tag still make sense for new capital?
Price-to-Earnings of 14.1x: Is it justified?
Granite Real Estate Investment Trust units last closed at CA$82.99, and on a P/E of 14.1x the stock screens as slightly expensive relative to an estimated fair P/E of 13.3x, yet cheaper than many peers in the same space.
The P/E multiple compares what investors pay today for each dollar of earnings. For a logistics and industrial property REIT like Granite Real Estate Investment Trust, this measure gives a quick read on how the market is weighing current profit against expectations for future income from its 145 properties.
GRT.UN trades below several reference points that income investors often check. The P/E of 14.1x is lower than the peer average of 17x and below the Global Industrial REITs industry average of 15.5x, which points to a market valuation that is more restrained than many sector comparables. At the same time, the ratio is modestly higher than the estimated fair P/E of 13.3x, which may indicate that the current tag is a touch richer than the level the fair ratio model identifies as its reference point.
Explore the SWS fair ratio for Granite Real Estate Investment Trust.
Result: Price-to-Earnings of 14.1x (ABOUT RIGHT)
Still, the thesis around Granite Real Estate Investment Trust can crack if industrial property demand weakens or if borrowing costs stay elevated and pressure refinancing terms.
Find out about the key risks to this Granite Real Estate Investment Trust narrative.
Another view on Granite Real Estate Investment Trust's value
The P/E workup nudges Granite Real Estate Investment Trust into the slightly expensive camp, yet the SWS DCF model sends a very different signal. At CA$82.99, units sit well below an estimated future cash flow value of CA$114.44, which frames the current quote as materially undervalued.
This kind of gap can mean the market is pricing in lasting pressure on industrial rents, refinancing terms, or both. It can also mean the cash flow model is too generous. The question for income investors is simple: Which story do you trust more, the earnings multiple or the long range cash view?
Look into how the SWS DCF model arrives at its fair value.
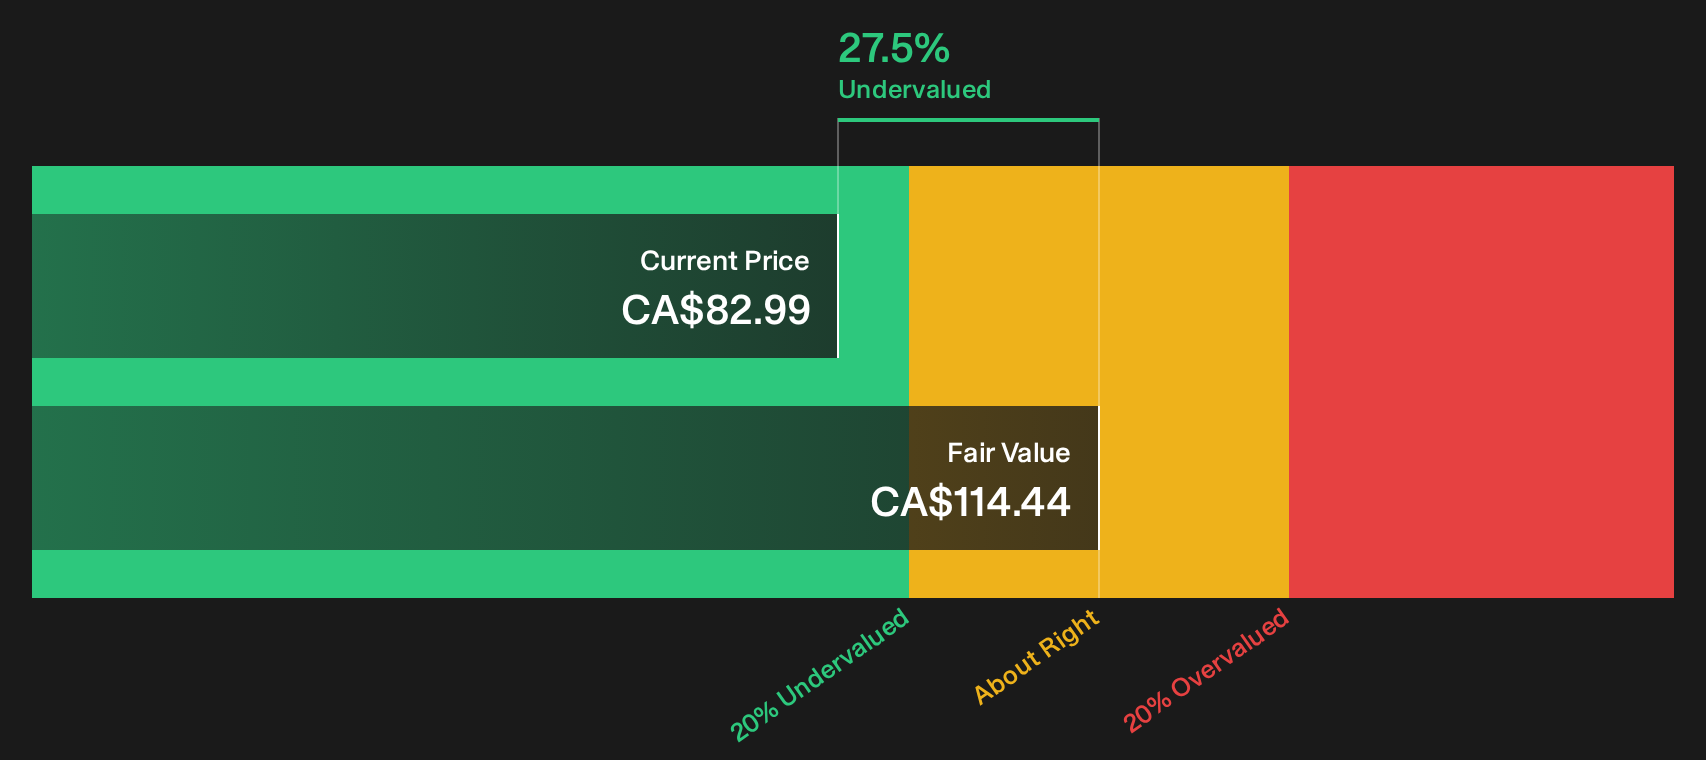
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Granite Real Estate Investment Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mixed signals around Granite Real Estate Investment Trust and its valuation? Act while the data is fresh and form your own stance using the full picture of risks and potential rewards in the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Granite Real Estate Investment Trust?
If Granite Real Estate Investment Trust has your attention, do not stop here. Use focused screeners to uncover fresh opportunities that match your income and risk preferences.
- Spot potential value candidates early by scanning 9 high quality undiscovered gems that pair solid fundamentals with room for the story to develop.
- Build a cash flow oriented watchlist by zeroing in on consistent payers in the 1 dividend fortresses that aim to keep income flowing.
- Sleep easier on volatility days by filtering for 8 resilient stocks with low risk scores with more resilient profiles and historically steadier trading action.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com